Full Report
The numbers behind EPAM Systems, Inc.: as-reported financial statements and company metrics for FY2021–FY2025, traced to the source filings, opened with the share-price history those statements have to justify. Every linked figure opens the exact page of the filing it was printed on, with the statement row highlighted. Amounts in US$ thousands unless noted.
Reading notes: All figures are as printed in EPAM's SEC filings, in thousands of US dollars (statements are captioned "In thousands, except per share data"). Revenue by Industry Vertical is the consolidated column of the segment-reconciliation disaggregation note; each year is cited to that year's own Form 10-K. The 'Consumer Goods, Retail and Travel' vertical was labeled 'Travel Consumer' in the FY2021–FY2023 filings (identical amounts); the current label is used for the row. FY2019 and FY2020 long-term figures are cited to the comparative columns of the FY2021 Form 10-K; FY2016–FY2018 are from the standardized SEC XBRL data feed and are shown without page links. Quarterly cash-flow single quarters are derived from the printed year-to-date 10-Q statements and reconcile exactly to data/financials/cash_flow_quarterly.json. Q4 FY25 is omitted because the fiscal-year 10-K does not print a standalone fourth-quarter income statement.
Share Price — Full Available History — 14 Years
The stock closed at $86.38 on Jul 13, 2026 — up 517% over the window shown (+13.4% a year), trading between $13.40 and $717.49. At that close the stock trades at 13× FY2025 diluted EPS as reported below.
Source: market price feed, monthly closes, sampled from 3,626 source observations, Feb 2012–Jul 2026. Price return only, excludes dividends. Note: the series shows a 46% single-day move around 2022-02-28 that may be an unadjusted corporate action — no split record was available to verify.
FY2025 at a Glance
Revenue (US$ thousands)
Net income (US$ thousands)
Diluted EPS
Source: FY2025 consolidated statements [1] [2] [3] [4]. Click any linked figure to open the filing page with the row highlighted.
Revenue by Industry Vertical
| Revenue by Industry Vertical | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
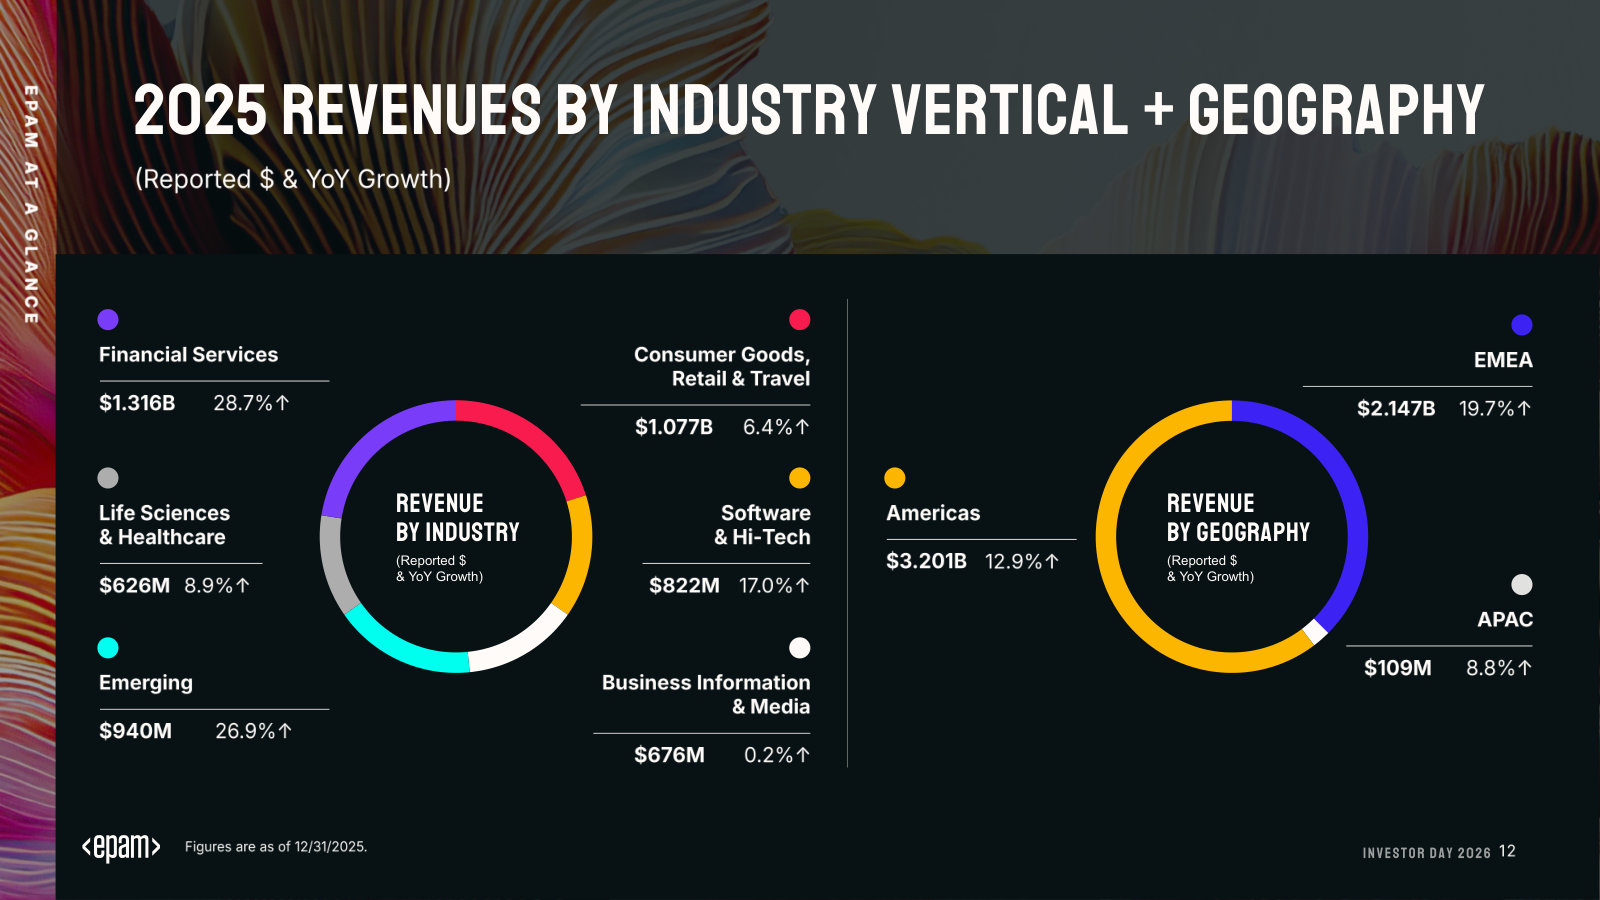
| Financial Services | 848,370 | 1,026,686 | 1,018,433 | 1,022,617 | 1,316,487 |
| Consumer Goods, Retail and Travel | 741,128 | 1,092,224 | 1,072,950 | 1,013,138 | 1,077,513 |
| Software and Hi-Tech | 664,597 | 793,261 | 707,720 | 702,367 | 821,819 |
| Business Information and Media | 666,941 | 809,952 | 753,981 | 674,597 | 675,667 |
| Life Sciences and Healthcare | 391,309 | 507,367 | 489,914 | 574,605 | 625,607 |
| Emerging Verticals | 445,799 | 595,208 | 647,542 | 740,616 | 939,963 |
| Total revenues | 3,758,144 | 4,824,698 | 4,690,540 | 4,727,940 | 5,457,056 |
| Total revenues growth, derived | — | +28.4% | -2.8% | +0.8% | +15.4% |
Source: Note 19 Segment Information — disaggregation of revenues by industry vertical (consolidated); labels shown as reported in the FY2025 Form 10-K [5] [6] [7] [8]. Click any linked figure to open the filing page with the row highlighted.
Income Statement
Source: Consolidated Statements of Income [1] [2] [3] [4]. Click any linked figure to open the filing page with the row highlighted.
Columns marked E are consensus analyst estimates shown alongside reported results for direct comparison; they are not company guidance.
Estimate source: Yahoo Finance analyst consensus, as of 2026-07-14. Estimate figures link to the consensus source, not to filing pages.
Balance Sheet
Source: Consolidated Balance Sheets [9] [10] [11] [12]. Click any linked figure to open the filing page with the row highlighted.
Cash Flow
Source: Consolidated Statements of Cash Flows [13] [14] [15] [16]. Click any linked figure to open the filing page with the row highlighted.
Workforce Delivery Operations
| Workforce Delivery Operations | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
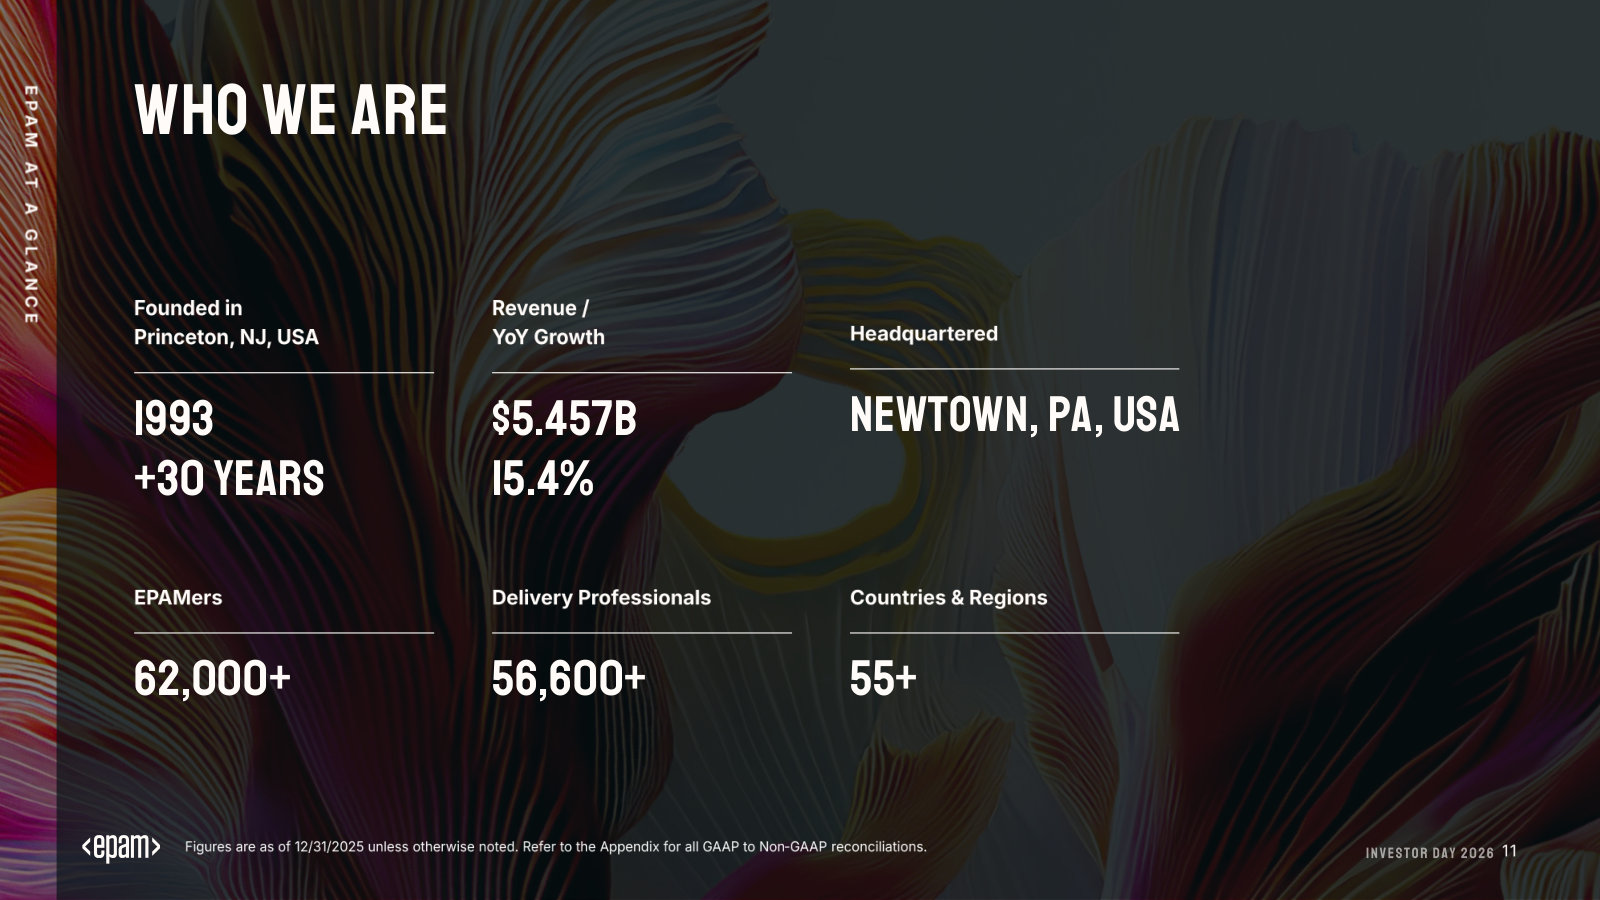
| Total employees | 58,824 | 59,300 | 53,150 | 61,200 | 62,850 |
| Delivery professionals | 52,617 | 52,850 | 47,350 | 55,100 | 56,600 |
| Delivery professional utilization rate | 78.7% | 75.8% | 74.3% | 76.7% | 76.8% |
| Voluntary attrition rate | 13.3% | 13.8% | 8.6% | 8.9% | 8.5% |
Source: company filings [17] [18] [19] [20]. Click any linked figure to open the filing page with the row highlighted.
Client Concentration
| Client Concentration | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Top five clients (revenue) | — | 793,603 | 780,606 | 748,324 | 746,169 |
| Top ten clients (revenue) | — | 1,149,966 | 1,109,033 | 1,107,647 | 1,180,007 |
| Top twenty clients (revenue) | — | 1,698,916 | 1,660,174 | 1,615,267 | 1,742,670 |
| Clients below top twenty (revenue) | — | 3,125,782 | 3,030,366 | 3,112,673 | 3,714,386 |
Source: company filings [21] [22]. Click any linked figure to open the filing page with the row highlighted.
Revenue by Client Location
| Revenue by Client Location | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Americas | 2,226,830 | 2,887,204 | 2,742,662 | 2,834,704 | 3,200,924 |
| EMEA | 1,259,717 | 1,737,919 | 1,822,782 | 1,793,198 | 2,147,304 |
| APAC | 103,559 | 120,370 | 102,138 | 100,038 | 108,828 |
| CEE (folded into EMEA from FY2024) | 168,038 | 79,205 | 22,958 | — | — |
Source: company filings [21] [22] [23] [24]. Click any linked figure to open the filing page with the row highlighted.
Long-Term Record
| Fiscal year | Total revenue | Income from operations | Net income | Diluted EPS | Operating cash flow |
|---|---|---|---|---|---|
| FY2016 | 1,160,132 | 133,696 | 99,266 | 1.87 | 167,217 |
| FY2017 | 1,450,448 | 172,946 | 72,760 | 1.32 | 192,820 |
| FY2018 | 1,842,912 | 245,764 | 240,256 | 4.24 | 292,218 |
| FY2019 | 2,293,798 | 302,850 | 261,057 | 4.53 | 287,453 |
| FY2020 | 2,659,478 | 379,324 | 327,160 | 5.60 | 544,407 |
| FY2021 | 3,758,144 | 542,316 | 481,652 | 8.15 | 572,327 |
| FY2022 | 4,824,698 | 572,966 | 419,416 | 7.09 | 464,104 |
| FY2023 | 4,690,540 | 501,239 | 417,083 | 7.06 | 562,634 |
| FY2024 | 4,727,940 | 544,584 | 454,533 | 7.84 | 559,168 |
| FY2025 | 5,457,056 | 520,003 | 377,678 | 6.72 | 654,934 |
Source: consolidated statements across filings; older years from the standardized feed [13] [1] [14] [2]. Click any linked figure to open the filing page with the row highlighted.
Operating KPIs
| KPI | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Delivery professionals | 52,600 | 52,850 | 47,350 | 55,100 | 56,600 |
| Total employees | 58,800 | 59,300 | 53,150 | 61,200 | 62,850 |
Source: company-reported operating metrics [18] [25]. Click any linked figure to open the filing page with the row highlighted.
Analyst Consensus
Current price
Mean target
Median target
High target
Low target
Estimate source: Yahoo Finance analyst consensus, as of 2026-07-14. Estimate figures link to the consensus source, not to filing pages.
Traceability
341 of 356 figures on this page (96%) link to the filing page where they are printed — click a linked figure to open the source PDF at that page with the row highlighted. Unlinked figures come from standardized data feeds or pre-filing years.
All figures are as printed in EPAM's SEC filings, in thousands of US dollars (statements are captioned "In thousands, except per share data").
Revenue by Industry Vertical is the consolidated column of the segment-reconciliation disaggregation note; each year is cited to that year's own Form 10-K. The 'Consumer Goods, Retail and Travel' vertical was labeled 'Travel Consumer' in the FY2021–FY2023 filings (identical amounts); the current label is used for the row.
FY2019 and FY2020 long-term figures are cited to the comparative columns of the FY2021 Form 10-K; FY2016–FY2018 are from the standardized SEC XBRL data feed and are shown without page links.
Quarterly cash-flow single quarters are derived from the printed year-to-date 10-Q statements and reconcile exactly to data/financials/cash_flow_quarterly.json. Q4 FY25 is omitted because the fiscal-year 10-K does not print a standalone fourth-quarter income statement.
EPAM pays no dividend; no dividend line is shown.
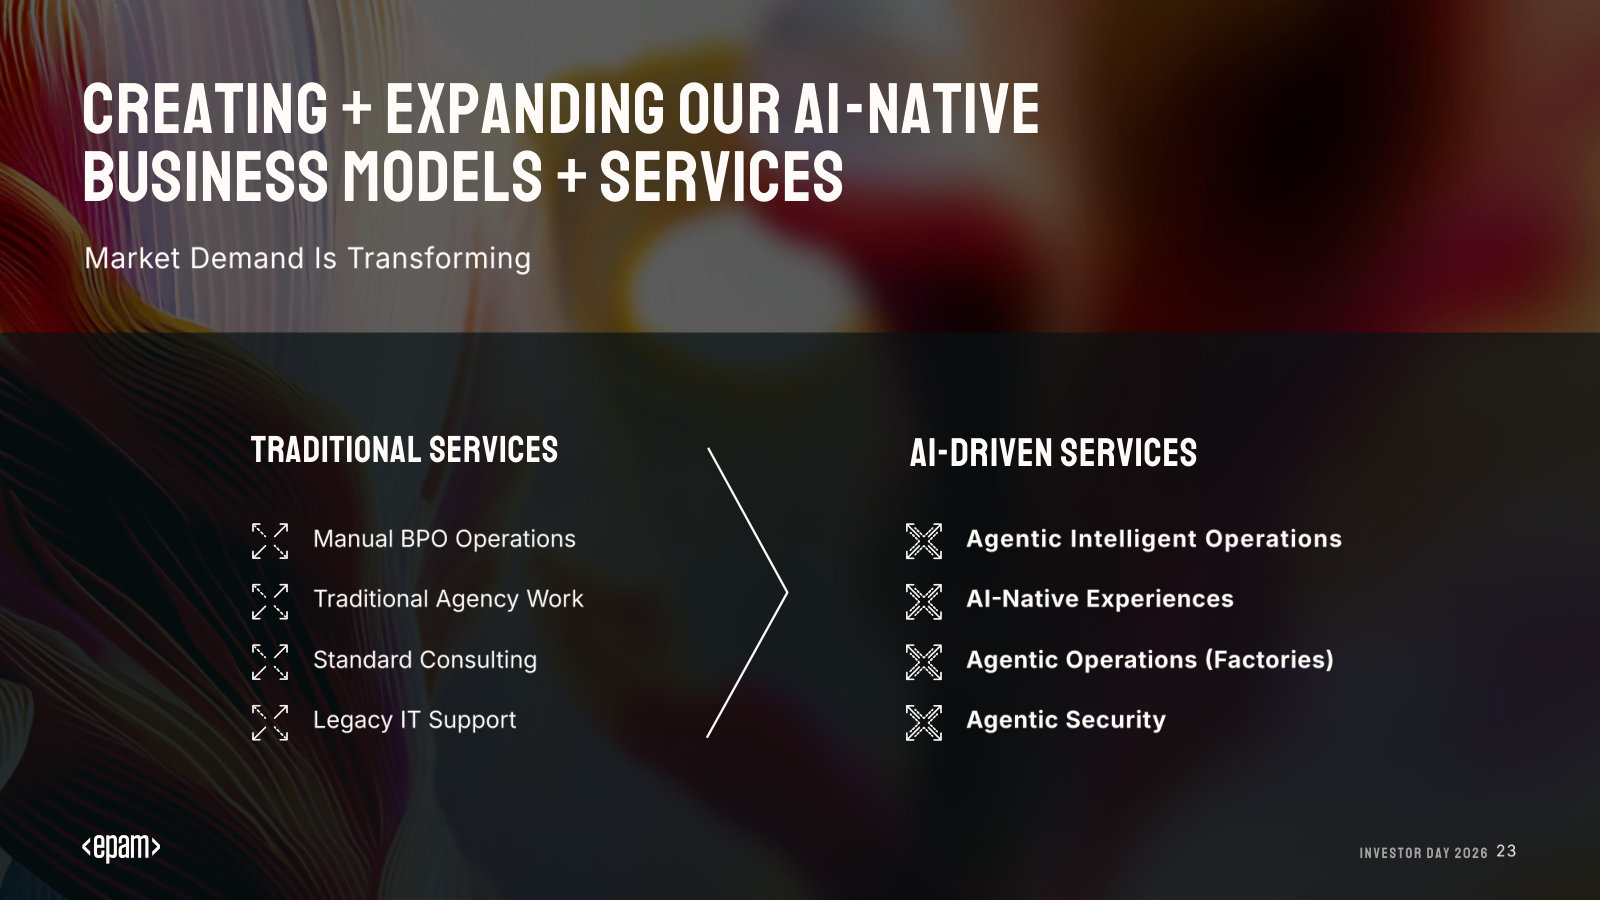
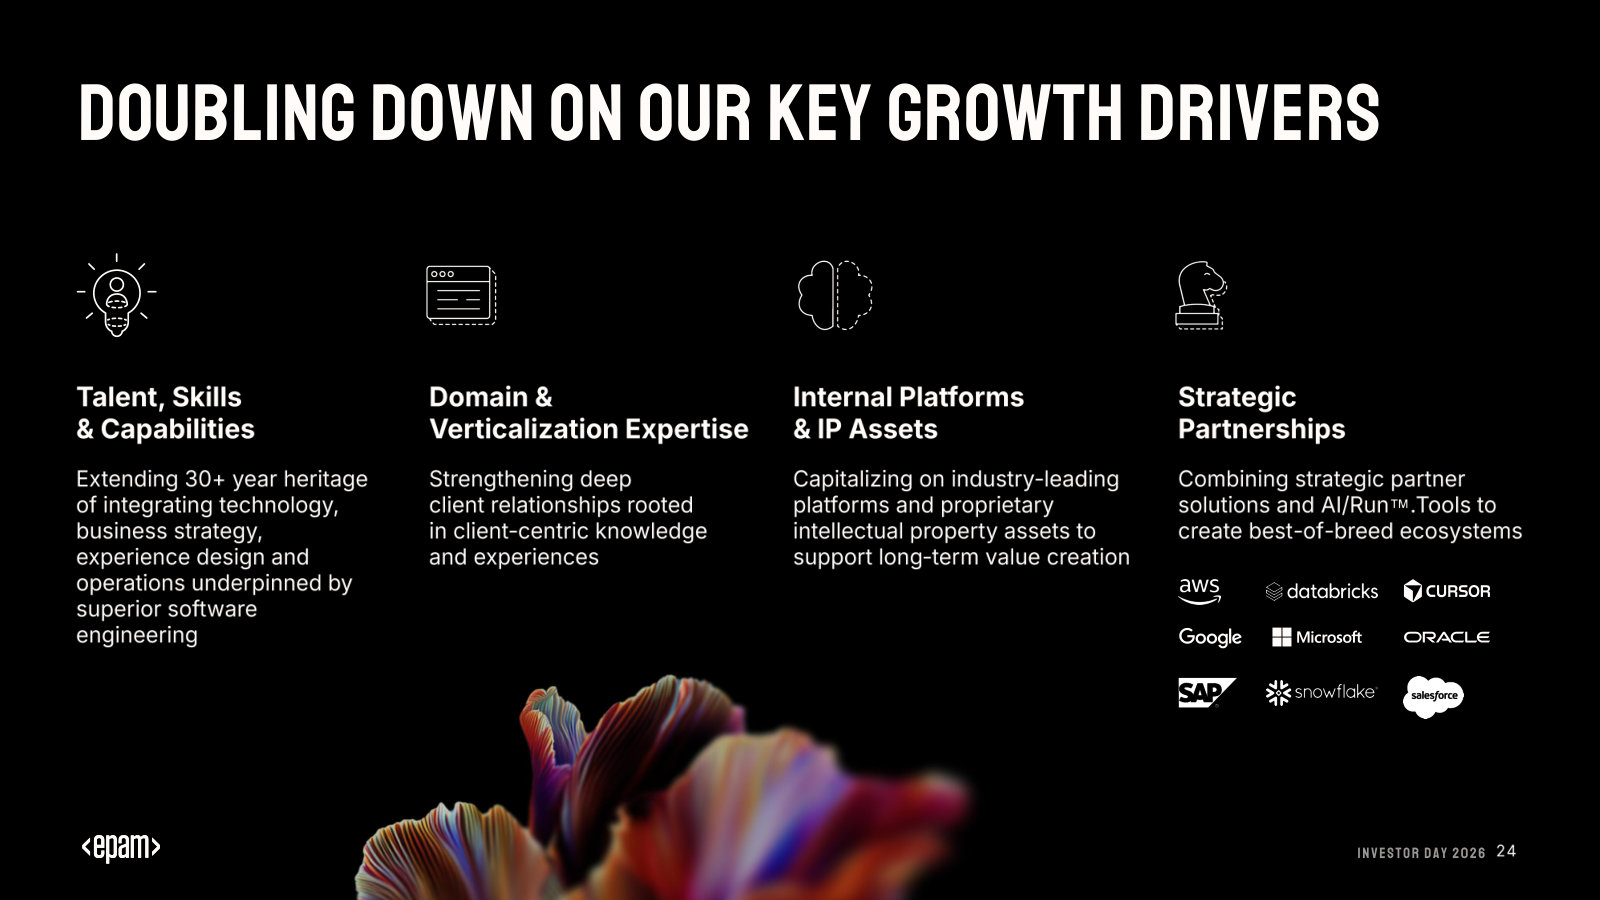
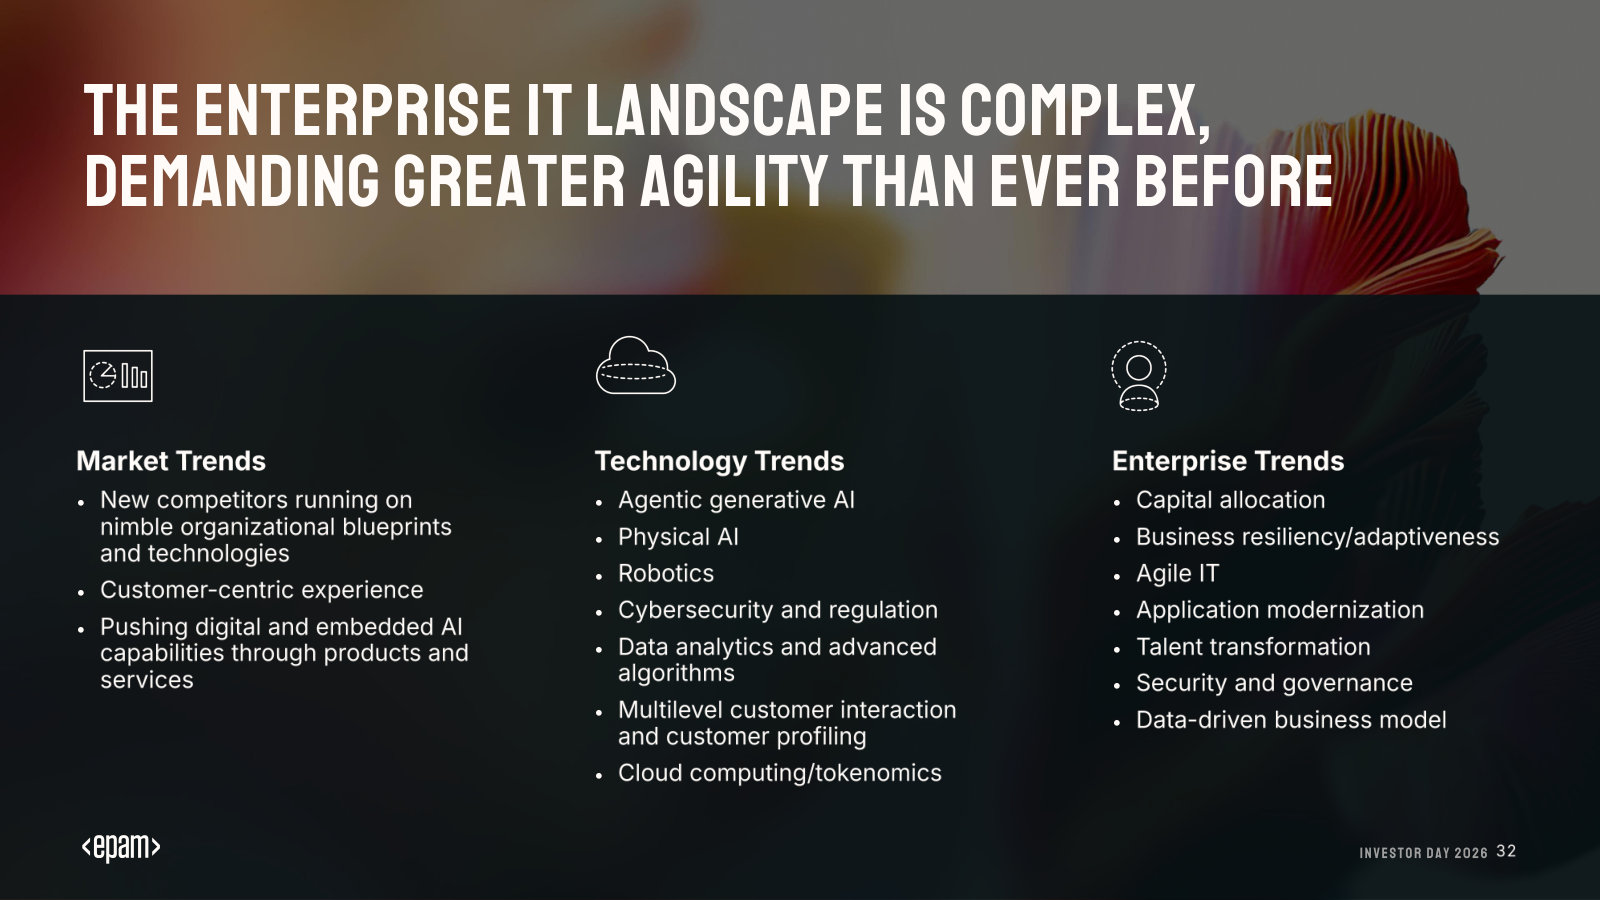
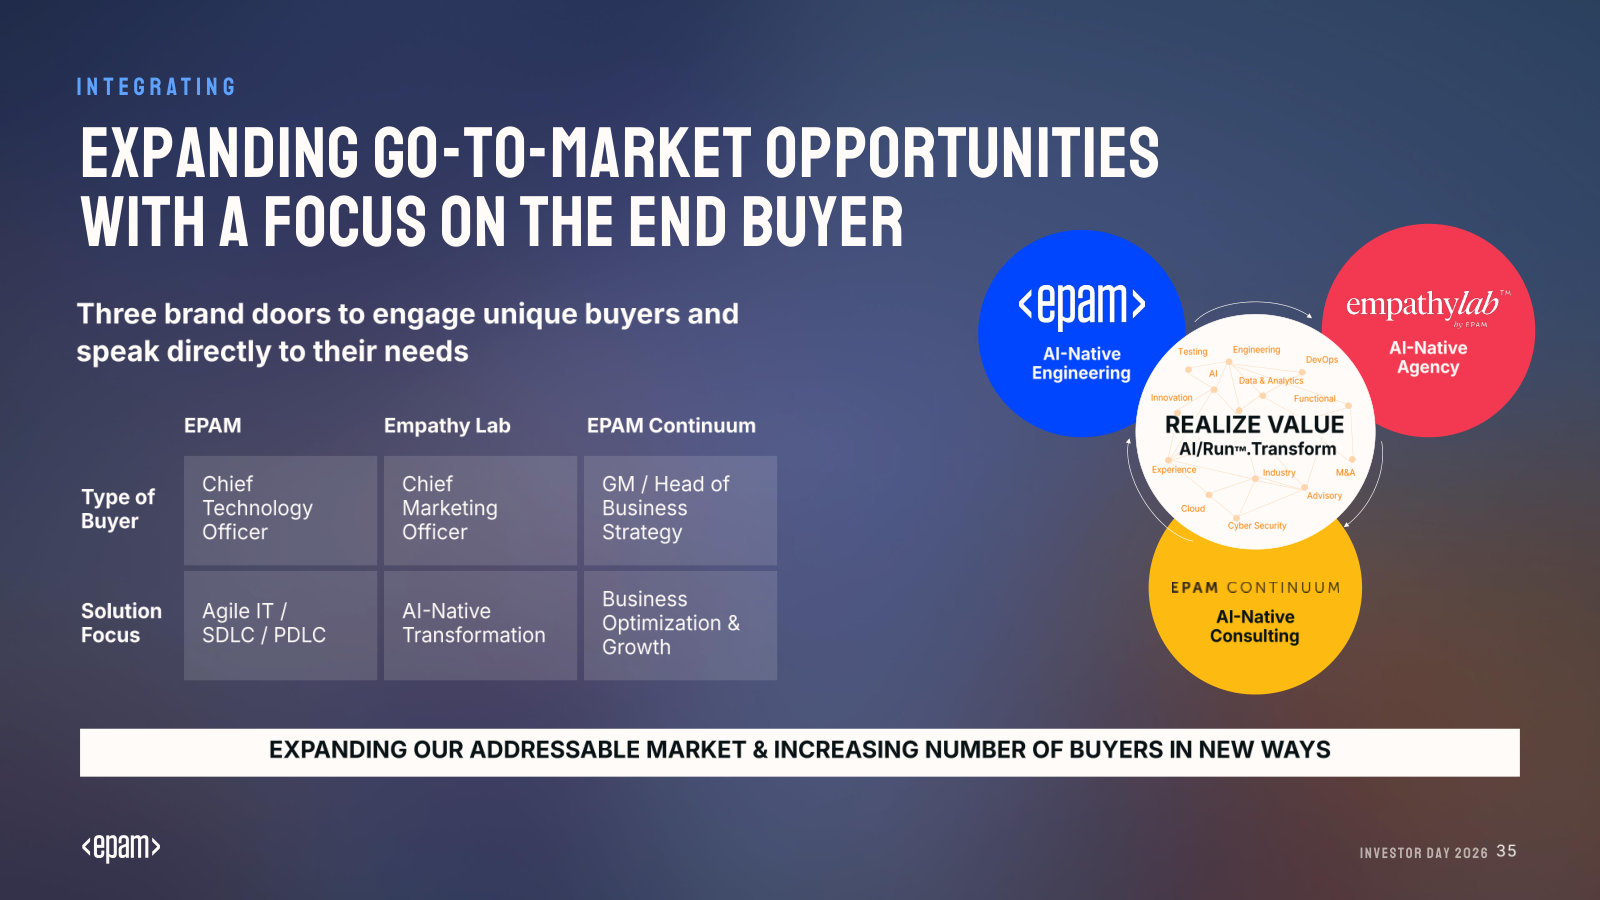
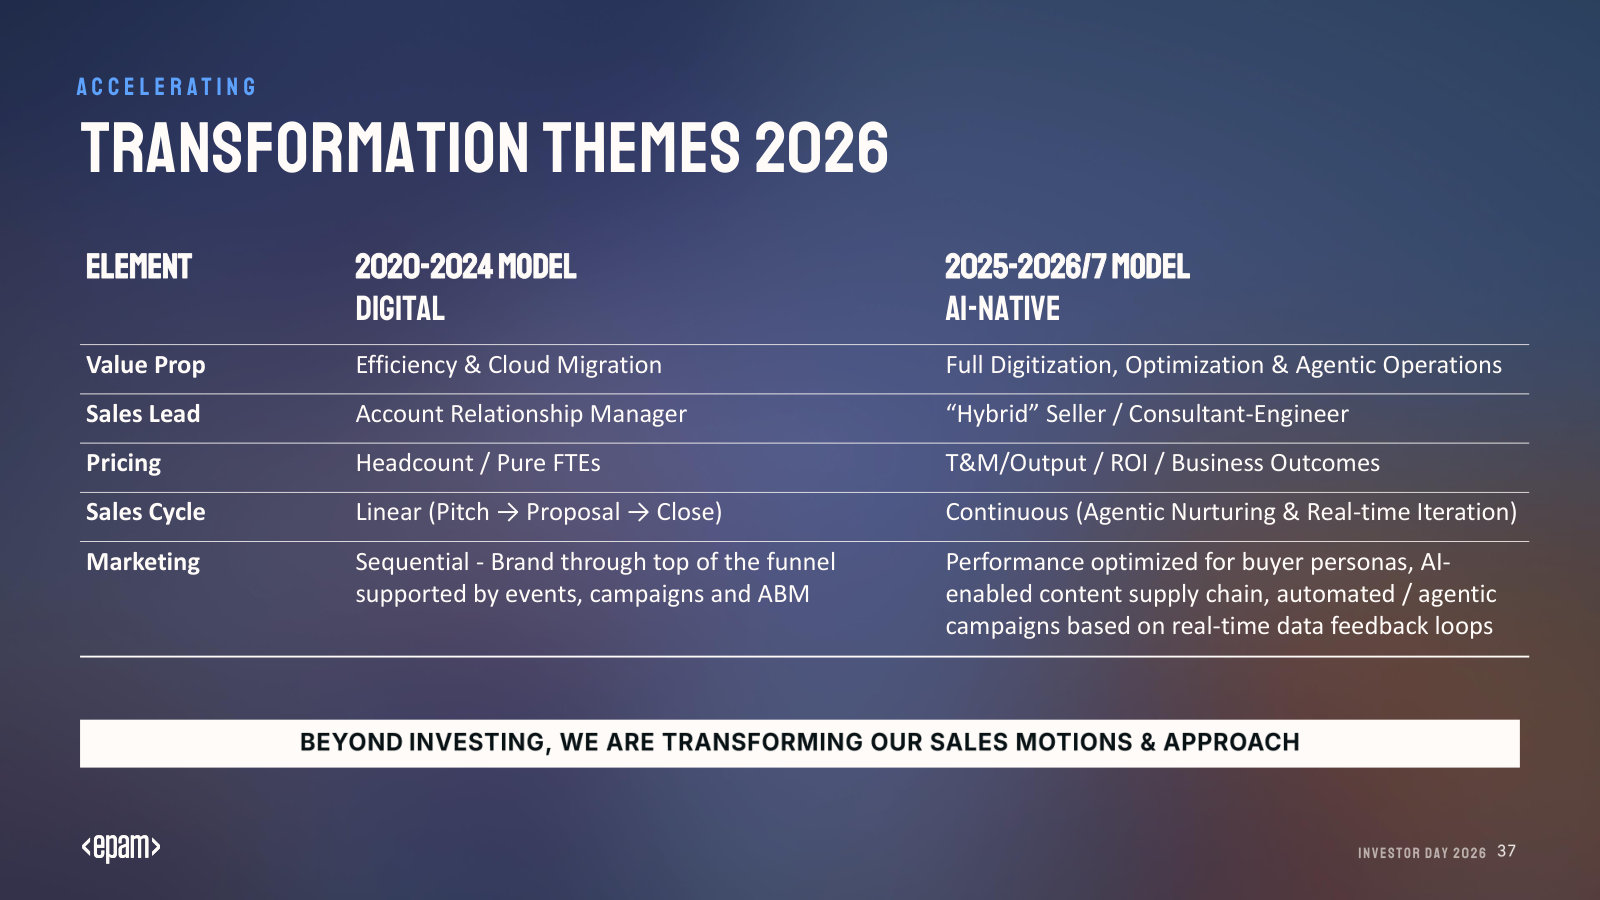
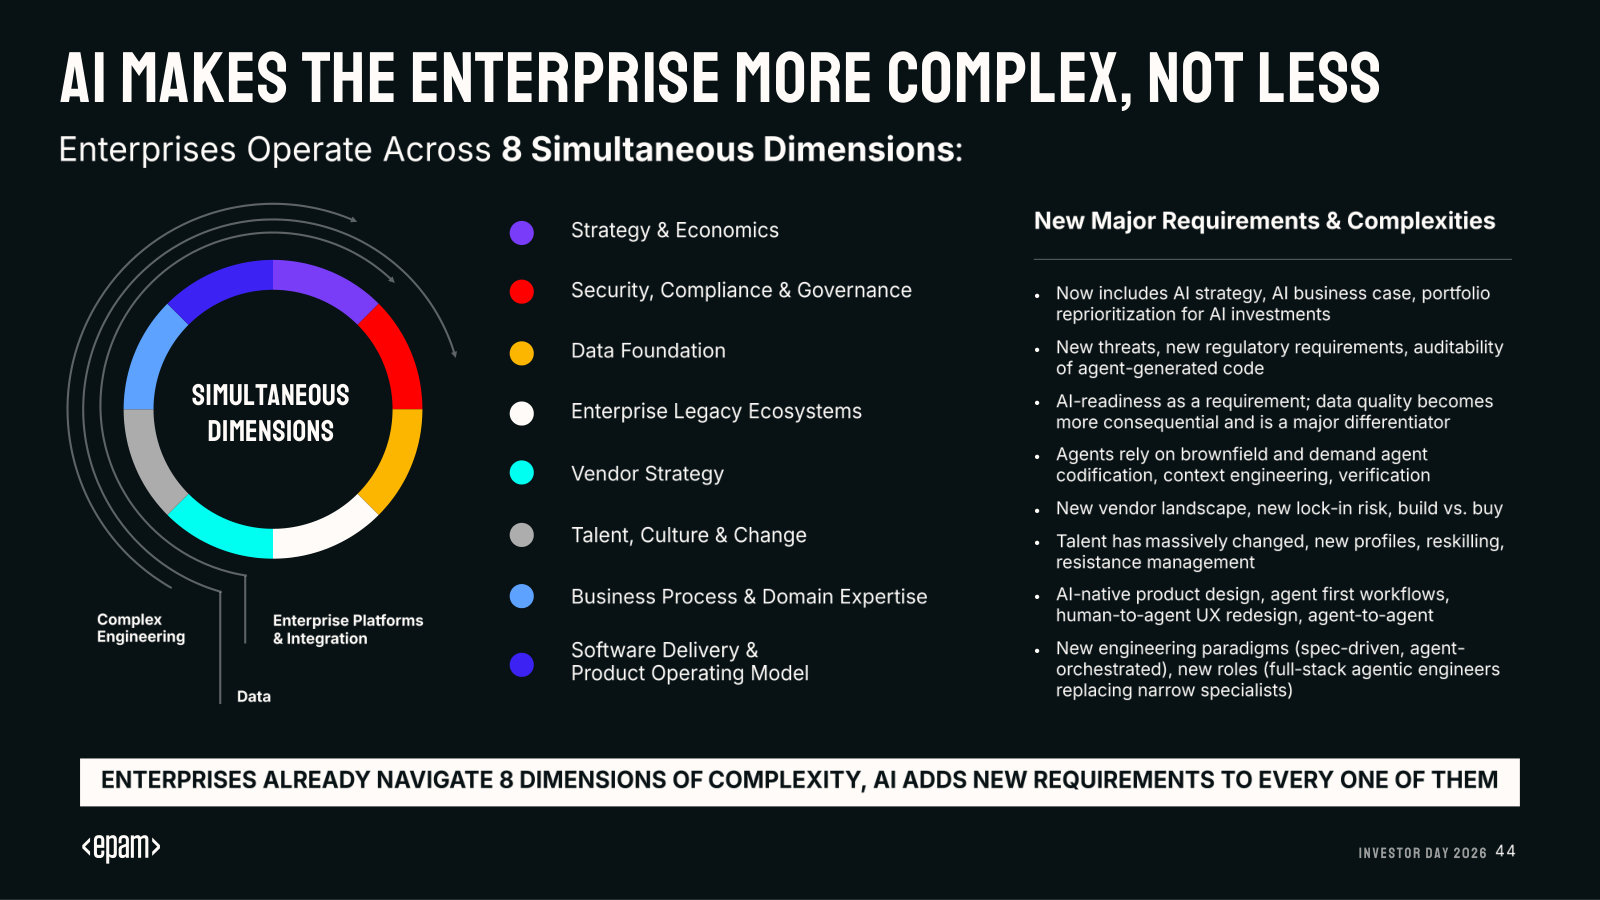
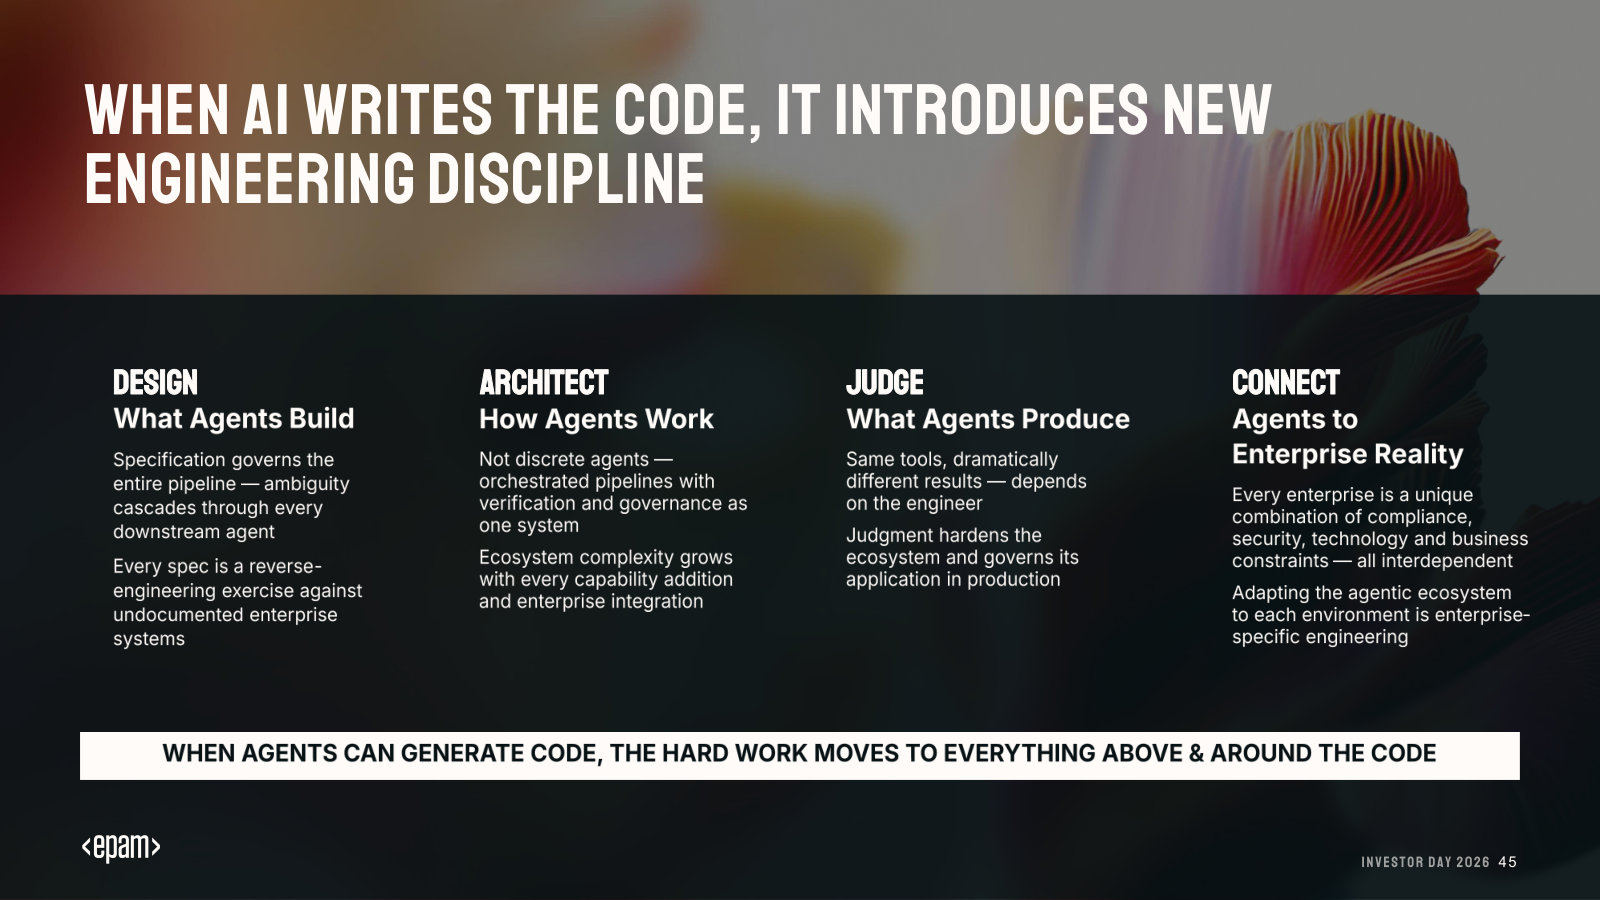
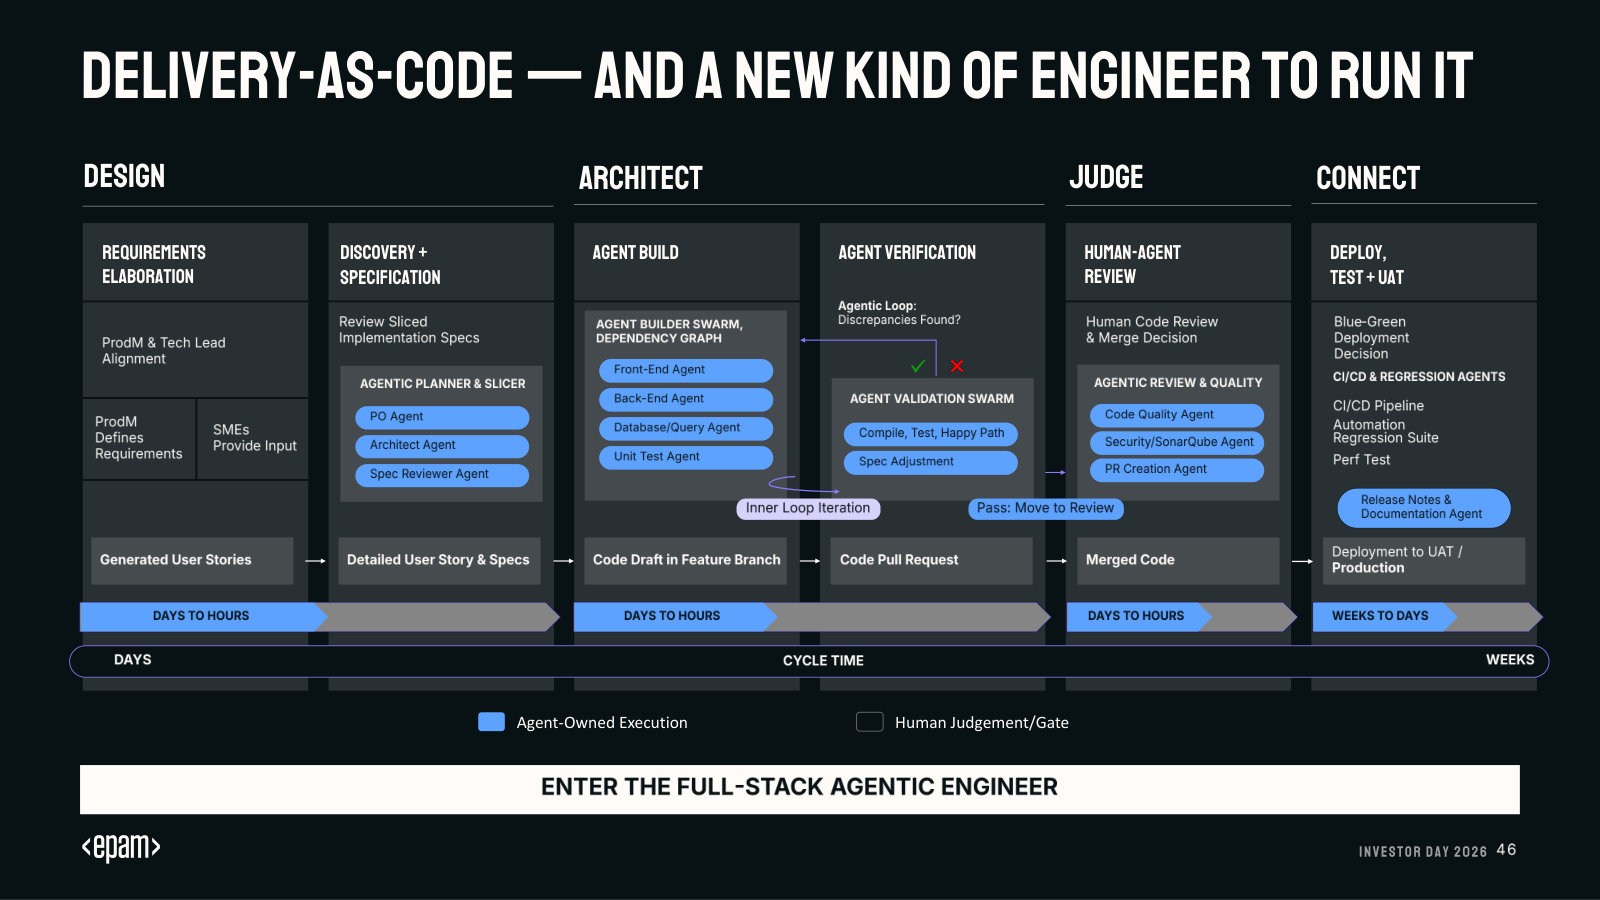
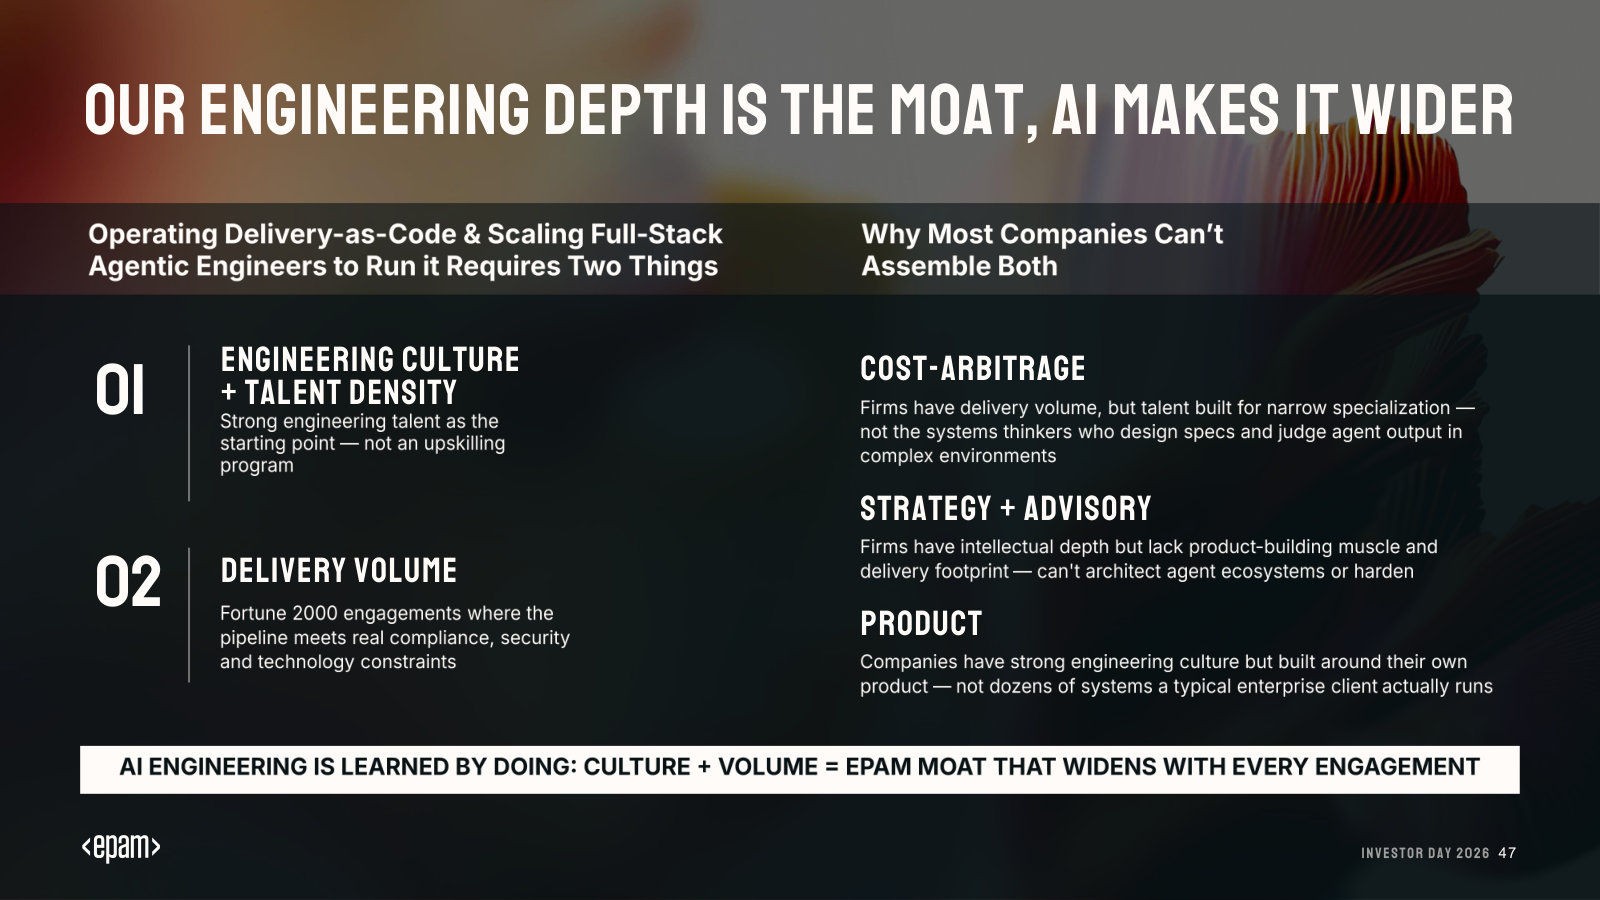
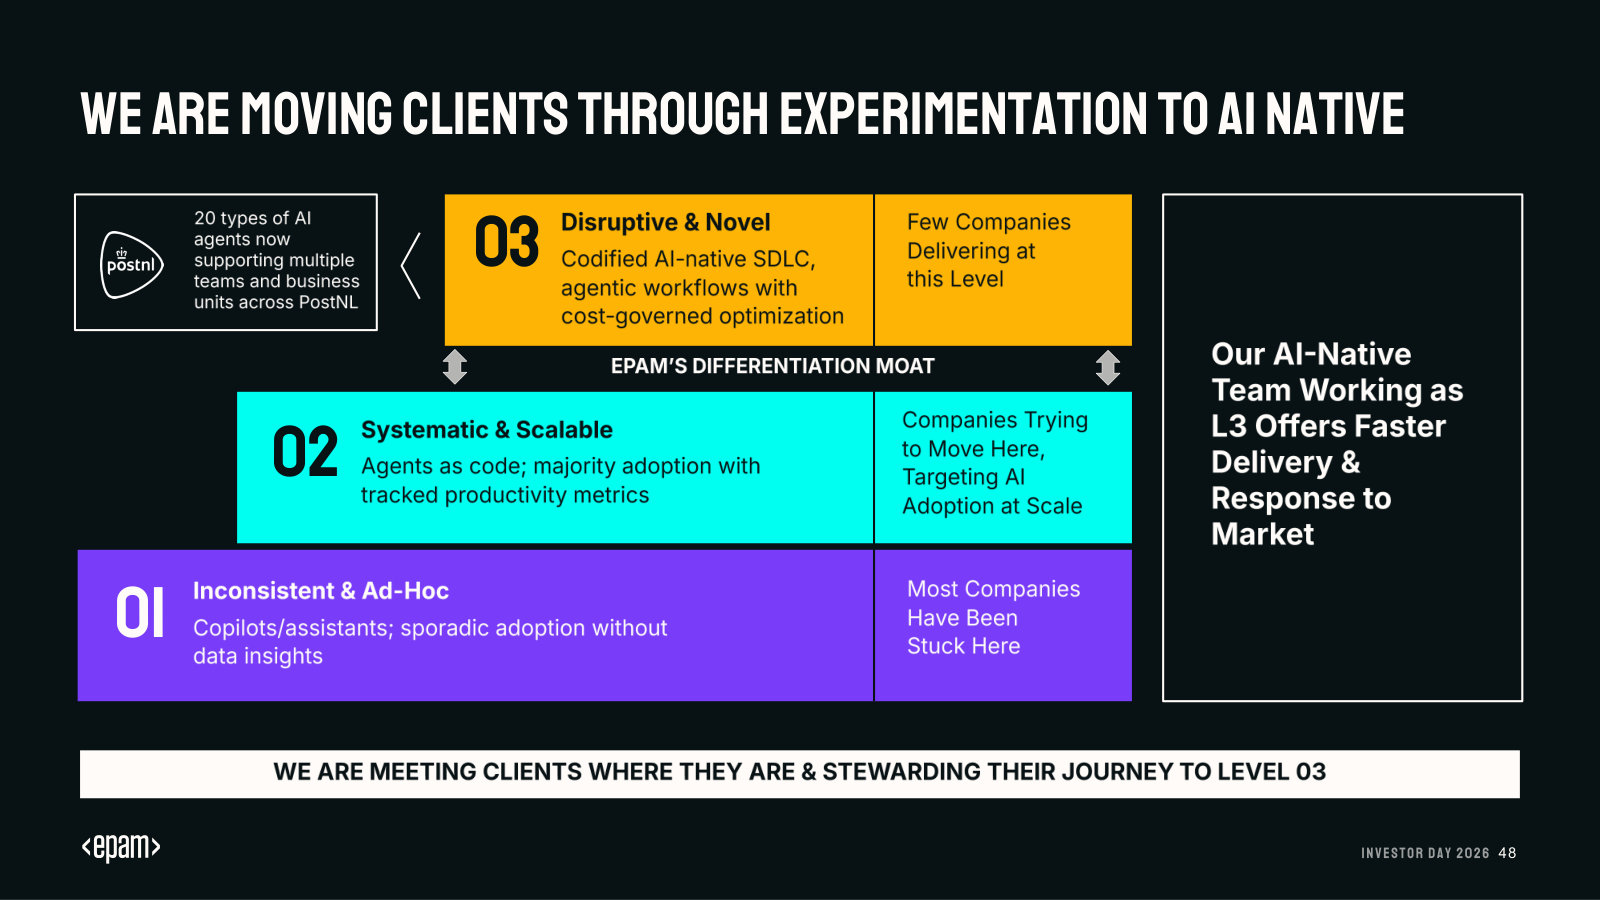
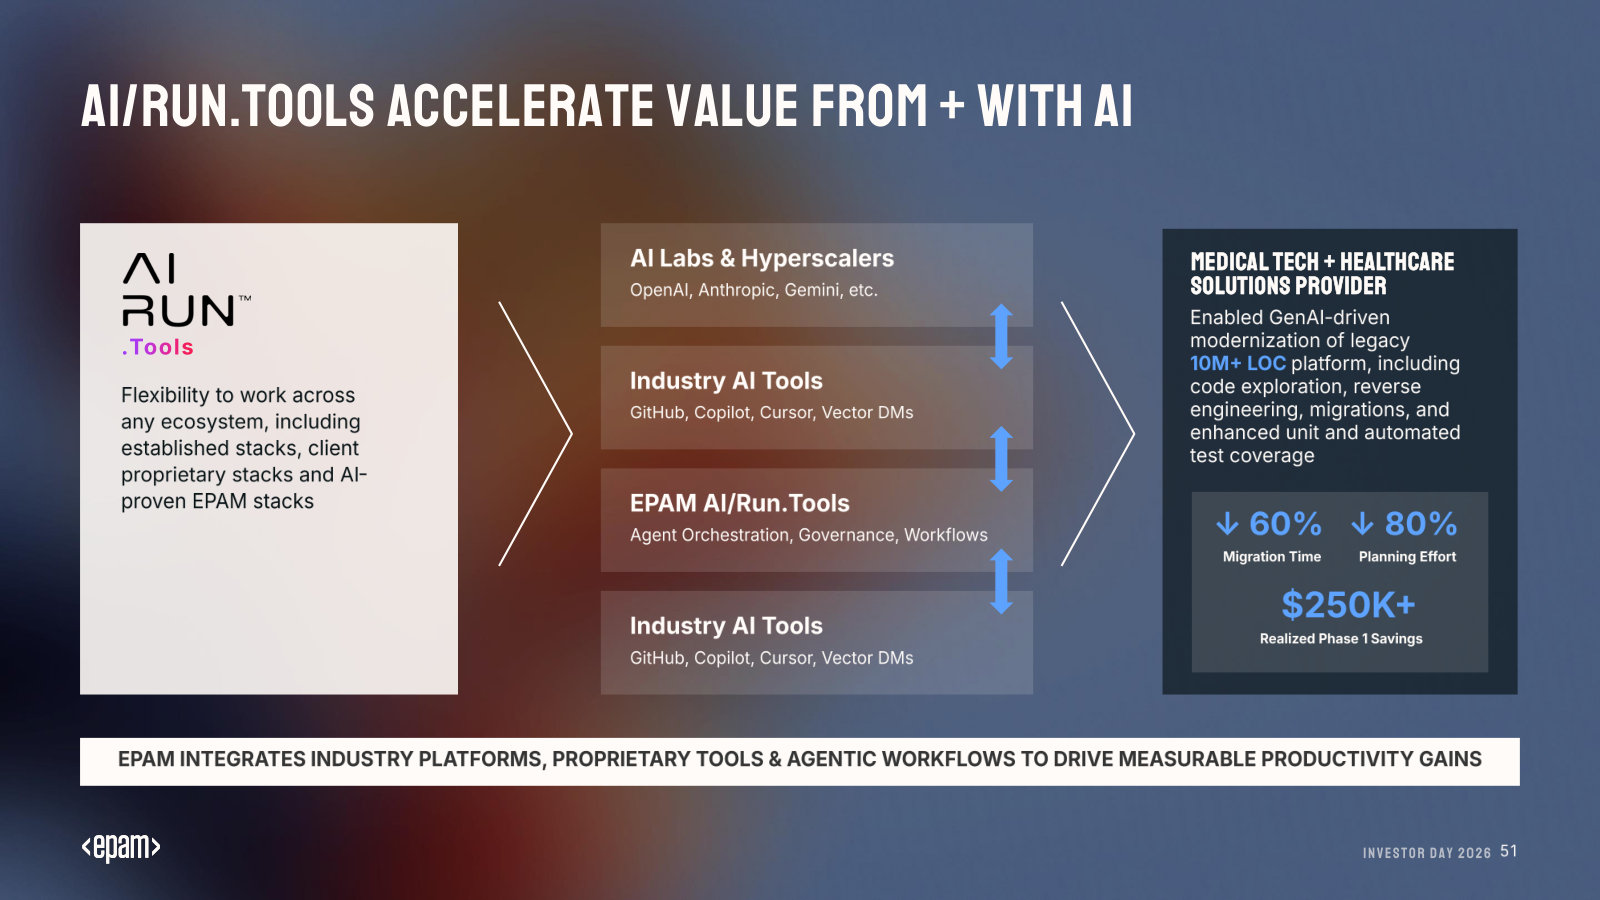
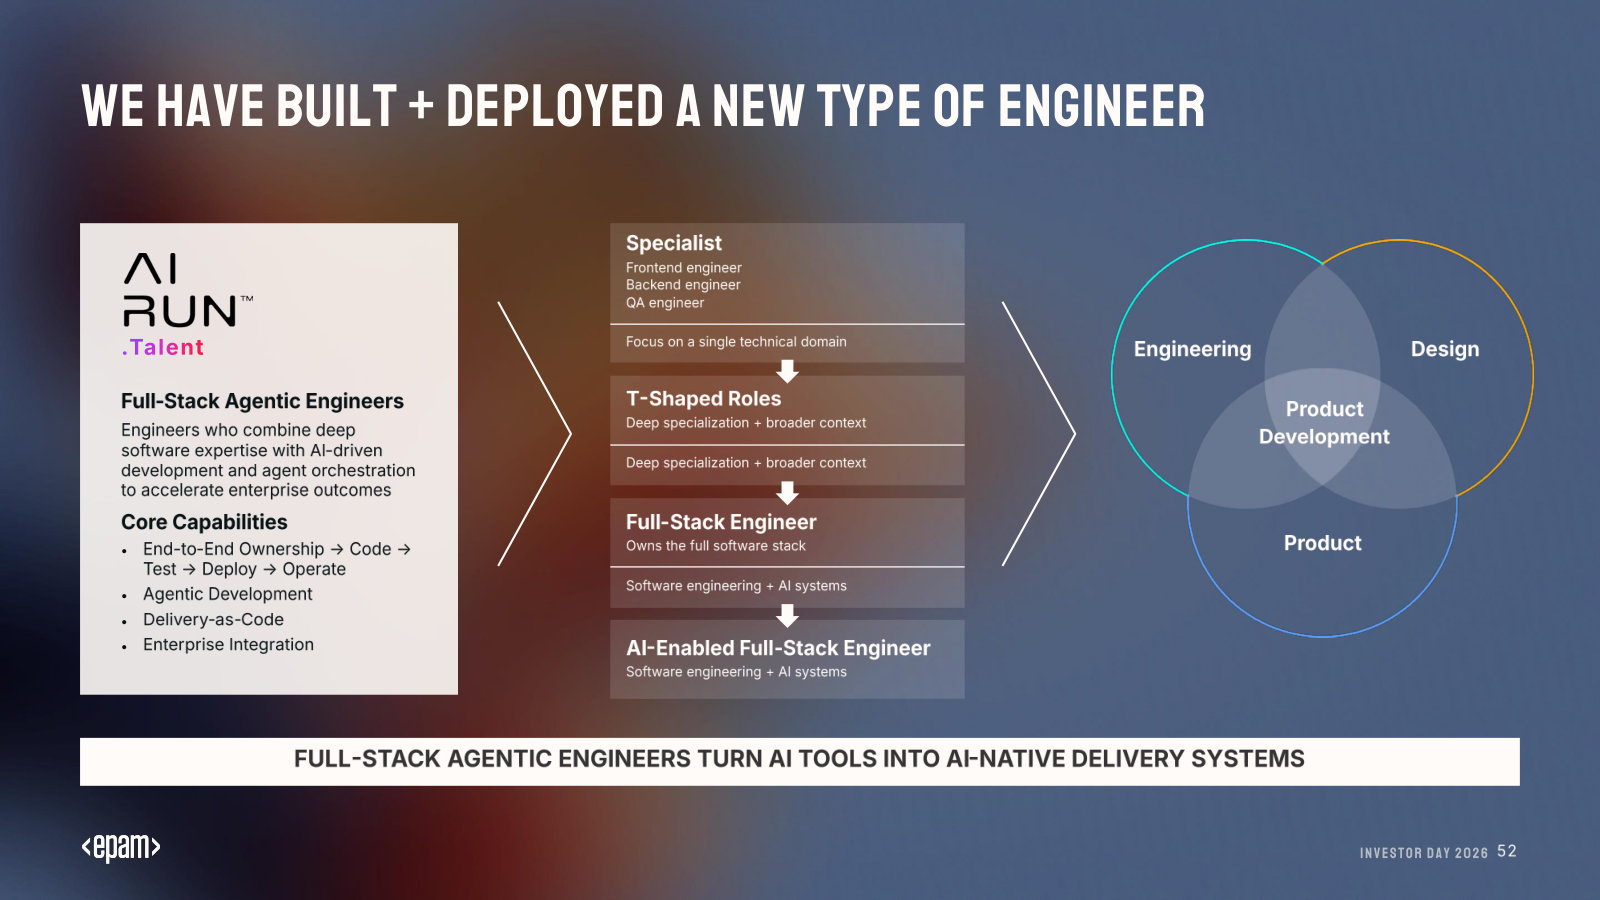
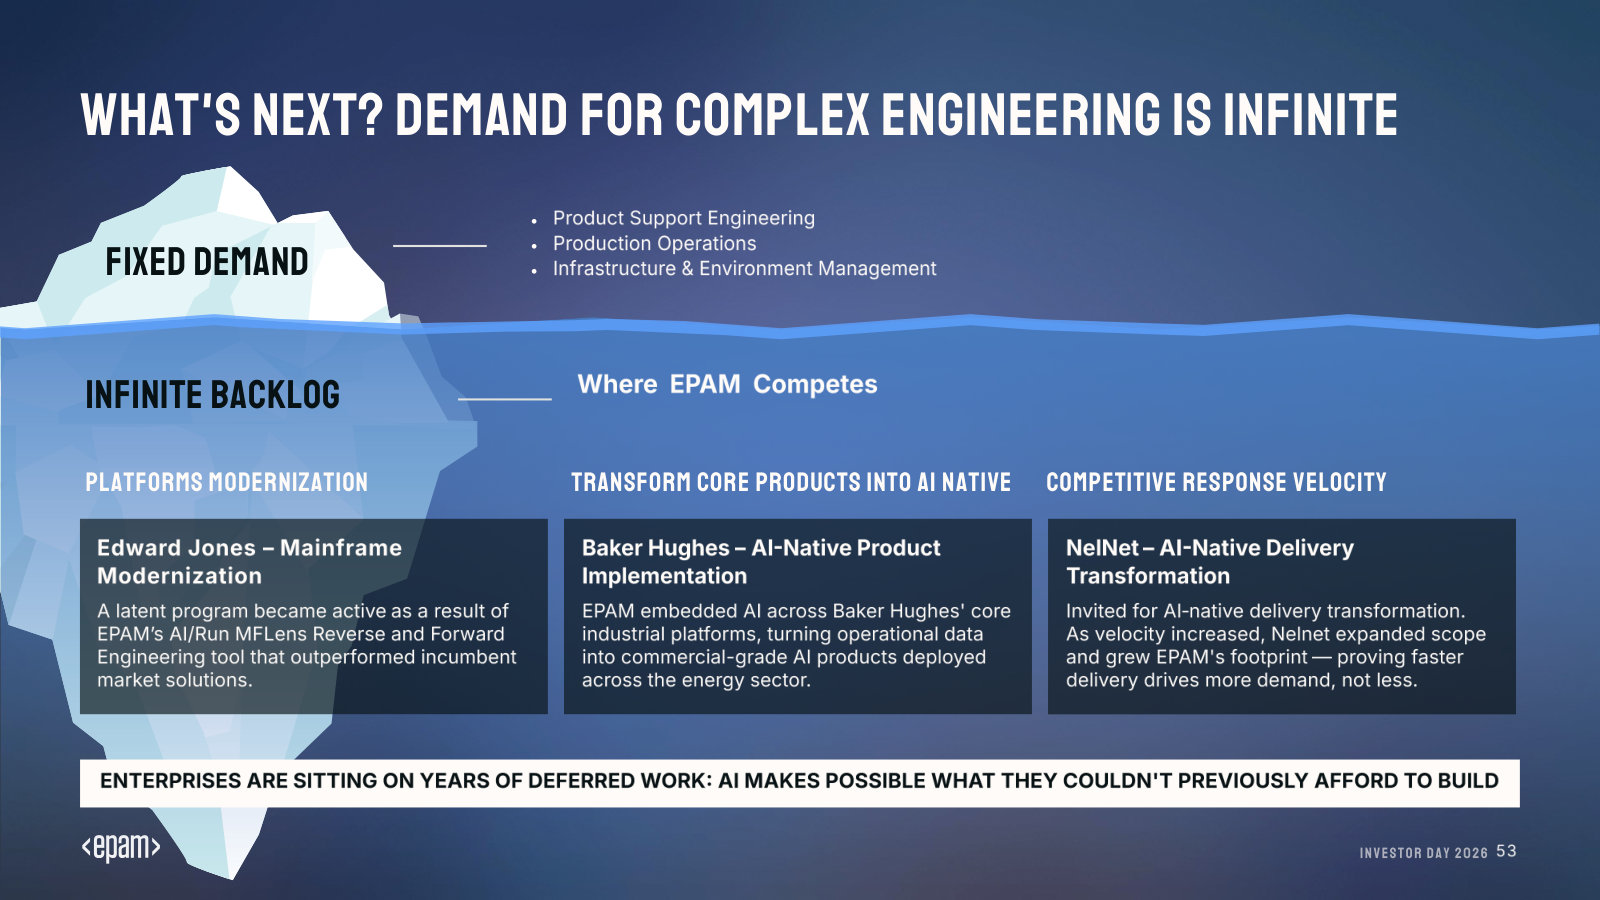
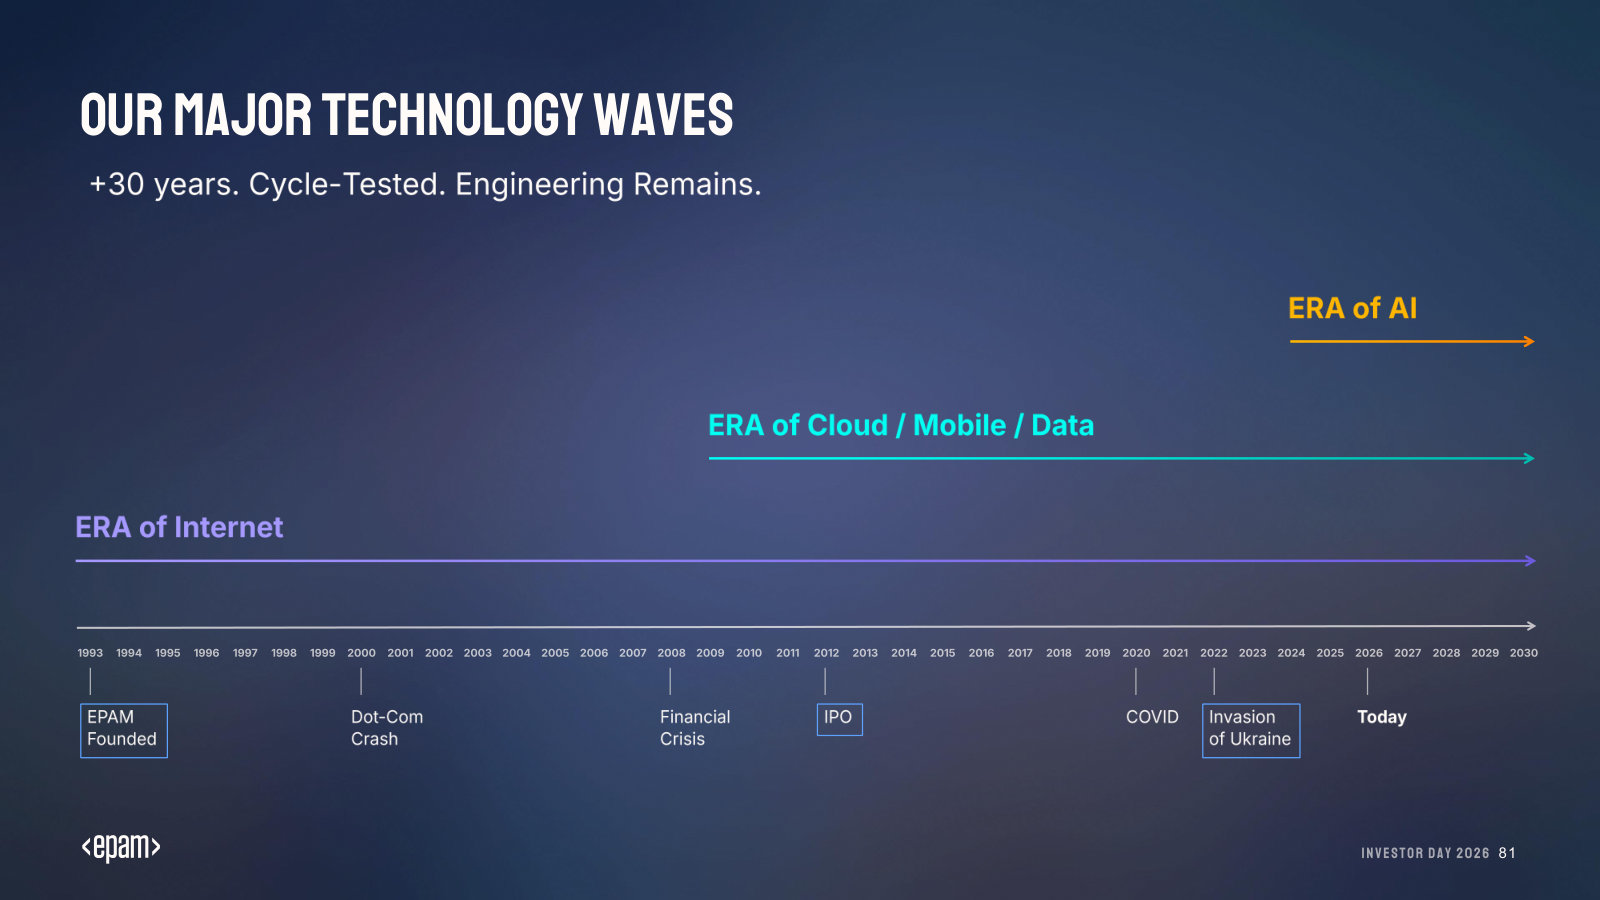
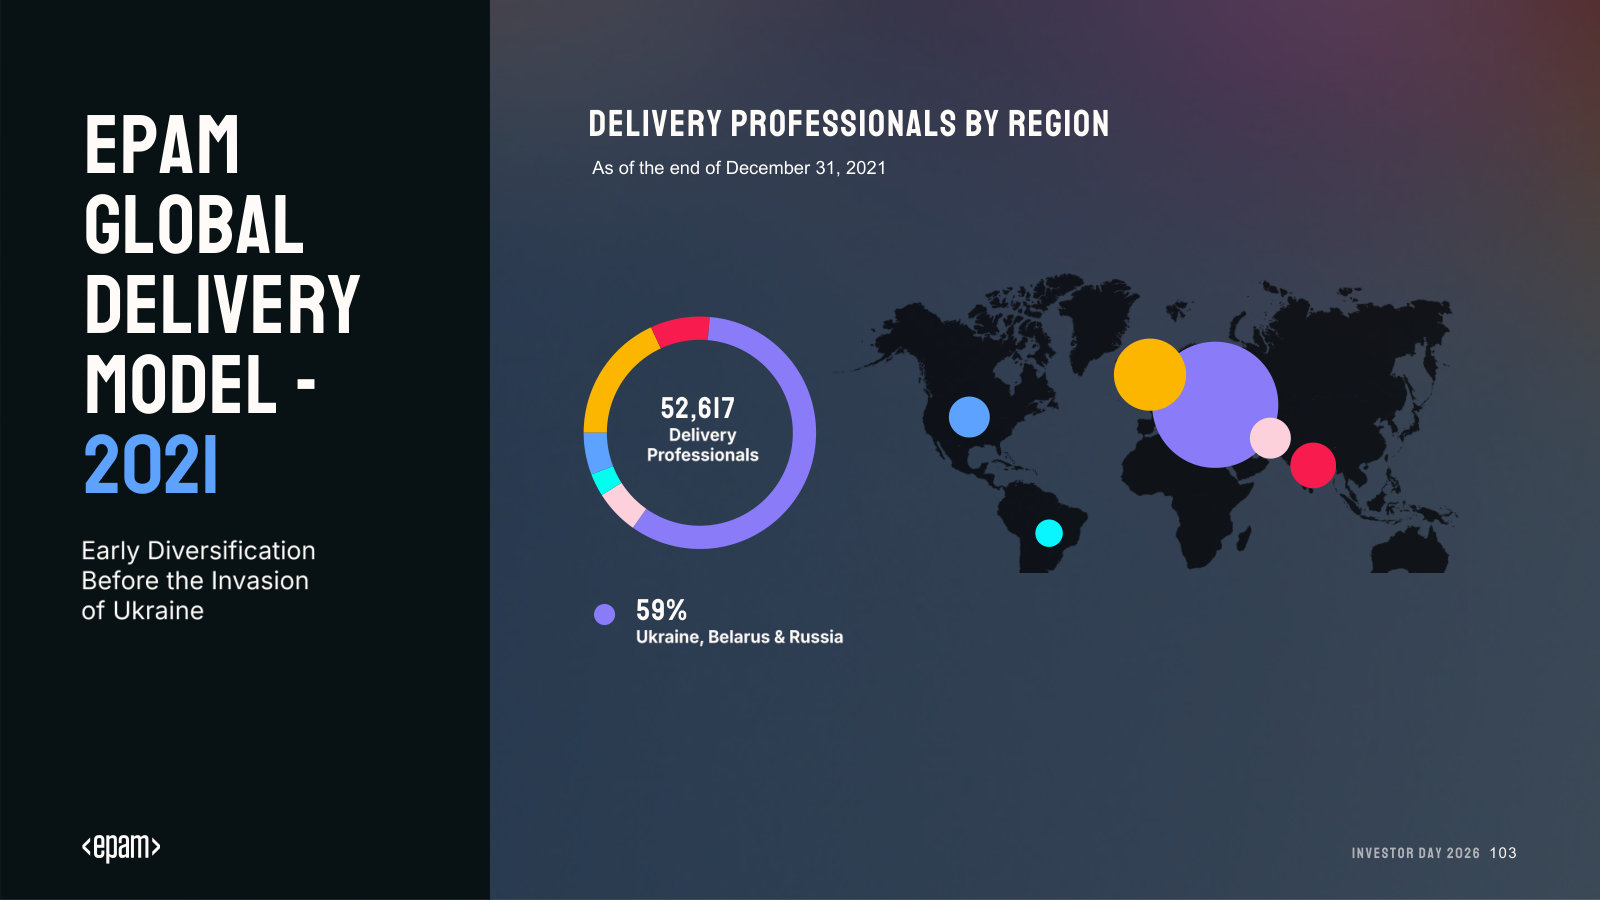
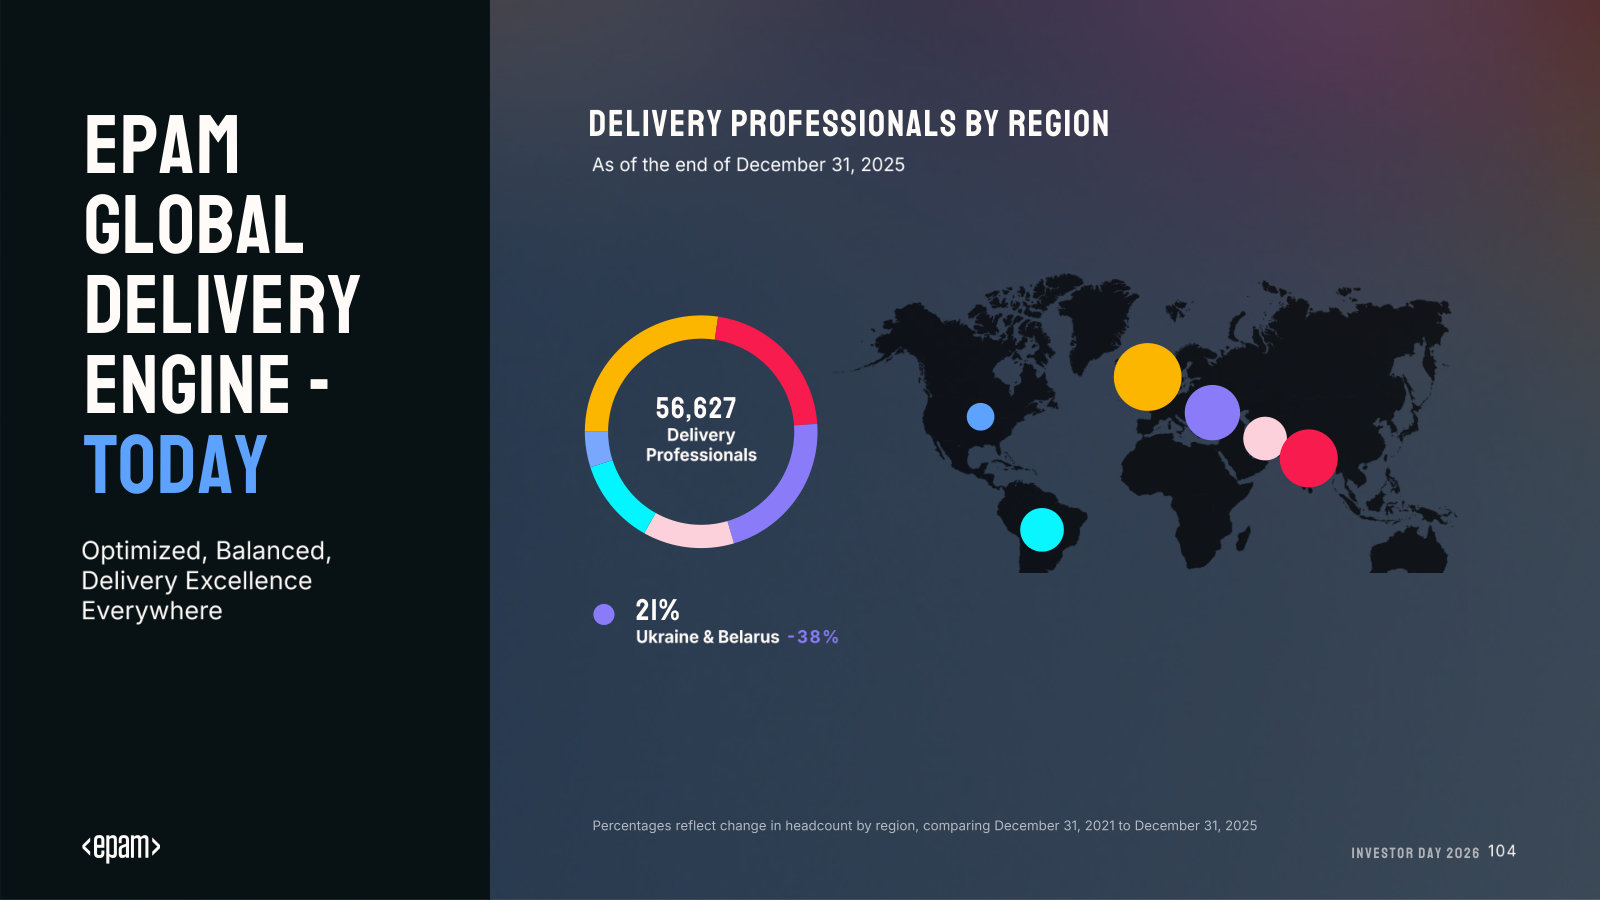
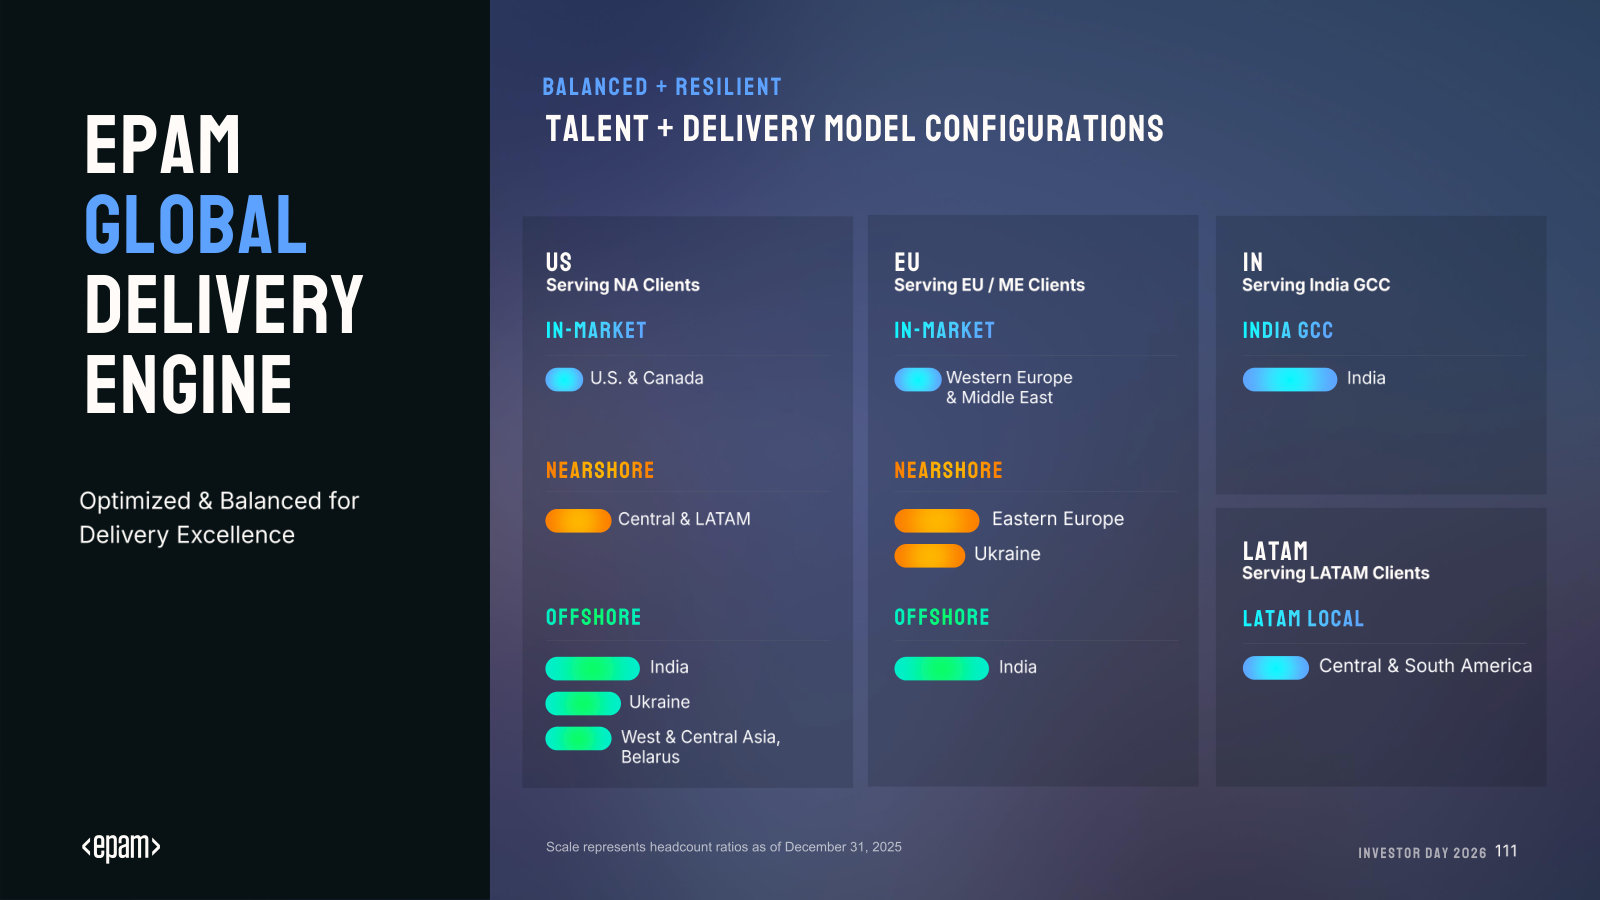
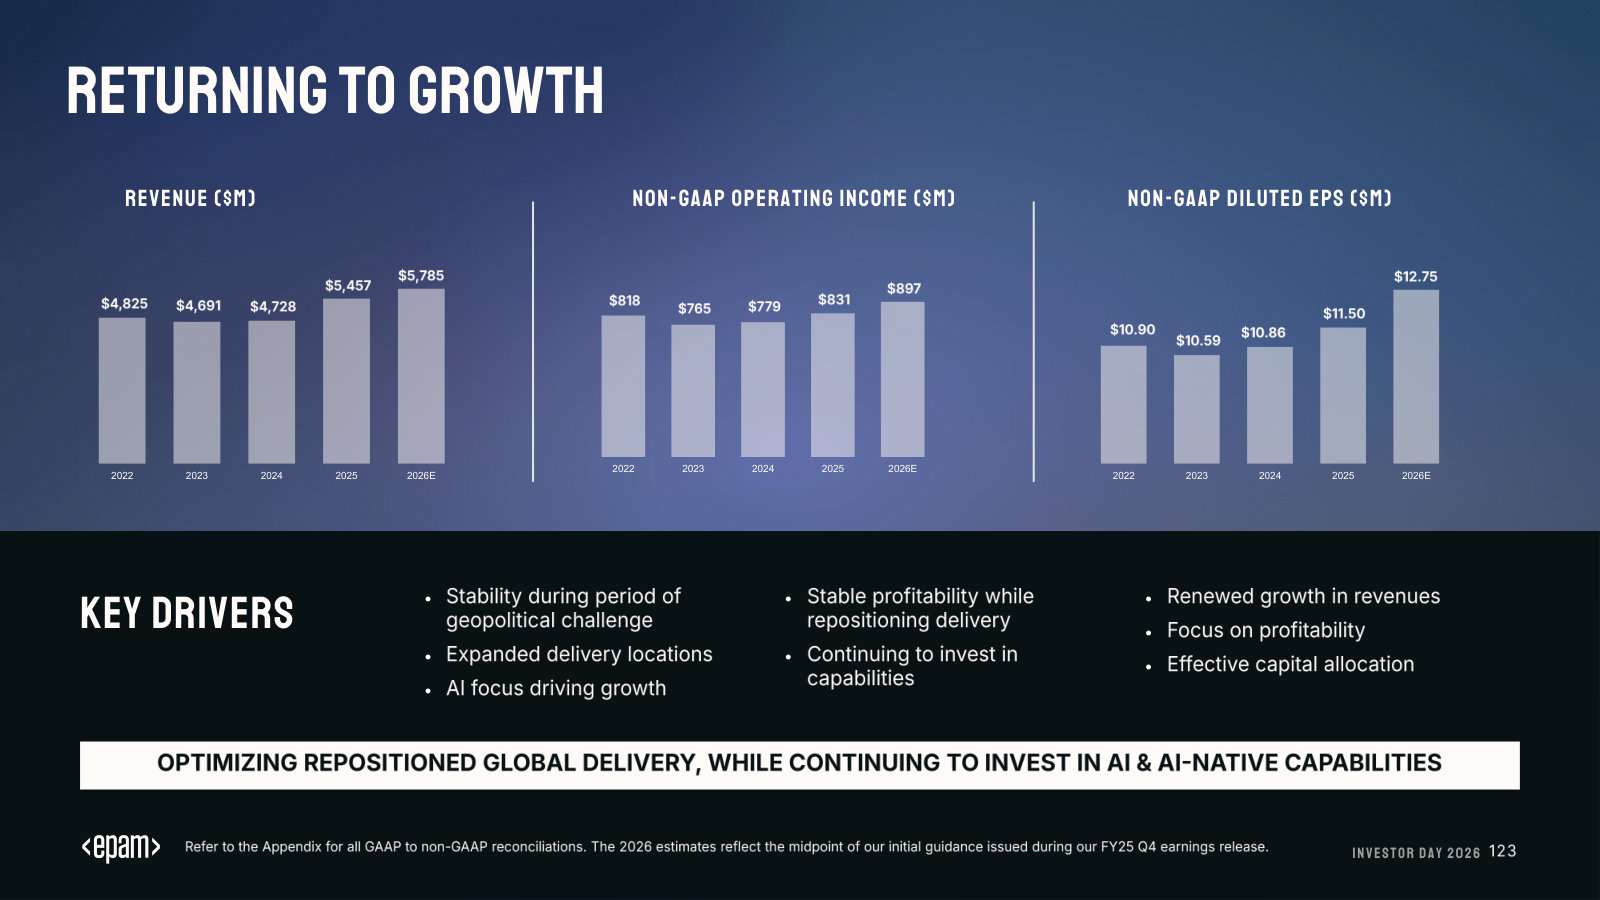
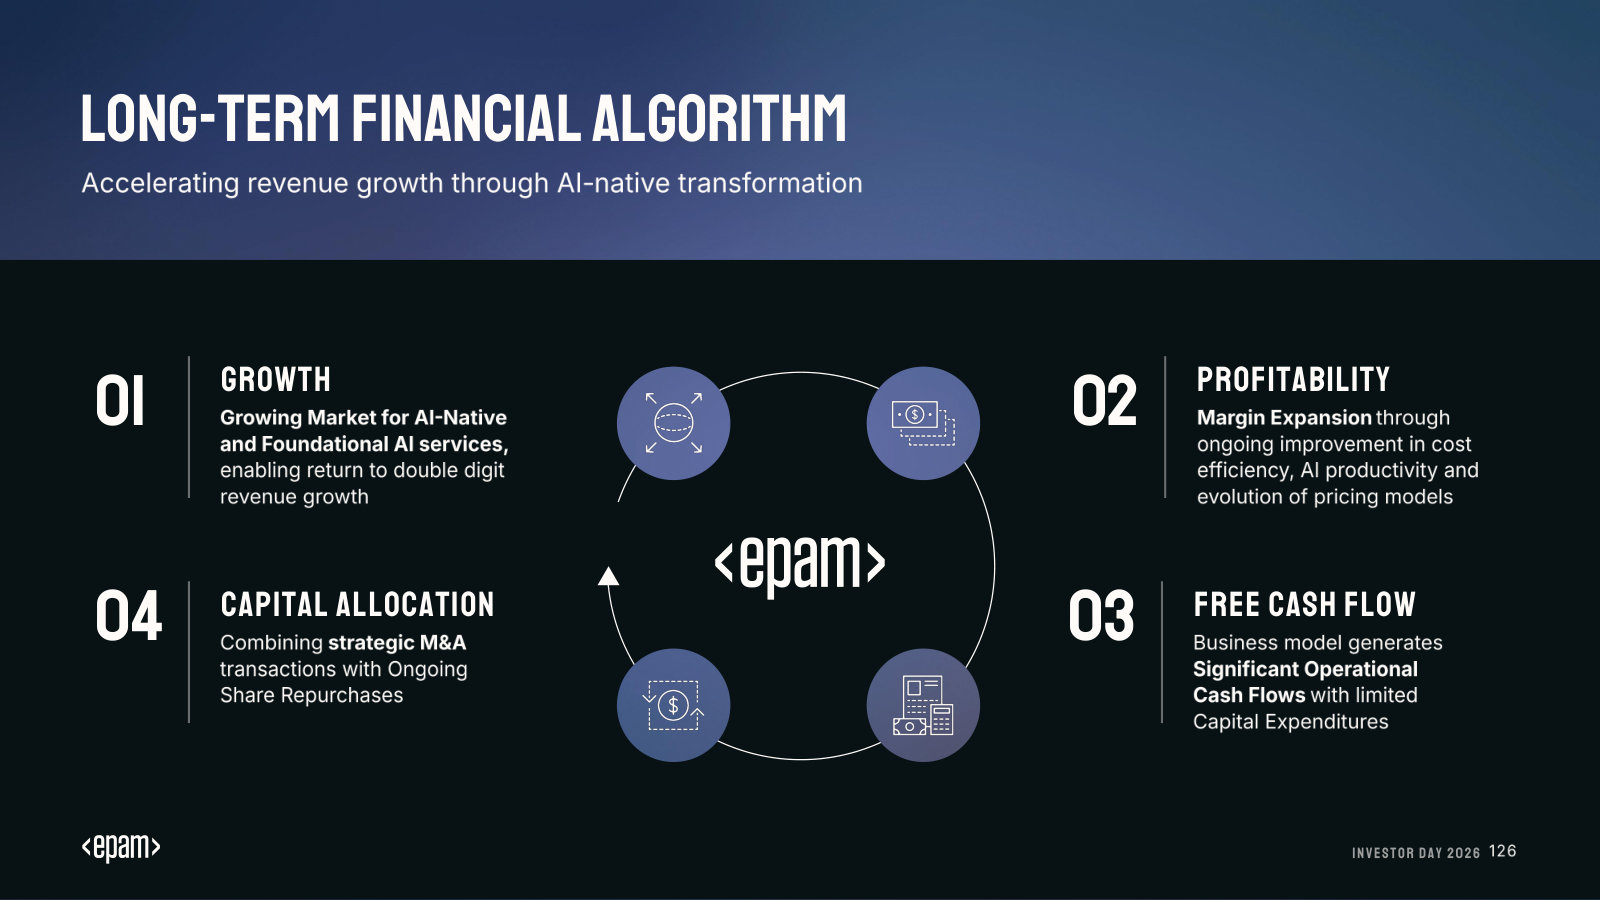
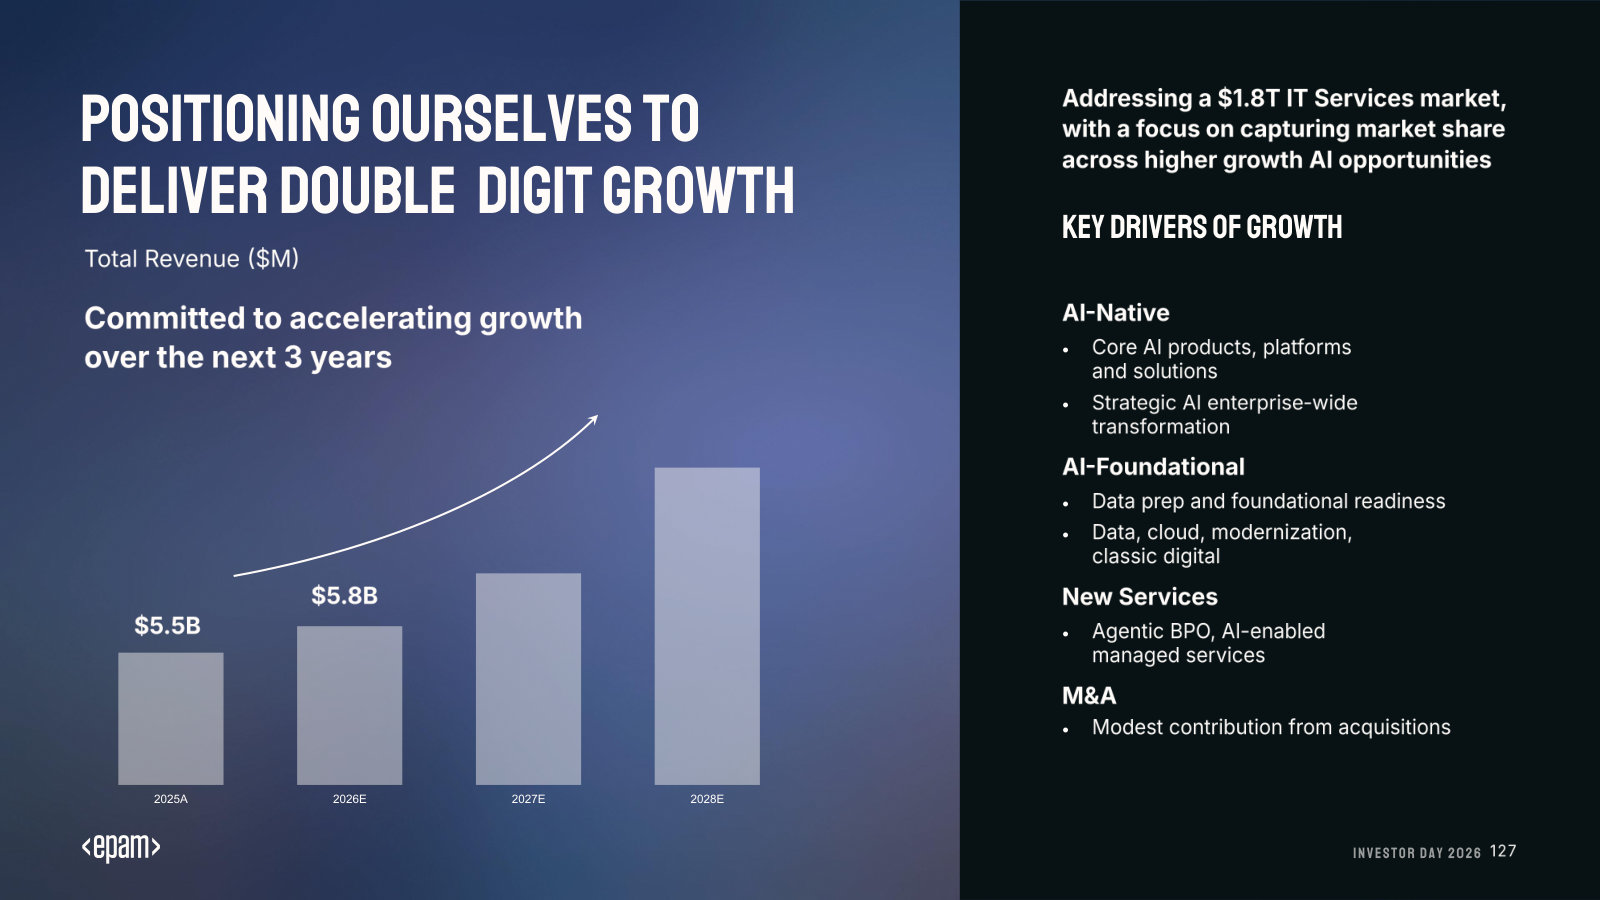
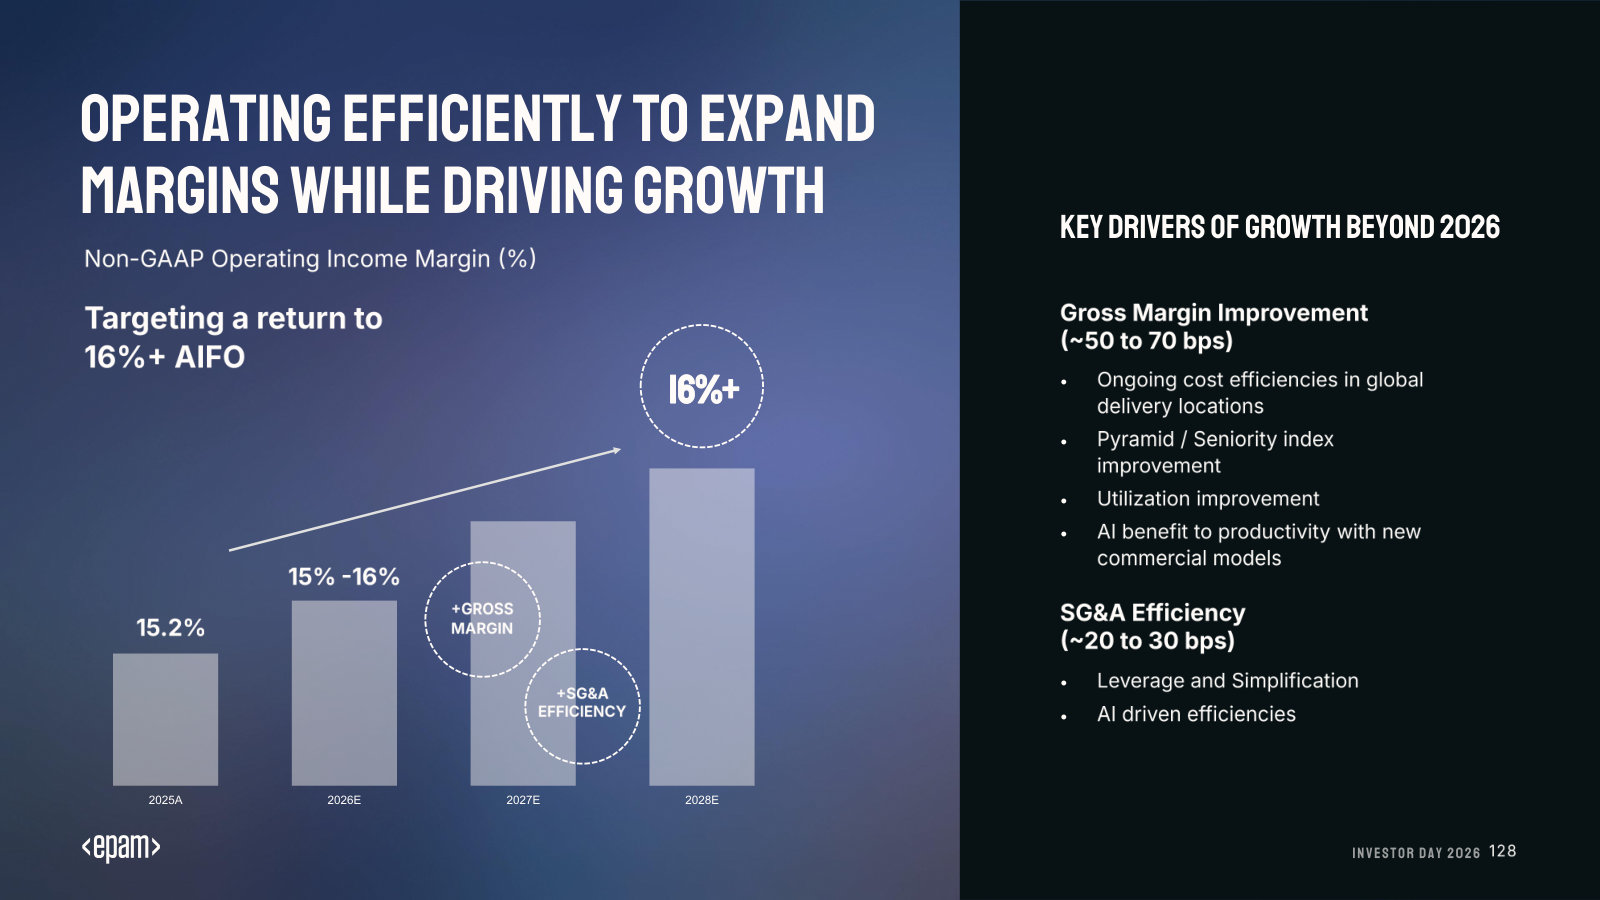
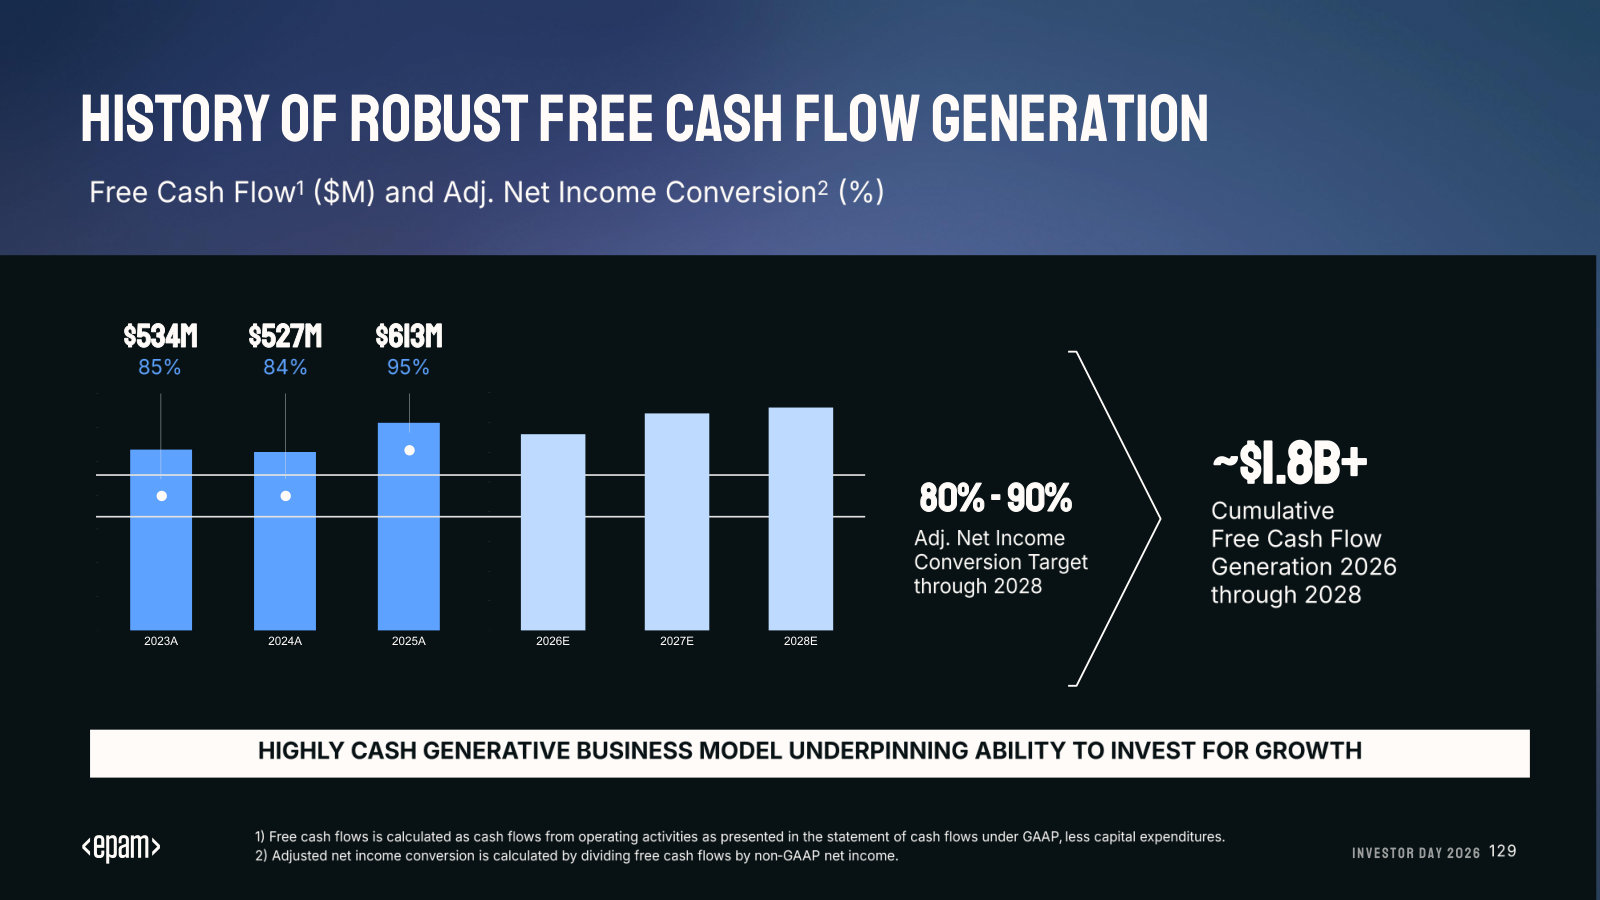
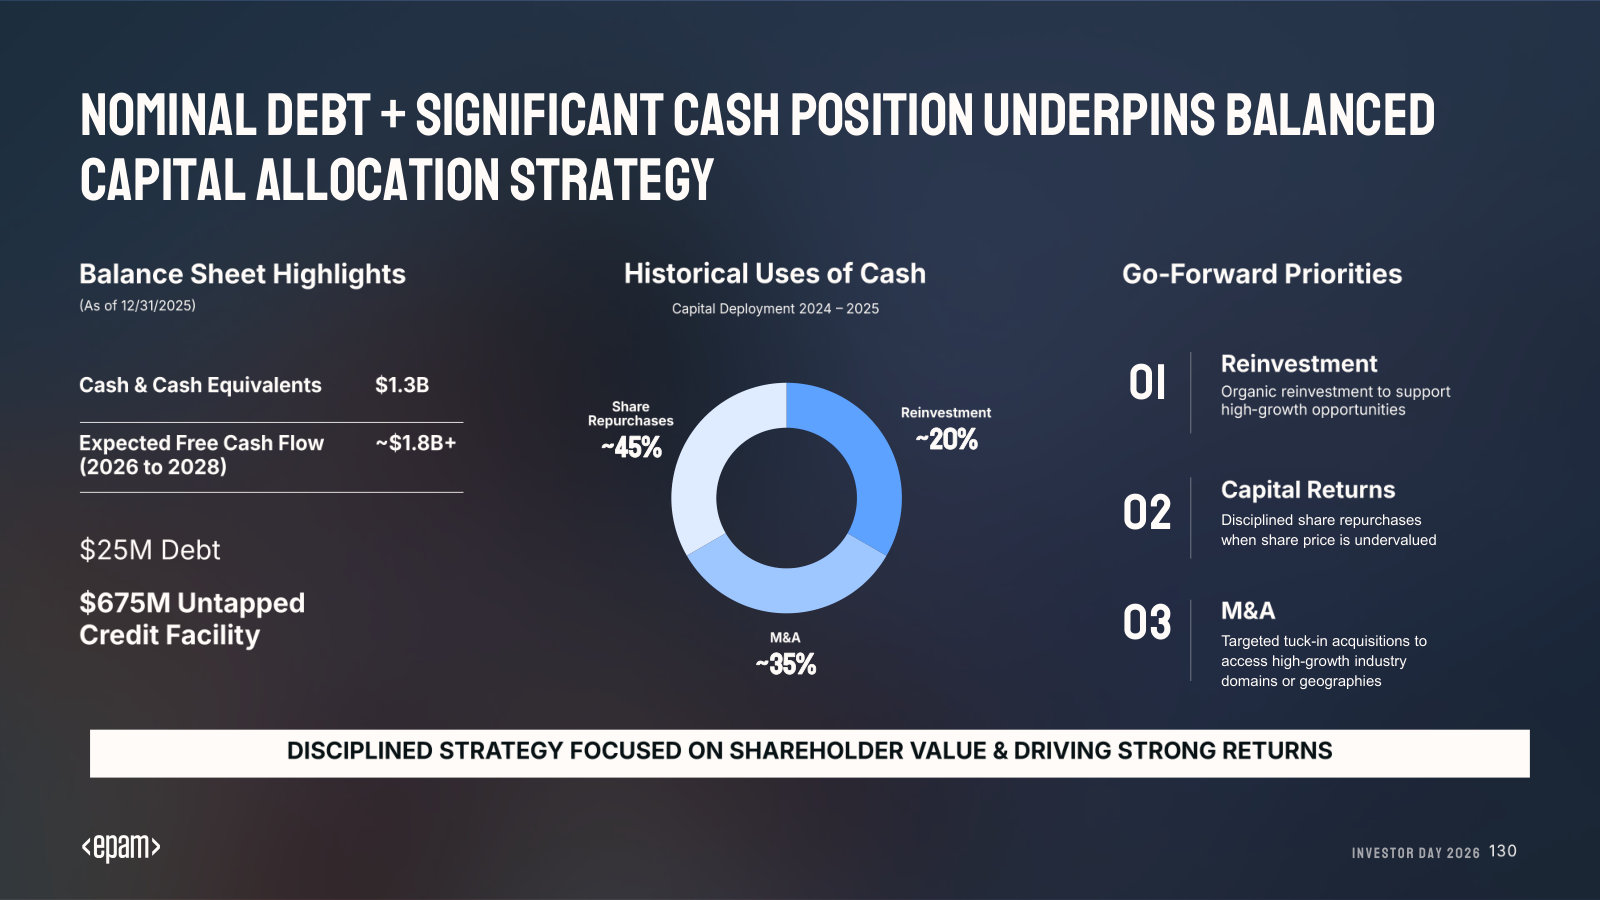
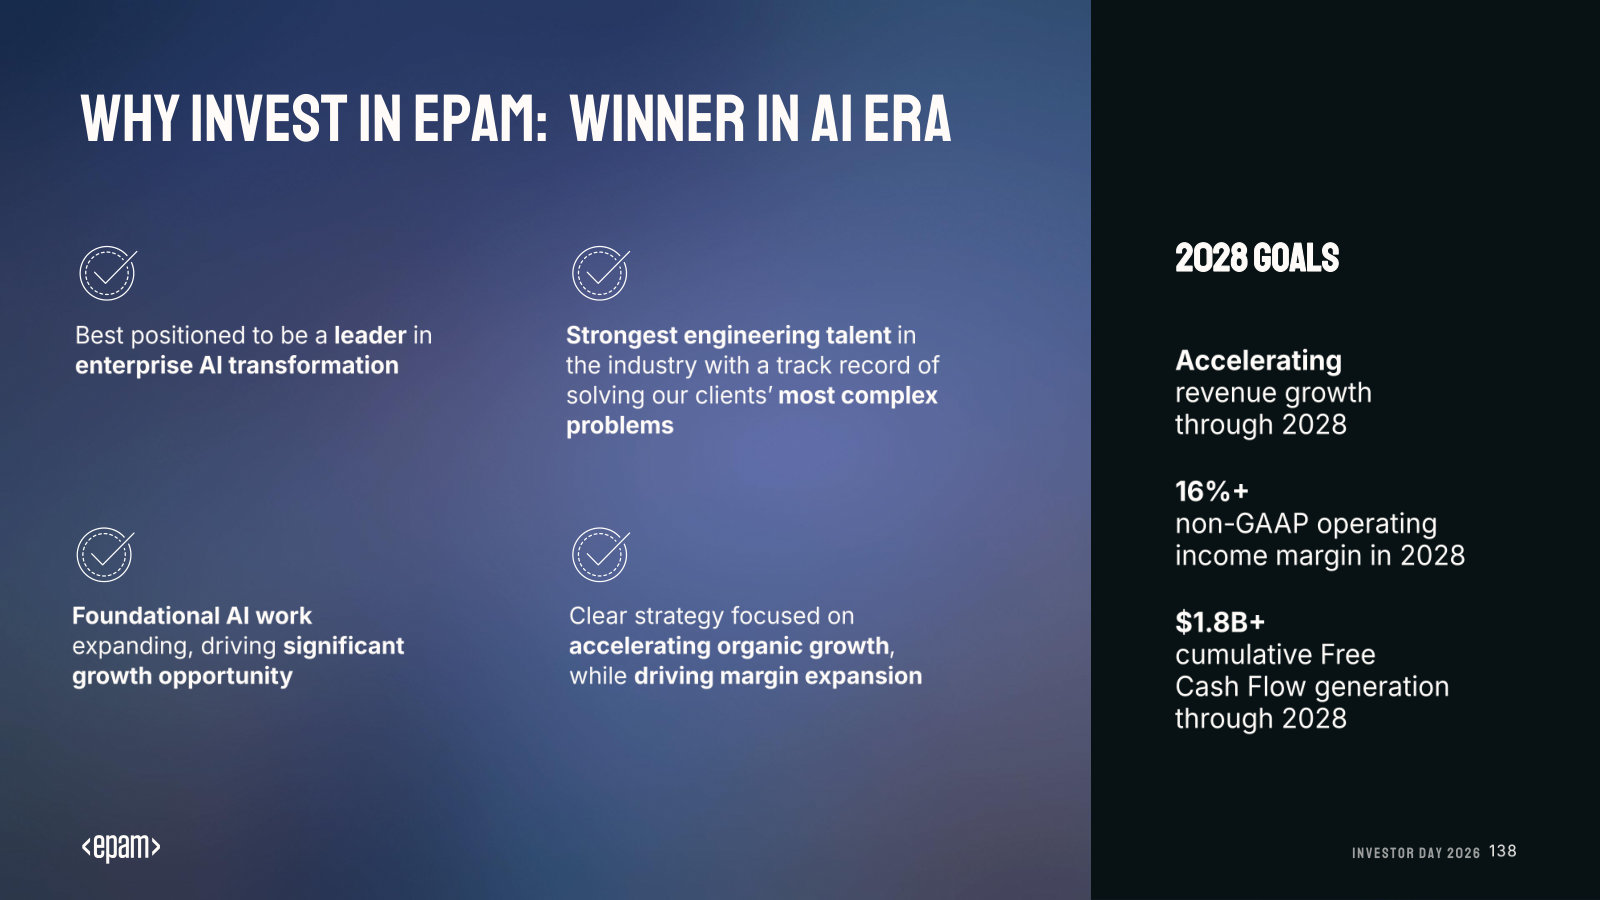
EPAM Systems, Inc.'s management explains the business in its own materials. The slides below do the most of that work, pulled from the documents preserved in Sources. Each source link opens the complete presentation at that slide in a new tab.
Investor Day 2026 — 2026
Management's fullest current statement of strategy, market opportunity, delivery model and 2028 financial targets. · Open the full document →
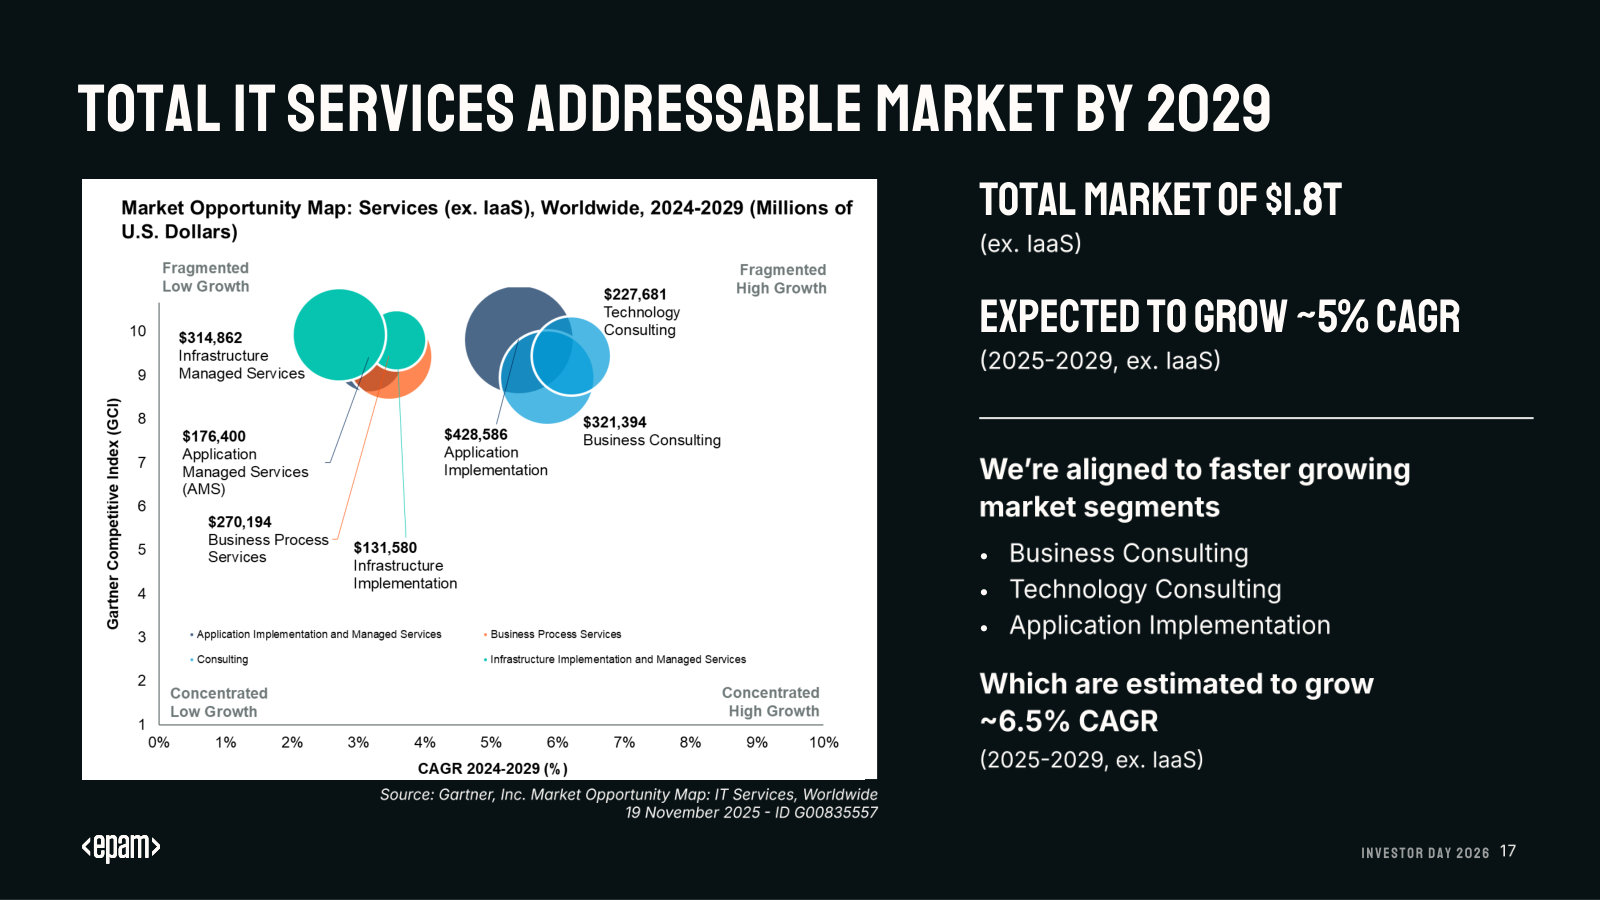
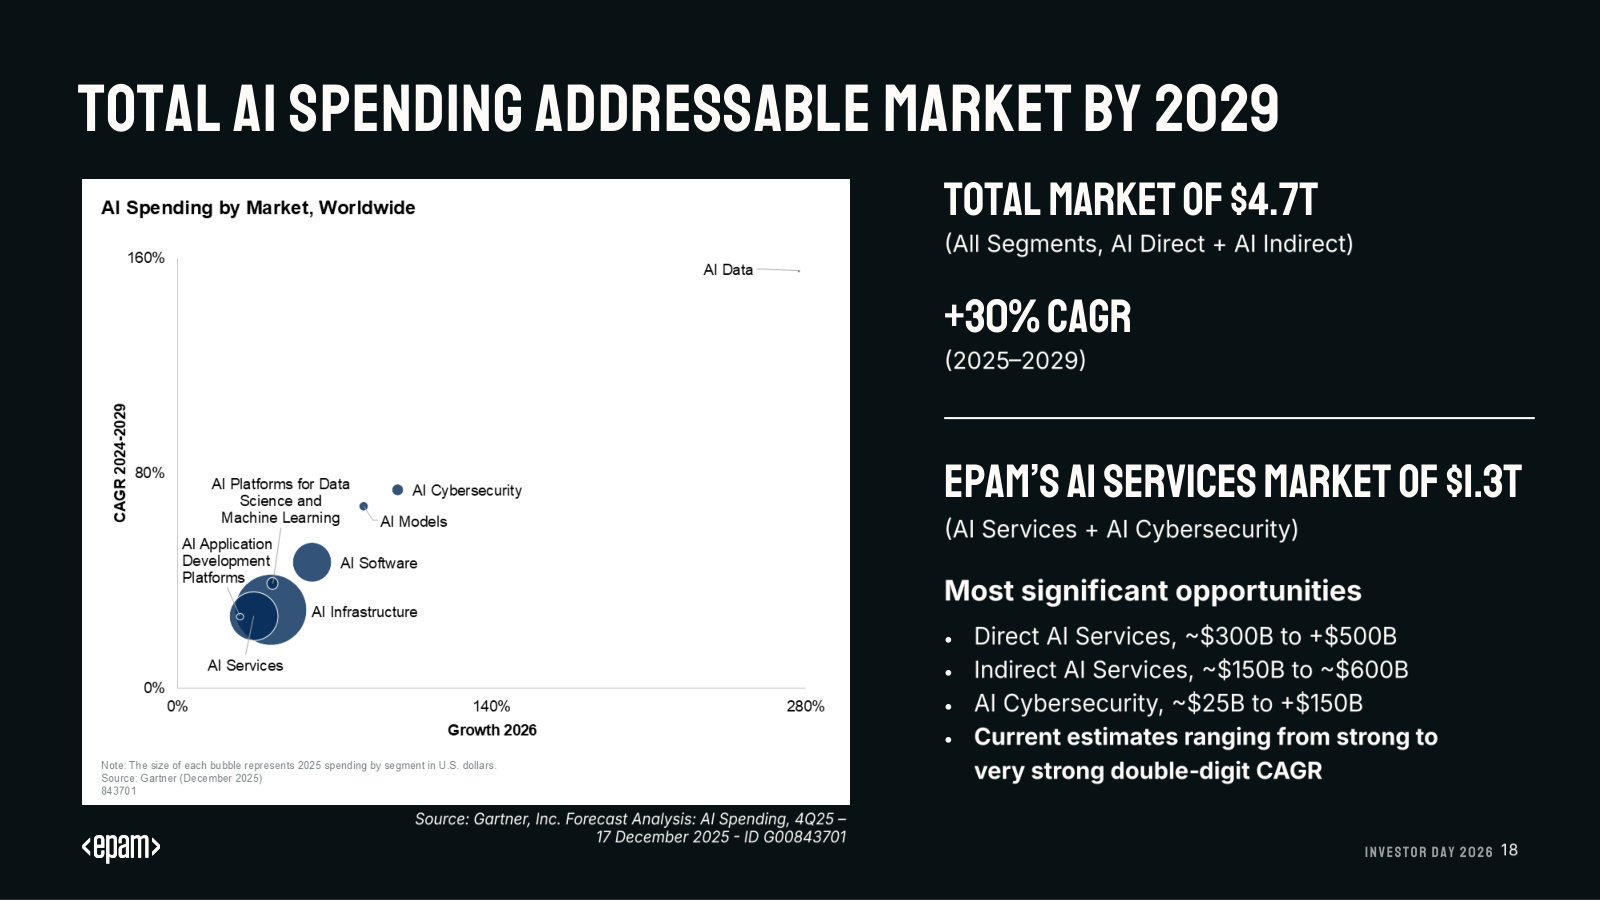
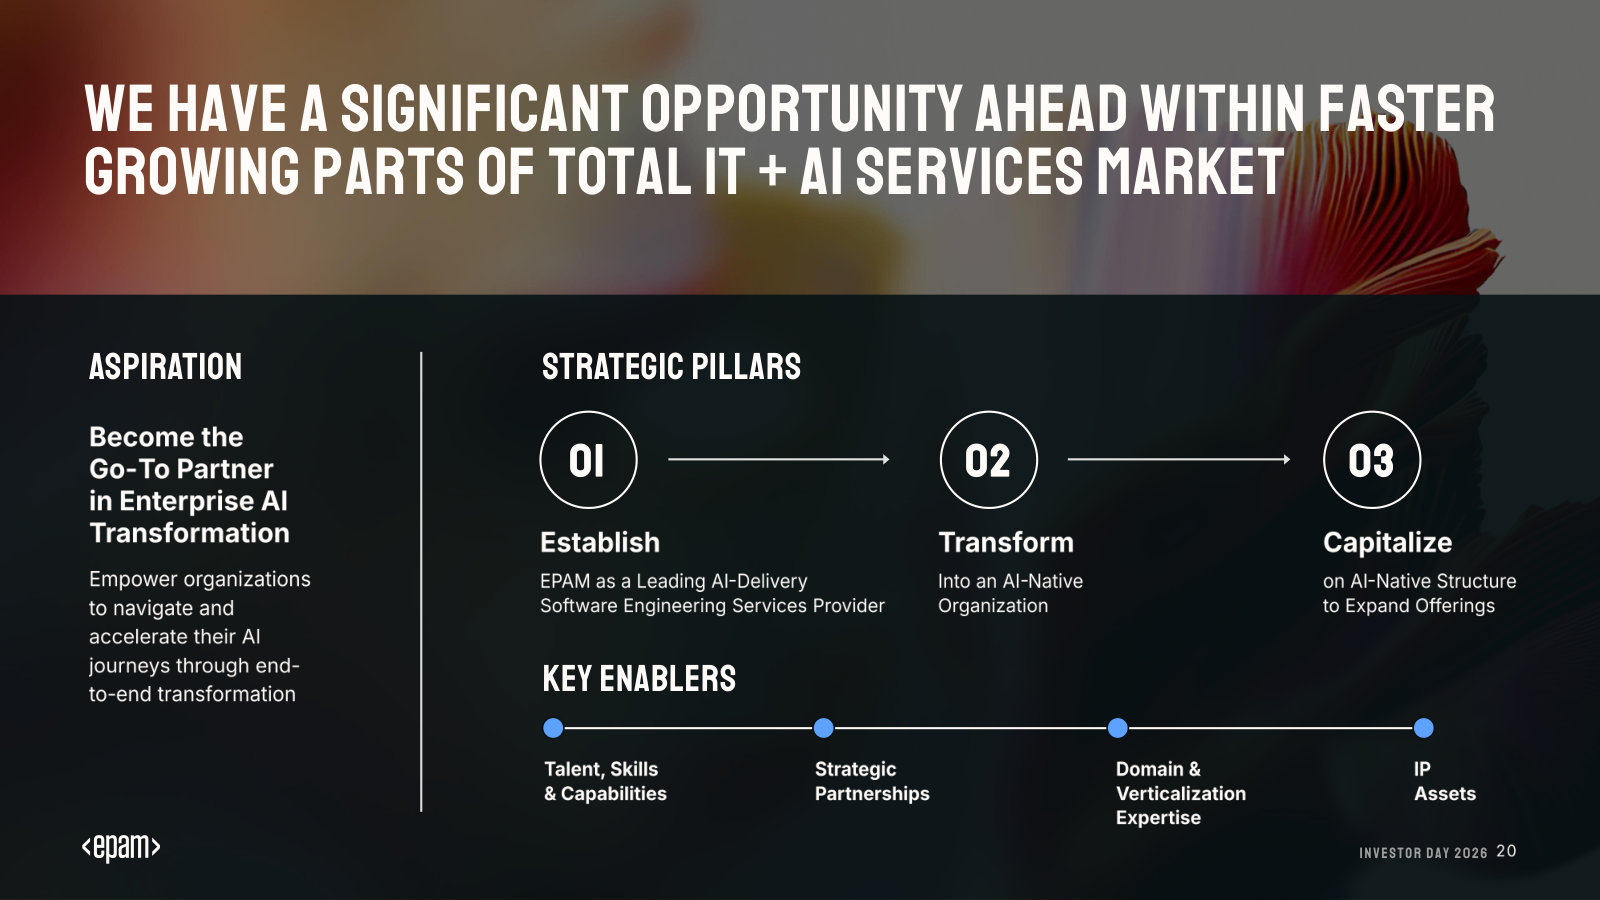
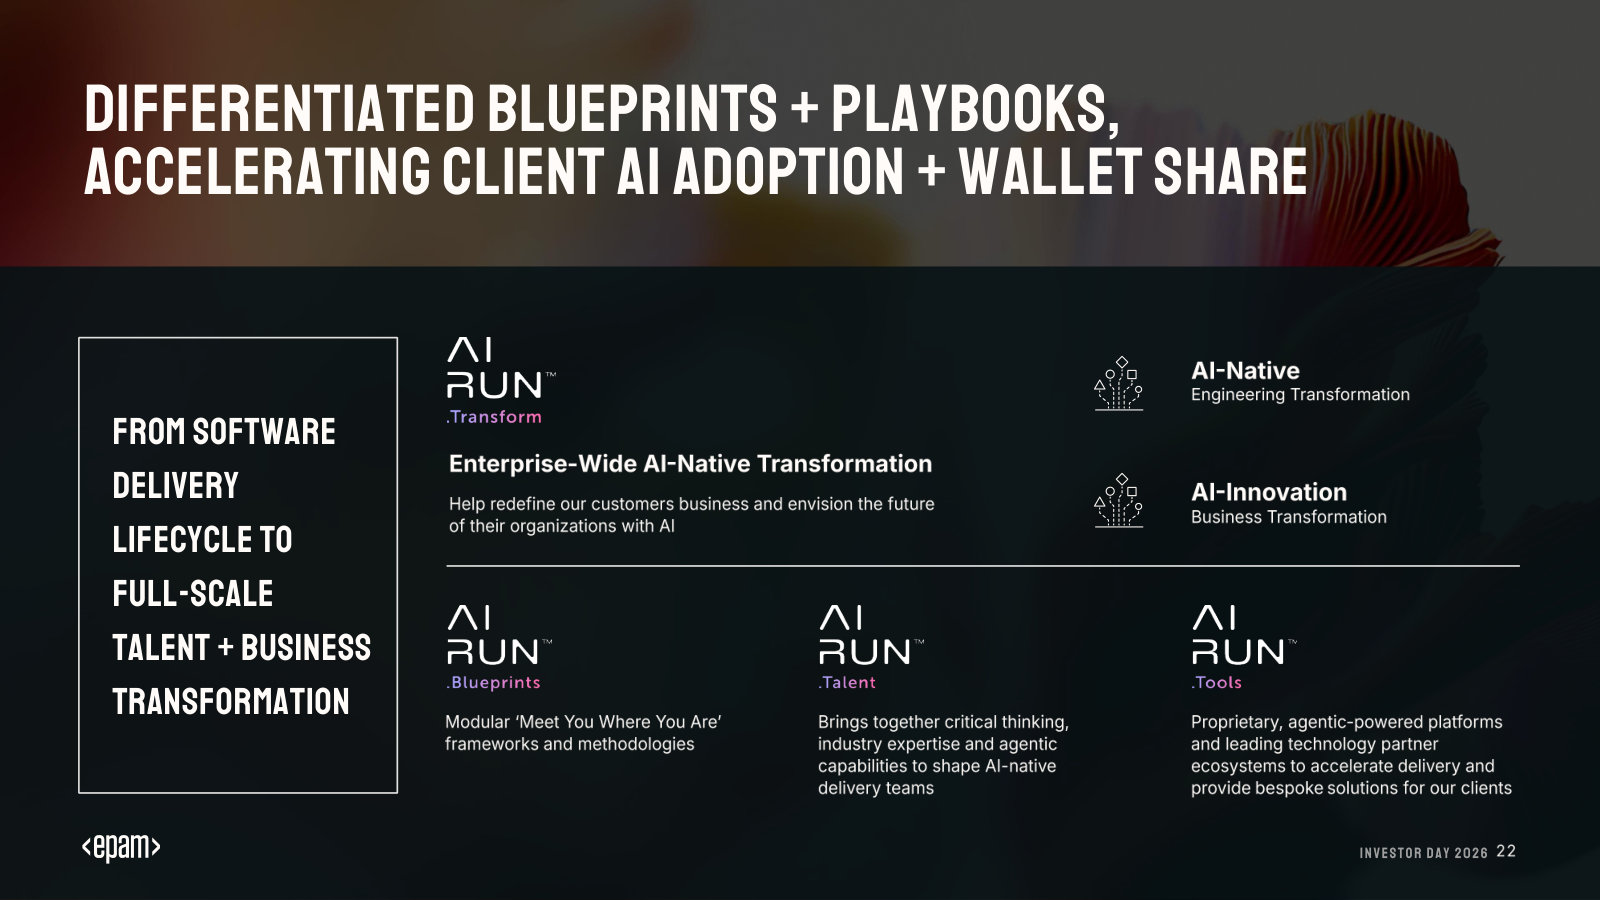
Investor Presentation — May 2026 — Q1 2026
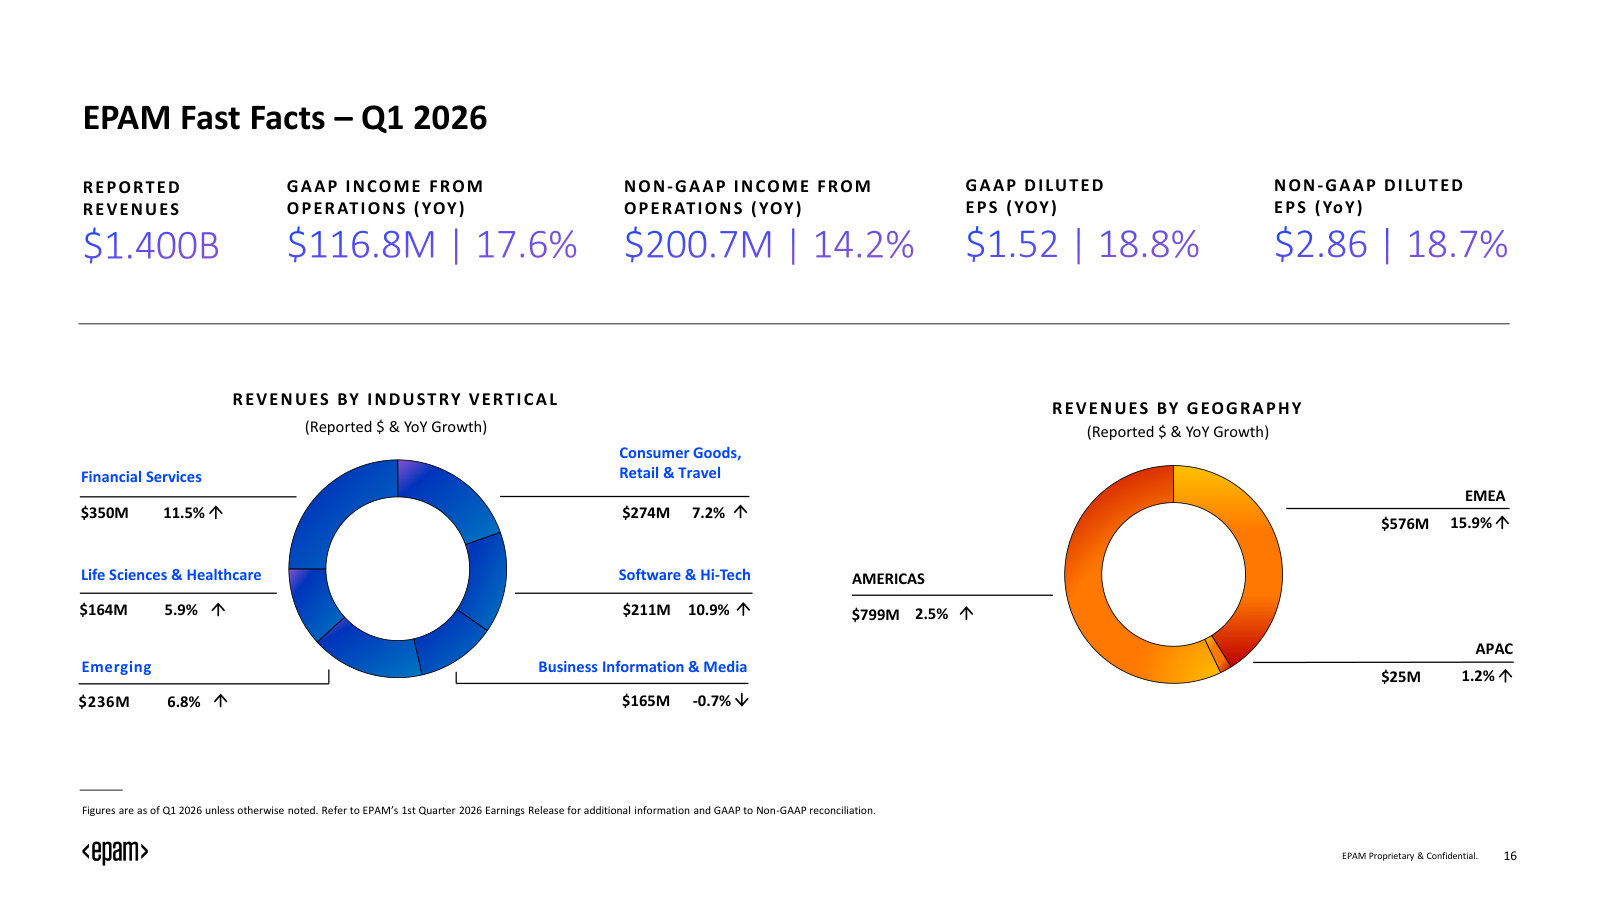
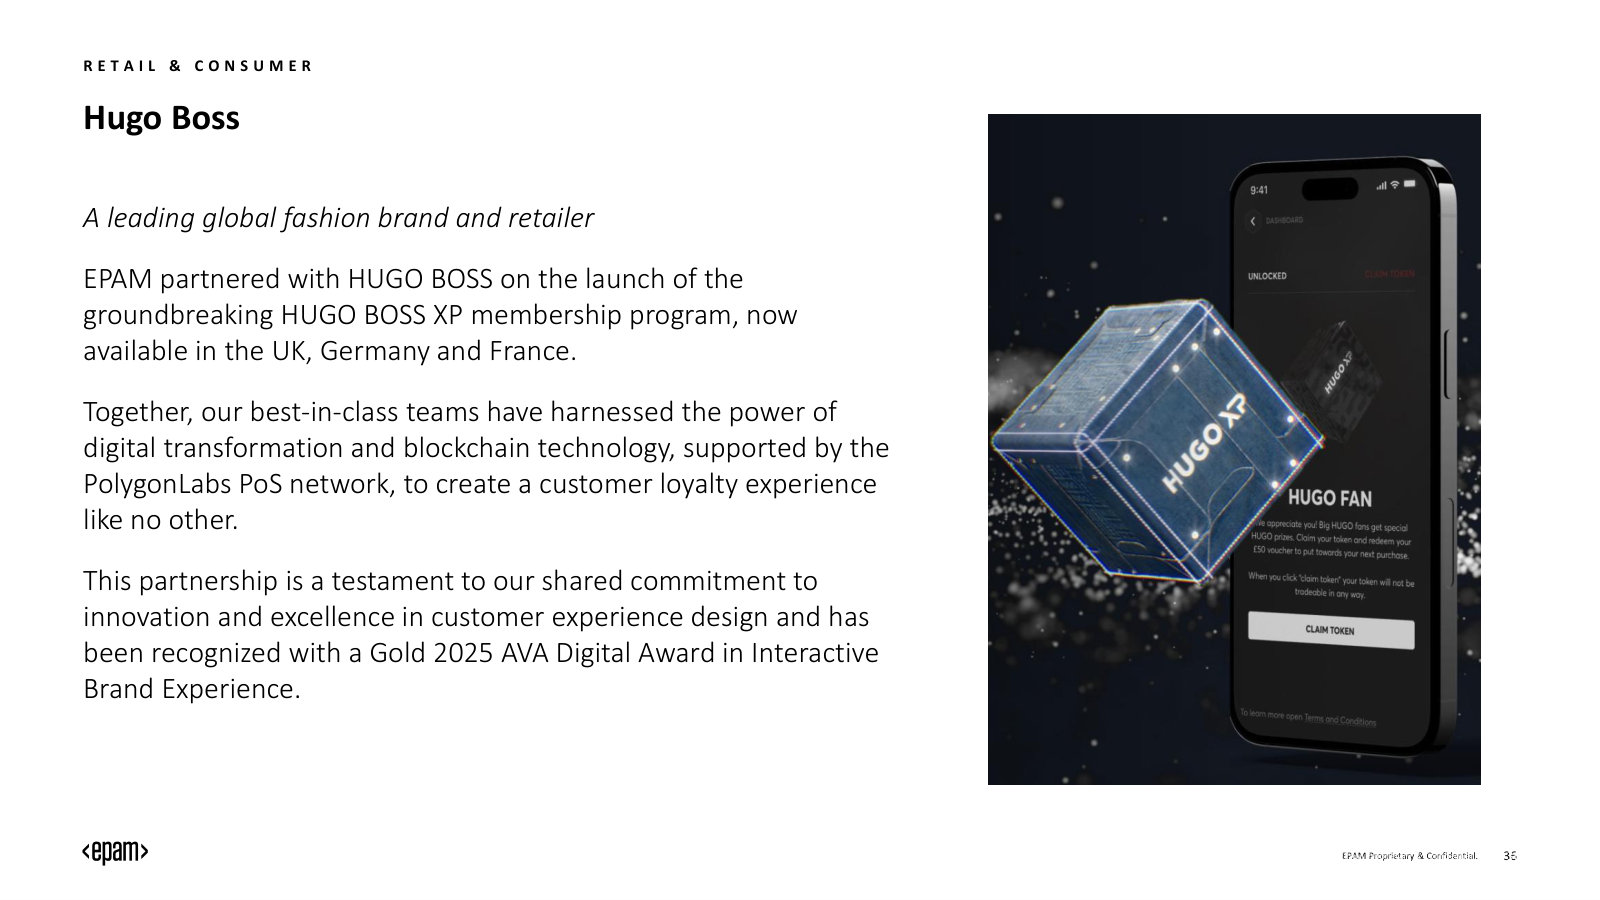
A concise, current company overview with the latest quarter's results and concrete client case studies. · Open the full document →
EPAM Systems, Inc.'s management answers for the business every quarter. These are the exchanges that explain it best — verbatim, from the call transcripts preserved in Sources. Each link opens the full transcript at that page in a new tab.
Q1 FY2026 Earnings Call — Q1 FY2026
The most recent call and new CEO Balazs Fejes's clearest strategy statement: the AI-native pivot, token economics, a pipeline of outsized 'vendor consolidation' deals, and how the guide is built. · Open the full transcript →
Guidance philosophy: the low end assumes worsening delays, the high end big-deal wins — but the midpoint needs neither.
David Grossman (Stifel); Jason Peterson, CFO: On the lower end of the range, you could see further worsening or more clients delaying decisions, which would mean incremental uncertainty and delays. On the higher end, you'd have solid execution in the traditional book plus a higher share of wins in the larger deals Balazs referenced […] For the midpoint, we do not need to win many of those large deals. The midpoint is driven more by steady execution and typical EPAM conversion of opportunities. If the macro continues to deteriorate further, that would challenge the midpoint, but it's not heavily dependent on those outsized deals
p. 8 · Read in context →
The hardest question: can EPAM close and run deals bigger than any before? A new muscle, but AI-native margins run above average.
Jonathan Lee (Guggenheim); Balazs Fejes, CEO: You highlighted large multiyear deals in the pipeline that are larger in scale than what EPAM has historically pursued. What gives you confidence in your ability to close and execute on those? Do you have the sales muscle, governance frameworks and delivery infrastructure to manage programs of that magnitude? How should we think about the profile of these deals regarding competitive dynamics, deal size and margin profiles relative to what you currently see […] We were somewhat surprised at how successful our offering resonated and how quickly the pipeline built. We have the sales muscle to get into these opportunities, and our offering is differentiated because it brings AI-native capabilities that challenge the status quo. We are risk-adjusting the pipeline; we're not assuming full conversion or immediate ramp. EPAM has experience running large programs historically, though those were typically aggregates of many smaller engagements rather than single outsized deals. In terms of profitability, our current AI-native portfolio, which is over $125 million per quarter, runs at higher profitability than the EPAM average
p. 9 · Read in context →
AI unit economics today: clients bear the token cost, EPAM is exploring when to charge — and there is no broad rate compression.
Bryan Keane (Citi); Balazs Fejes, CEO: Pricing dynamics are a moving target and token economics continues to be an area of discussion. Today, in most client relationships clients are bearing the cost of tokens. We're exploring different commercial models, including when EPAM might charge for tokens, when clients pay directly, and how to structure security and compliance concerns. Anthropic is not fundamentally different in construct — we'll develop software using the Anthropic stack and explore appropriate commercial models with clients and Anthropic. Regarding pricing, Jason and I were pleased to see rate increases in Q1; we are not seeing broad rate compression at this time and have been successful negotiating rate increases with a minority of clients
p. 10 · Read in context →
How AI margins get controlled: EPAM must build “trading-desk-like” model-sourcing to manage cost, availability and pricing.
James Faucette (Morgan Stanley); Balazs Fejes, CEO: To control economics you need to control multiple aspects: model usage (which model is used for which task and how frequently), the right blend of models to balance capability and cost, and multi-sourcing capability so you can buy the same model service from multiple providers when appropriate. We need to build trading-desk-like capabilities to manage pricing, availability and consumption limits. If you correctly control sourcing and usage of models, you can achieve differentiation in pricing and profitability
p. 11 · Read in context →
The cannibalization admitted plainly: clients divert budgets toward AI and away from e-commerce builds toward AI-native products.
Arvind Ramnani (Truist); Balazs Fejes, CEO: There is some impact as clients shift IT budgets toward AI spending and automate parts of the SDLC, for example testing. Clients are also diverting investments away from some digital platform or e-commerce builds toward new AI-native products or platforms. That's the shift we are seeing
p. 11 · Read in context →
Q4 & Full-Year 2025 Earnings Call — Q4 FY2025
The annual call: how EPAM monetizes AI through a deliberately narrow 'AI-native' revenue line, why bigger AI programs help demand, where 2026 margin and pricing come from, and the buyback-plus-tuck-in capital plan. · Open the full transcript →
Defines the deliberately narrow AI-native revenue line: >$105M in Q4, targeted above $600M in 2026, excluding all AI-assisted delivery.
Balazs Fejes, CEO: Notably, in Q4, we generated more than $105,000,000 in pure AI-native revenues, where we continue to see solid momentum and strong sequential growth. As a reminder, our AI-native revenues are defined across two groupings: number one, AI-native IP products, platforms, and solutions where AI was the core of the solution versus simple work accelerated by the use of AI tools; and number two, AI-led transformation initiatives across the entire enterprise. Importantly, our definition excludes all the AI foundational services along with any AIassisted work performed by EPAM Systems, Inc. employees within the software delivery lifecycle. Looking ahead, we continue to see robust demand for our AI-native services and expect to scale these revenues in excess of $600,000,000 in 2026
p. 2 · Read in context →
The bull thesis: AI multiplies complexity faster than it cuts cost, putting EPAM in the build-vs-buy sweet spot — “the age of building.”
Balazs Fejes, CEO: While we are seeing measurable productivity gains at scale, we are also seeing complexity dramatically increase at a faster pace than we have seen in prior cycles. Clients are facing growing pressure to continue to invest in AI, and that means platform modernization, data, and cloud foundations, security, and critical AI-native upskilling. As a result, AI presents a favorable opportunity for EPAM Systems, Inc. within the build versus buy volume proposition. EPAM Systems, Inc. continues to be positioned in this sweet spot as we believe we are entering an age of building
p. 1 · Read in context →
Hardest question — “when does the dam break” on delayed AI spend; no crystal ball, but financial-services spend is turning nondiscretionary.
David Grossman (Stifel); Balazs Fejes, CEO: When does that dam have to break? At some point, when does the spending have to accelerate despite uncertainty? […] I wish I would have a crystal ball for that, but I think we are seeing more and more larger programs, which makes me optimistic that we are getting close to that point. So I think right now there are clearly, in certain industries—financial services, for example, in Europe— people are no longer able to hold back transformation and the nondiscretionary CapEx expenditure. Plus, in certain other industries, we are already seeing people are no longer able to delay their decision-making around AI investments, and that is triggering larger programs
p. 10 · Read in context →
Capital allocation: near-term buybacks plus small tuck-in M&A, with scaled M&A only after digesting the prior deals.
Jim Schneider (Goldman Sachs); Balazs Fejes, CEO; Jason Peterson, CFO: I think we continue to focus on the share buybacks, which as Jason also already communicated, we announced the share buyback plan earlier, the previous quarter. And in the next couple of quarters, at least definitely in the first half year, we are going to continue to make acquisitions as appropriate and repurchase shares. And especially, what we really want to execute is small tokens. But that is our plans at this point of time […] Yeah. So, Jim, in the near term, you probably still have a focus on share repurchase, and then over time, I think we would be more open to kind of scaled M&A activity
p. 12 · Read in context →
Q1 FY2025 Earnings Call — Q1 FY2025
The succession call: founder Arkadiy Dobkin hands the CEO role to 20-year insider Balazs Fejes, while acquisitions carry the top line and compress margins. · Open the full transcript →
The founder hands off: after 32 years Dobkin moves to Executive Chairman and names 20-year insider Balazs Fejes CEO, effective 9/1/25.
Arkadiy Dobkin, CEO & President: After 32 years since starting in EPAM serving as the Chairman, CEO, and President, I decided to transition into the role of Executive Chairman. This move has been thoughtfully planned over the past several years, and I believe that the right moment is now both for me personally and for the future of the company. But I'm not leaving EPAM as Executive Chairman; I plan to continue providing strategic guidance, combining my years of experience to hold the relationships and Board leadership, and ensuring that the CEO transition is smooth and effective, and that EPAM continues advancing our mission, culture, and values […] I am pleased to announce today that Balazs Fejes will become our new Chief Executive Officer and President on September 1, 2025. Balazs, better known as FB, joined the company over 20 years ago and has been a critical part of our growth story. His leadership has been instrumental to EPAM's development, serving as our first CTO, building our financial services business globally, leading our European and APAC markets, and most recently serving as the President of Global Business and Chief Revenue Officer. FB is uniquely positioned to provide both strategic and operational leadership during our next phase of revolution. I am confident that his rare combination of business and technical acumen will enable him to continue driving EPAM forward
p. 1 · Read in context →
How the top line is built: 11.7% reported vs 1.4% organic constant-currency growth shows acquisitions carrying the quarter.
Jason Peterson, CFO: In the first quarter, EPAM generated revenue of $1.3 billion, a year-over-year increase of 11.7% on a reported basis. On an organic constant currency basis, revenue grew 1.4% compared to the first quarter of 2024, exceeding our expectations of flat organic growth anticipated at the midpoint of our Q1 guidance. We are pleased to deliver another quarter of year-over-year organic growth in constant currency, reflecting ongoing demand for EPAM services and strong execution across our global portfolio of clients. As Ark mentioned, we believe the outperformance is in part driven by client recognition of EPAM's superior delivery quality and momentum across our AI offerings. Moving to our Q1 vertical performance, four out of six industry verticals delivered strong to ver strong revenue growth. Revenues from our FD and NEORIS acquisitions had the most impact on our financial services and emerging verticals, so I will break out the organic and inorganic contribution within these two verticals. Financial services delivered very strong growth of 29.3% year-over-year, reflecting 4.5% organic growth in constant currency driven by continued strength in insurance, banking, and payments
p. 4 · Read in context →
The margin tension quantified: gross margin fell to 28.7% from 30.4% as comp hikes and dilutive acquisitions outweighed utilization gains.
Jason Peterson, CFO: Non-GAAP gross margin for the quarter was 28.7% compared to 30.4% for the same quarter last year. Relative to Q1 2024, gross margin in Q1 2025 was negatively impacted by 2024 compensation increases which were only partially offset through pricing. Additionally, lower profitability from recent acquisitions negatively impacted gross margin. The negative impacts from compensation and lower profitability from acquisitions exceeded the benefits of improved utilization and the positive impact from the Polish R&D incentive. The company will be focused on improving gross margin throughout the remainder of the year
p. 4 · Read in context →
Hardest question — quantify second-half backlog coverage; management declines, admitting decisions are made “in real-time.”
Jim Schneider (Goldman Sachs); Arkadiy Dobkin, CEO: any way of sort of quantifying your second half backlog coverage perhaps being better, worse, or the same as in a typical time after Q1? […] If we're talking about the second half of the year, I can only repeat what we've said already. So with all kind of better environment visibility still relatively difficult, and what we're seeing for the second part of the year is approximately what we were seeing a quarter ago. So decisions are still being made more in real-time. That's what we benefited in Q1 and Q2, so predicting Q3, Q4 better than we predicted so far is difficult, including the size of the deals as well
p. 10 · Read in context →
Q4 & Full-Year 2023 Earnings Call — Q4 FY2023
The post-war annual: India set to become EPAM's largest delivery location, the downturn pricing and margin math, and the first serious framing of GenAI as both a pull-through and a commoditizer. · Open the full transcript →
The post-war delivery shift made concrete: India, the fastest-growing location since 2021, set to become EPAM's largest by end-2024.
Arkadiy Dobkin, President & CEO: We work on scaling India and LatAm, and at the same time, preparing for future growth in development centers across Europe and Western and Central Asia, our key destination for majority of our relocated talents. In 2023, India continued to be our fastest-growing location, practically since 2021. And while we were growing our capabilities there with accelerated speed, we also worked to ensure that our delivery culture remains focused on quality and client value. India will likely become our largest location by the end of 2024 or at least on match with our current scale in Ukraine
p. 4 · Read in context →
The downturn margin math: winning work needs some discounting while comp rises and pricing stays weak — margin pressure guided into 2024.
Jason Peterson, CFO: We have been pleased with the progress we are making on demand generation, and we'll continue to prioritize revenue growth into 2024, which, in some pursuits, include some degree of discounting. In 2024, we expect to incur incremental costs due to more normalized variable compensation levels, in addition to wage inflation in certain geographies. This higher level of compensation, combined with the limited ability to improve client pricing in the near term, will continue to put pressures on margins in 2024
p. 13 · Read in context →
GenAI as opportunity: small proof-of-concepts are proving out and pulling through a “tail” of larger data-engineering work.
Arkadiy Dobkin, President & CEO: As everybody say, it's still a lot of experimentation, but we highlighted something which we do. And there is a quest to implementations happening as we speak. Still the program is not very sizable, but what we also see is that a lot of proof of concepts actually proven to the point that it will trigger additional tail of data engineering programs a lot, because while experimentation going well and proof of concept looking good, usually the data for this type of activities is by size well enough
p. 17 · Read in context →
GenAI as threat: today's exciting capabilities “become very quickly commodity,” resetting the landscape roughly every 12 months.
Sean Kennedy (Mizuho); Arkadiy Dobkin, President & CEO: So I think, still there are, at this point, a lot of experimentation and a lot of kind of more straightforward thinking about GenAI, as it's available practically for the end consumers and how this can change interfaces. And again, very straightforward that everybody is thinking how to have a right access to the hybrid data between general sales, the specific ones and most of the companies experimenting in this area and created some type of copilots. And I'm talking about application of areas and just utilizing GenAI as a activity tools for individuals and we work as a sort. I'm talking about, like, client-facing capabilities, new insight. The dificulties of this is it will be changing quarter by quarter. And, I think some exciting things which we see right now would become very quickly commodity and much more sophisticated since it'll be happening like 12 months from now
p. 31 · Read in context →
Hardest question — if demand is recovering, why so little first-half growth? The new logos are smaller engagements amid intense competition.
Darrin Peller (Wolfe Research); Arkadiy Dobkin, President & CEO: So I think when we're talking about increasing the client number, it's true the difference with previous year that this is smaller clients, smaller — clients maybe not smaller, but smaller engagements. And overall, it still feel a lot of pressure from all, more competitiveness. And it's all coming back to our statement that we actually adjusted our behavior during the 2023, OK, and started to use different approaches to kind of protect client base as well. But it was much more visible all the transition between first half and second half of 2023
p. 29 · Read in context →
Q1 FY2022 Earnings Call — Q1 FY2022
The stress-test call, the first after Russia's invasion of Ukraine: a delivery-concentrated model tested in real time — relocation, the Russia exit, withdrawn guidance, and the plan to diversify the footprint. · Open the full transcript →
Phase 1 was survival: management calls stabilization a success and confirms the April decision to exit Russia.
Arkadiy Dobkin, CEO & President: Those efforts we define for ourselves as a Phase 1, a period of safety and stabilization of our operations, with very little attention to anything beyond that. Under the current conditions, we believe this phase is largely completed and we will call it out as a notable success. Jason will illustrate in more details the specific numbers for our Q1 results and our guidance for Q2 shortly. So while we are managing through the humanitarian crisis in Ukraine, we're also working with our customers to address their concerns and request to reposition projects and teams to different geographies, which is very much guided by the business continuity plans we had previously established with our clients, including multiple relocation alternatives for our employees. In April, we also made the decision to exit our operations in Russia
p. 5 · Read in context →
The concentration and the plan: talent in Ukraine, Belarus and Russia falls from ~70% pre-COVID toward ~30% of production by end-2022.
Arkadiy Dobkin, CEO & President: I would also point out that in large part, this diversification program was well underway even during the past several years. Before COVID, our allocation to the talent from Ukraine, Belarus and Russia was close to 70% of our total production capacity. By the end of 2021, it was less than 60%. And we believe, by the end of 2022, we will manage to reduce the allocation of our production staff in the region to about 30%
p. 6 · Read in context →
The new footprint, named: relocated staff land in Poland, Central Asia, Turkey and Serbia, with some routed onward to the US.
Arvind Ramnani (Piper Sandler); Arkadiy Dobkin, CEO & President: And if I start to list all countries where people might be right now, it would probably be by the end of this call. But there are several specific areas. Poland, obviously, was one of the key destinations, but it's not only Poland. It's countries in Central Asia, it's countries in – countries like Turkey and Serbia. So it's all known names. But at the same time, it's not even one-phase exercise because in some situation we have to move people very quickly. And then after this, finding the final destination, which could be U.S
p. 20 · Read in context →
The hardest question: can EPAM build delivery outside Ukraine/Belarus? India and LatAm are offered as proof the greenfield playbook works.
David Grossman (Stifel); Arkadiy Dobkin, CEO & President: So India last year was the fastest-growing location for us, but it wasn't fastest-growing location for us for the first three years, it was practically flat or even going down. So we changed operations while we still have the same management which we acquired a long time ago. So we have support of this team to transition this to a very different company today. And that's why India, probably by the end of the year, would be probably No. 2, No. 3 location for us. Very similar happening in Latin America
p. 26 · Read in context →
More calls
Q3 FY2025 Earnings Call — Q3 FY2025 · 10 pages · The first full quarter under new CEO Balazs Fejes: how AI-native revenue is scaling and how the demand recovery is progressing. · Open →
Q2 FY2025 Earnings Call — Q2 FY2025 · 13 pages · The mid-2025 read during the CEO handoff: NEORIS/tariff-driven demand softness and the return to organic growth. · Open →
Q4 & Full-Year 2024 Earnings Call — Q4 FY2024 · 10 pages · The FY2024 annual: the trough-and-recovery setup, the First Derivative and NEORIS acquisitions, and the 2025 guidance frame. · Open →
Q3 FY2024 Earnings Call — Q3 FY2024 · 5 pages · For the demand trough and the just-closed NEORIS acquisition that reshaped the emerging-markets and financial-services verticals. · Open →
Q1 FY2023 Earnings Call — Q1 FY2023 · 36 pages · Where the 2023 demand slowdown first becomes visible after the war-recovery year, with clients pausing discretionary spend. · Open →
Q4 & Full-Year 2022 Earnings Call — Q4 FY2022 · 36 pages · The full-year war-recovery story: Russia exit complete, the diversified footprint in place, and the cautious 2023 outlook. · Open →
Q2 FY2022 Earnings Call — Q2 FY2022 · 37 pages · The second post-invasion quarter: relocation execution, the ramp of new delivery locations, and the path back toward historical margins. · Open →
Q4 & Full-Year 2021 Earnings Call — Q4 FY2021 · 40 pages · The last pre-war annual: the baseline of the old Ukraine/Belarus/Russia-heavy delivery model before the invasion changed everything. · Open →
EPAM Systems, Inc.'s annual reports contain management's most considered account of the business. These are the sections, passages and visual pages worth opening in the originals preserved in Sources.
EPAM Systems, Inc. — FY2025 Annual Report (Form 10-K) — FY2025
Latest 10-K: management's fullest account of a people-and-delivery business now reshaped by AI, Ukraine and 2024 acquisitions. · Open the full document →
Item 1. Business — p. 5 · Read the full section →
What EPAM sells and where it delivers — the software-engineering core, AI pivot, and a globally dispersed delivery base.
How management frames the business: engineering heritage now sold as AI-native transformation.
EPAM has used its software engineering expertise to become a leading global provider of digital engineering, cloud and artificial intelligence-enabled transformation services, and a leading business and experience consulting partner for global enterprises and ambitious start-ups. […] Through platforms like EPAM AI/RUN™ and initiatives like DIALX Lab™, we integrate advanced AI technologies into tailored business strategies, driving significant industry impact and fostering continuous innovation.
p. 5 · Read in context →
The delivery footprint that is the business: India now largest, Ukraine still ~8,750 professionals.
In 2025, India remained our largest delivery location, measured by the number of delivery professionals, and as of December 31, 2025, we had approximately 12,200 delivery professionals in this location. […] Ukraine continues to be a significant delivery location for us and we had approximately 8,750 delivery professionals there as of December 31, 2025, compared with 8,764 delivery professionals as of December 31, 2024.
p. 9 · Read in context →
Human Capital — p. 11 · Read the full section →
For an IT-services firm, headcount and utilization are the cost model — the numbers that convert people into revenue.
~62,850 employees, ~56,600 delivery professionals, ~76.8% utilization — the operating engine, quantified.
As of December 31, 2025, 2024 and 2023, we had approximately 62,850, 61,200, and 53,150 employees, respectively, of which approximately 56,600, 55,100, and 47,350 were delivery professionals, respectively. […] For the years ended December 31, 2025, 2024 and 2023, the utilization rates of our delivery professionals were approximately 76.8%, 76.7%, and 74.3%, respectively.
p. 11 · Read in context →
Item 1A. Risk Factors — Risks Related to Geopolitical Events — p. 14 · Read the full section →
Company-specific, not boilerplate: ~14,100 delivery staff sit in Ukraine and Belarus, directly in the war's path.
Concentration of personnel in Ukraine and Belarus and what escalation would force.
In particular, as of December 31, 2025, approximately 14,100 of our global delivery, administrative and support personnel were based in Ukraine and Belarus, both of which are involved in or affected by Russia’s invasion of Ukraine. […] Any escalation of the conflict that includes Belarus or its military could jeopardize our personnel, facilities, and operations in Belarus.
p. 15 · Read in context →
Item 1A. Risk Factors — Risks Related to Artificial Intelligence — p. 16 · Read the full section →
New in FY2025 and existential: management concedes AI tools could let clients replace the very services EPAM sells.
Management's own words on AI as substitution risk — and that it has already weighed on the stock.
AI, large language model, and machine learning technologies enable clients and potential clients to develop, customize, and maintain software solutions internally and could reduce reliance on third-party service providers such as EPAM and our clients that are software product vendors. […] If a significant number of our existing or future clients employ AI-driven tools as a replacement for our services or the software we build, our revenues, anticipated growth and prospects, our financial condition, and our results of operations could be materially adversely affected.
p. 16 · Read in context →
Item 7. Management's Discussion and Analysis — p. 41 · Read the full section →
Where management explains what actually drove results — and how much of 2025's growth was bought, not organic.
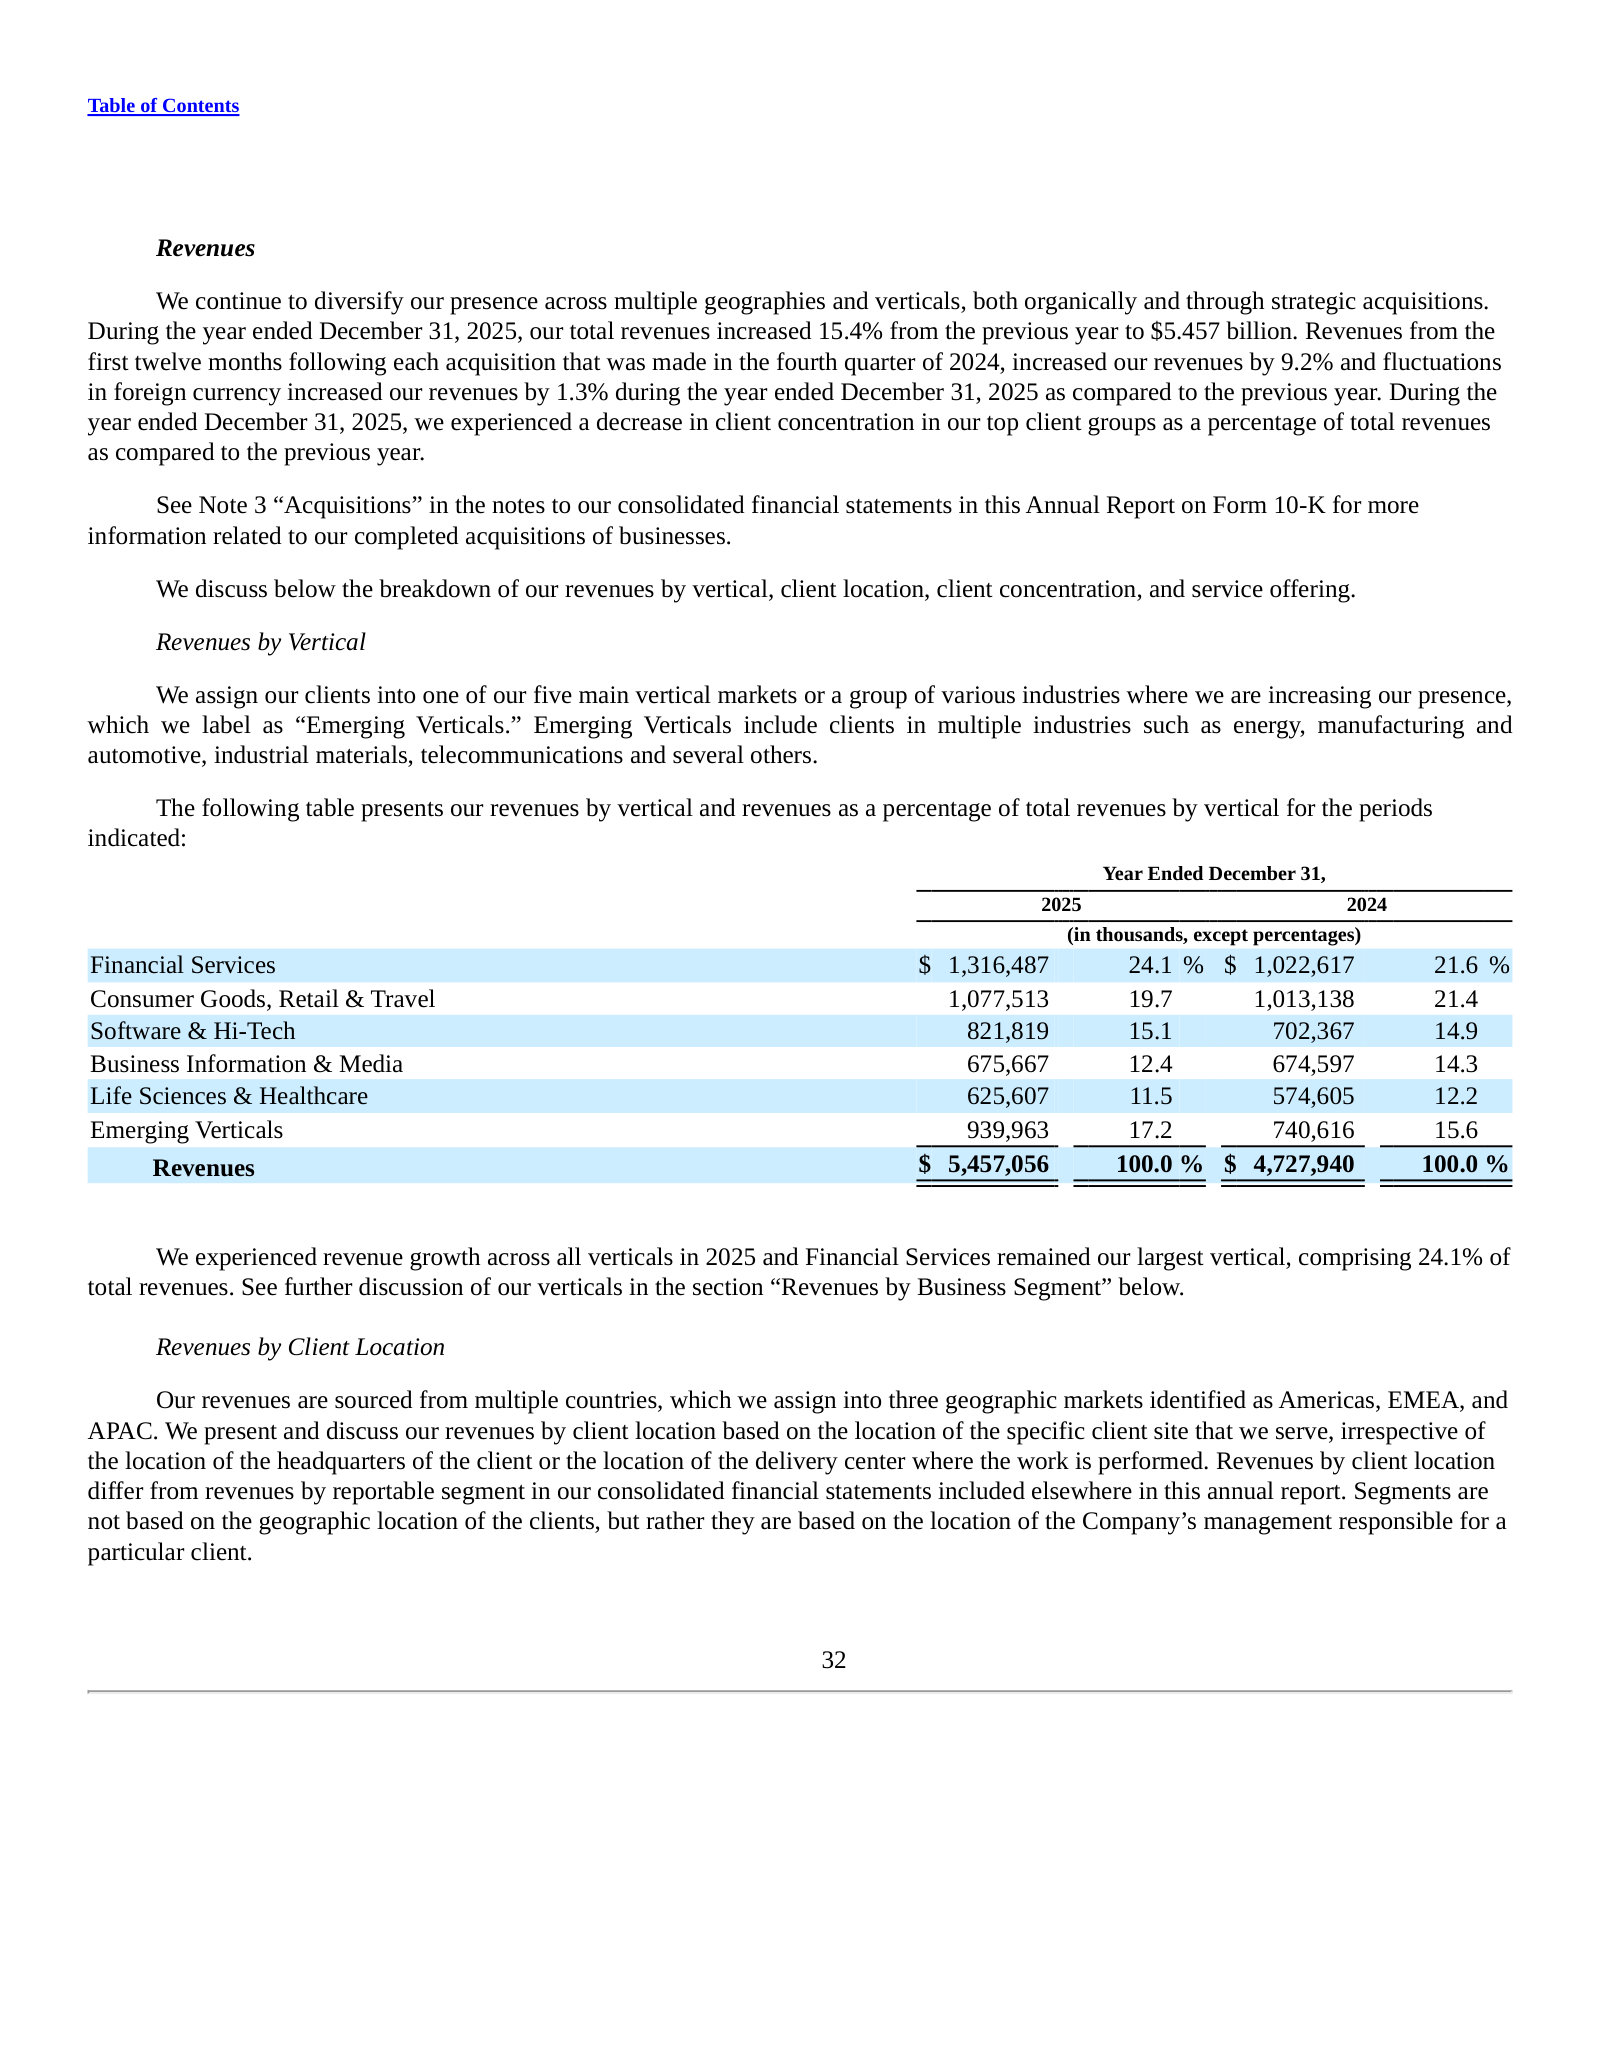
Revenues up 15.4% to $5.457bn — but 9.2 pts came from acquisitions and 1.3 pts from FX.
During the year ended December 31, 2025, our total revenues increased 15.4% from the previous year to $5.457 billion. Revenues from the first twelve months following each acquisition that was made in the fourth quarter of 2024, increased our revenues by 9.2% and fluctuations in foreign currency increased our revenues by 1.3% during the year ended December 31, 2025 as compared to the previous year.
p. 45 · Read in context →
Results by Business Segment — p. 49 · Read the full section →
The reportable segments and a telling redefinition: North America renamed Americas as Latin America becomes material.
The segment rename — a naming change that signals the geographic shift into Latin America.
Starting in 2025, we renamed our North America segment to Americas. The new name reflects the evolving geographic footprint and growth of operations within the segment, particularly in Latin America. This constitutes a naming change only and no changes were made to amounts reported.
p. 49 · Read in context →
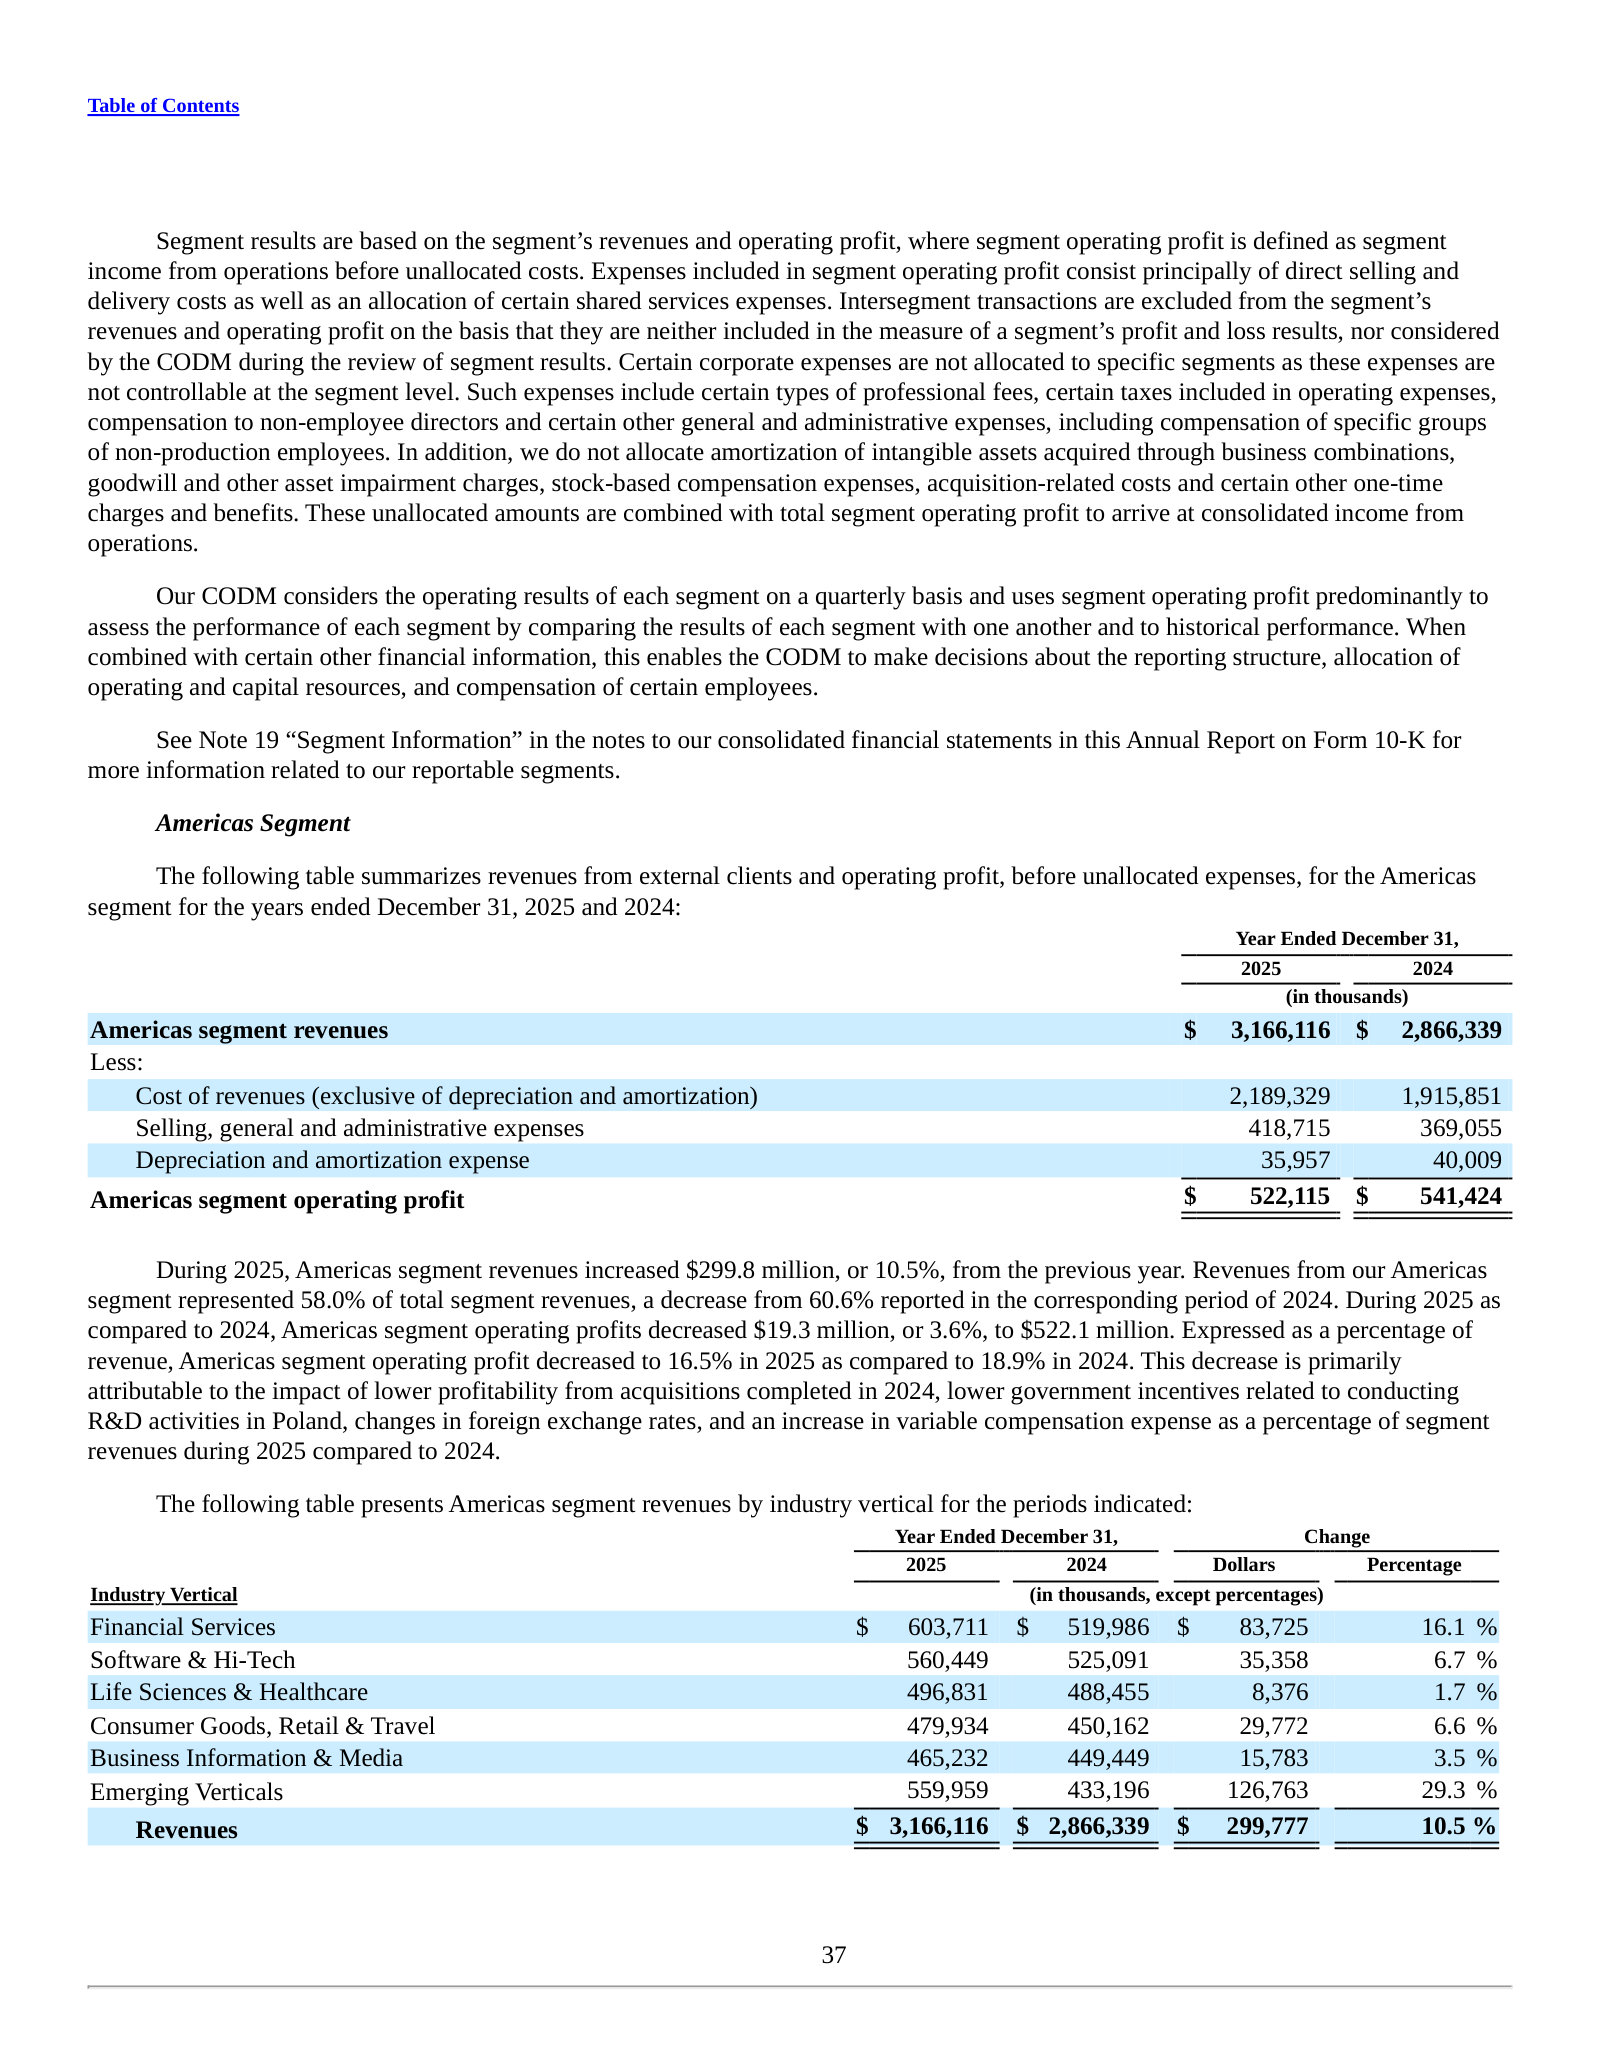
EPAM Systems, Inc. — FY2024 Annual Report (Form 10-K) — FY2024
Included to show the before-picture of the segment redefinition: in FY2024 the same unit was still reported as 'North America.' · Open the full document →
Results by Business Segment — North America Segment — p. 45 · Read the full section →
The prior name and structure, before the 2025 rename to Americas — the redefinition made visible.
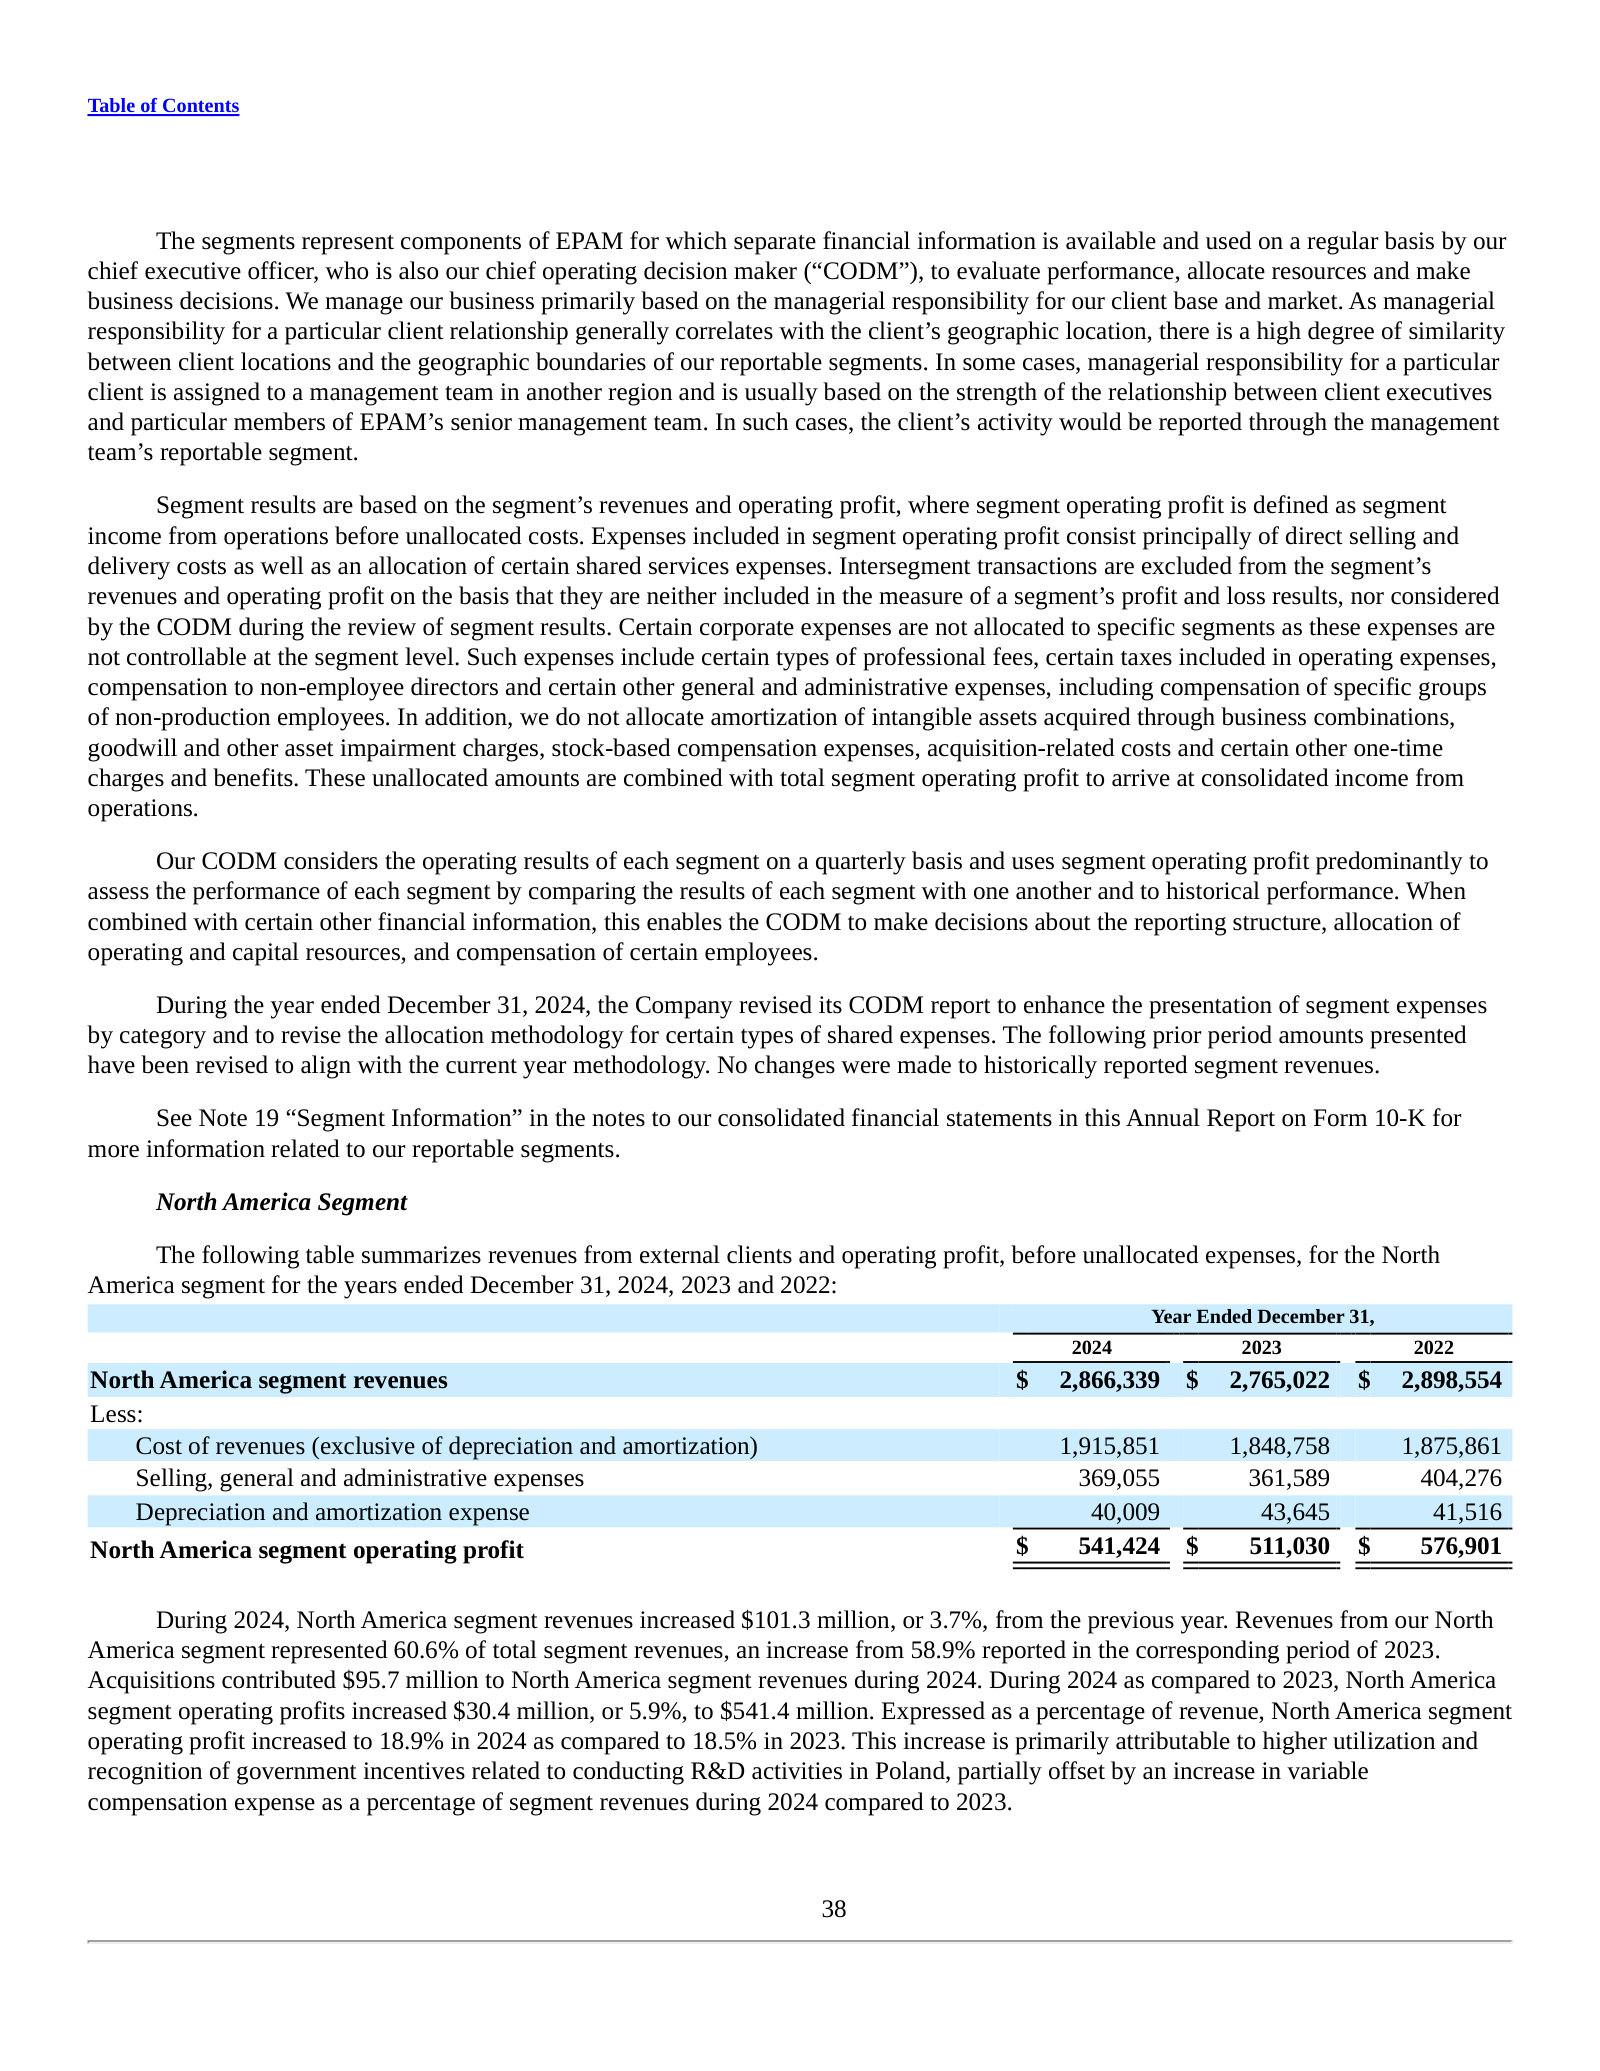
More annual reports
EPAM Systems, Inc. — FY2023 Annual Report (Form 10-K) — FY2023 · 114 pages · The trough year: growth stalled on weak client demand — useful baseline for the AI-era risk narrative. · Open →
EPAM Systems, Inc. — FY2022 Annual Report (Form 10-K) — FY2022 · 102 pages · First 10-K after Russia's invasion of Ukraine — where the war-disruption and Russia-exit disclosures begin. · Open →
EPAM Systems, Inc. — FY2021 Annual Report (Form 10-K) — FY2021 · 116 pages · The pre-war peak-growth edition — a picture of the business before Ukraine reshaped its delivery map. · Open →
Competitors describe EPAM Systems, Inc.'s market in their own filings and calls. These verified passages and visual pages show where their strategies meet, using source documents preserved in Sources.
Endava plc (DAVA)
Endava is EPAM's closest listed pure-play analog — a next-generation digital-engineering firm with nearshore delivery in Central Europe and Latin America and an “AI-native” positioning — and it names EPAM Systems by name as a primary competitor in its 20-F.
Endava's FY2025 20-F names EPAM Systems among its primary “next-generation digital IT service providers,” a peer set it separates from traditional consultancies and offshore IT firms.
The market for technology and IT services is intensely competitive, highly fragmented and subject to rapid change and evolving industry standards and we expect competition to intensify. […] Our primary competitors include next-generation digital IT service providers, such as Globant S.A., EPAM Systems, Grid Dynamics and Thoughtworks, digital agencies and consulting companies, such as Ideo, McKinsey & Company and Publicis Sapient, global consulting and traditional IT services companies, such as Accenture PLC, Capgemini SE, Cognizant Technology Solutions Corporation and Tata Consultancy Services Limited, and in-house development by our clients of their technology and IT capabilities.
p. 23 · Read in context →
Endava's self-description of the market it serves — “next-generation technology services” delivered with an “AI-native approach” across the full digital-transformation lifecycle — mirrors EPAM's own platform-engineering framing.
We are a leading provider of next-generation technology services, dedicated to enabling our clients to accelerate growth, tackle complex challenges and thrive in evolving markets. By combining innovative technologies and deep industry expertise with an AI-native approach, we consult and partner with our clients to create solutions that drive transformation, augment intelligence and deliver lasting impact. From ideation to production, we support our clients with tailor-made solutions at every stage of their digital transformation, regardless of industry, region or scale.
p. 53 · Read in context →
Endava's CEO ties its “AI-native engineering” go-to-market pivot to a Mastercard partnership in next-generation payments — an industry-vertical, partner-led AI play of the kind EPAM also pursues.
John Cotterell (Chief Executive Officer): As part of our go-to-market pivot, we expanded our strategic partner network enlarging our market reach and solution set. I want to highlight our recently announced collaboration with Mastercard which combines Endava's AI-native engineering and industry expertise with Mastercard's global reach and data-driven products and services. Together, we believe we have a powerful engine to accelerate the adoption and scale of next-generation payments and immersive experiences for Endava's clients worldwide.
p. 8 · Read in context →
Globant S.A. (GLOB)
Globant is a digitally-native, “AI-first” engineering-services firm competing head-to-head with EPAM for digital-transformation and GenAI build work; its FY2025 20-F lists EPAM Systems by name as a competitor.
Globant's FY2025 annual report lists EPAM Systems by name among the technology-service providers it competes with, alongside the traditional consultancies and other next-gen engineering firms.
The markets in which we operate are competitive and subject to rapid change. We compete with global IT service providers. […] We compete with various technology service providers such as Accenture, Atos, Capgemini, Cognizant Technology Solutions, Deloitte Digital, DXC Technology, Endava, EPAM Systems, Inc., Genpact, GlobalLogic, Grid Dynamics, HCL Technologies, Infosys, Tata Consultancy Services, CI&T and Wipro, among others.
p. 38 · Read in context →
Globant's stated AI mix — over a thousand GenAI/CoreAI/data engagements, roughly a third of its projects, plus 900+ AI-readiness projects in the pipeline — sizes the AI-first demand pool it and EPAM both chase.
Martín Migoya (Co-Founder & CEO): Since doubling down on our 100 square strategy this year, we have seen the execution being shown in bookings and revenue. Our top five clients grew sequentially by 2.1%, exceeding the company's average growth over this period. The share of clients we have identified as 100 square potential as part of our total bookings is currently 56.7%, up from 50% last year. Today, we have over a thousand engagements related to GenAI, CoreAI, or data currently running, representing a third of our overall projects. We have over 900 projects related to AI readiness in our pipeline.
p. 6 · Read in context →
Grid Dynamics Holdings, Inc. (GDYN)
Grid Dynamics is an enterprise-AI and platform-engineering firm with a CEE/Latin America/India delivery footprint closely resembling EPAM's; its FY2025 10-K names EPAM Systems as a primary competitor.
Grid Dynamics' FY2025 10-K names EPAM Systems among its primary competitors and frames the contest around low-cost delivery geographies (India, China, CEE, Latin America) that EPAM also relies on.
We face competition from offshore IT services providers in outsourcing destinations with low wage costs such as India, China, CEE countries and Latin America, as well as competition from large, global consulting and outsourcing firms and in-house IT departments of large corporations. […] Our primary competitors include global consulting and traditional IT service providers such as Accenture plc, EPAM Systems, Inc., Capgemini SE, Cognizant Technology Solutions Corporation, Infosys Technologies, Tata Consultancy Services Limited,
p. 33 · Read in context →
Grid Dynamics' CEO reports AI at 29.3% of revenue and pitches a “product-centric engineering” model for Fortune 1000 clients as differentiation from headcount-led incumbents — the same argument EPAM makes against legacy integrators.
Leonard Livschitz (Chief Executive Officer): Our first quarter results support that conviction with AI revenue reaching 29.3% of total company revenue, growing nearly 60% year over-year. […] Large enterprises are increasingly seeking highly capable, nimble partners like Grid Dynamics, who can move quickly and deliver meaningful AI outcomes rather than relying on incumbent global system integrators burdened by legacy delivery models. In many ways, headcount leverage is no longer a competitive moat and differentiation comes from domain knowledge, AI capabilities and ability to rapidly scale relevant expertise. We're not a systems integrator. We're a product-centric engineering company focused on solving the most complex mission-critical challenges for Fortune 1000 clients
p. 1 · Read in context →
Grid Dynamics defines itself as an “Enterprise AI transformation partner for the Fortune 1000,” built on data/ML, cloud and product engineering delivered from the Americas, Europe and India — the identical remit and geography as EPAM.
Grid Dynamics Holdings, Inc. […] is an Enterprise Artificial Intelligence (“AI”) transformation partner for the Fortune 1000. We combine deep AI expertise with proven enterprise-scale delivery to help clients identify where to invest in AI, deliver systems that work at scale, and capture real business value from AI deployments. […] This is supported by deep capabilities and ongoing investment in data and machine learning platform engineering, cloud platform and product engineering, Internet of Things (“IoT”) and edge computing, and digital engagement services. Founded in 2006, Grid Dynamics is headquartered in Silicon Valley with offices across the Americas, Europe, and India.
p. 7 · Read in context →
Cognizant Technology Solutions Corporation (CTSH)
Cognizant is a large global IT-services firm that competes with EPAM across digital, cloud and AI-enabled software work and names EPAM Systems by name as a direct competitor in its 10-K; its scale illustrates the size asymmetry EPAM faces.
Cognizant's FY2025 10-K lists EPAM Systems by name among its direct competitors and cites “digital and AI capabilities” as a principal competitive factor.
The markets for our services are highly competitive, characterized by a large number of participants and subject to rapid change. […] Our direct competitors include, among others, Accenture, Atos, Capgemini, CGI, Deloitte Digital, DXC Technology, EPAM Systems, Genpact, HCL Technologies, IBM Consulting, Infosys Technologies, Tata Consultancy Services and Wipro. […] The principal competitive factors affecting the markets for our services include the provider’s reputation and experience, strategic advisory capabilities, digital and AI capabilities, performance and reliability, responsiveness to customer needs, financial stability, corporate governance and competitive pricing of services.
p. 18 · Read in context →
Cognizant's Flowsource platform — generative and agentic AI across the software development life cycle, in use at over 70 clients — collides directly with EPAM's core digital platform engineering and GenAI-enabled delivery.
Ravi Kumar S (Chief Executive Officer): A primary tool for executing Vector 1 is our Flowsource platform, which integrates generative and agentic AI across the full software development life cycle. Flowsource is now being used at over 70 clients with an additional 120 in the pipeline.
p. 2 · Read in context →
Cognizant's FY2025 headcount of roughly 351,600 — heavily concentrated in India-based global delivery — marks the scale gap against EPAM's far smaller engineering base in the same delivery-model market.
As of December 31, 2025, we had approximately 351,600 employees, with 256,900 in India, 41,600 in North America, 14,600 in Continental Europe, 7,800 in the United Kingdom and 30,700 in various other locations throughout the rest of the world.
p. 19 · Read in context →
Accenture plc (ACN)
Accenture is the largest player in the digital-transformation and GenAI services market EPAM competes in; it does not name EPAM, but its market-sizing and its integrated “reinvention services” model define the competitive backdrop and demand pool.
Accenture cites IDC's forecast that the advanced-AI market grows more than 40% through 2029 and reports adding roughly 100 new advanced-AI clients per quarter — an outside sizing of the GenAI demand pool EPAM also targets.
Julie Sweet (Chair and Chief Executive Officer): IDC estimates that the total addressable market for advanced AI is expected to grow more than 40% through 2029 […] Over the last nine quarters, we've seen about 100 incremental clients initiate advanced AI projects with us each quarter
p. 16 · Read in context →
Accenture's description of its September 2025 “reinvention services” reorganization — one unit selling multi-service deals with AI and data embedded — is the integrated-delivery model EPAM competes against for large transformation mandates.
Julie Sweet (Chair and Chief Executive Officer): On September 1, we launched reinvention services, which brings all of Accenture's capabilities into a single unit. Nearly 80% of our large deals are multi-service. The model as we fully roll it out will make it faster and simpler to sell and deliver everything Accenture offers and to rotate our offerings to embed more AI and data and equip our people.
p. 8 · Read in context →
Infosys Limited (INFY)
Infosys is a large India-centric IT-services firm competing with EPAM for digital-transformation, cloud and GenAI engineering mandates; it does not name EPAM, but its Topaz/Cobalt platforms and AI-services push map onto EPAM's offering set.
Infosys frames a “large addressable market for AI services” across six areas and positions its Topaz Fabric (AI) and Cobalt (cloud) platforms to serve it — the same digital, cloud and GenAI engineering demand EPAM pursues.
Salil Parekh (Chief Executive Officer and Managing Director): We see a large addressable market for AI services across six areas; AI strategy and engineering, data, process, legacy modernization, physical AI and trust. With our Topaz Fabric platform for AI, our Cobalt platform for cloud, we have differentiated capabilities to serve our clients across the six areas of AI.
p. 26 · Read in context →
Infosys reports AI-led programs across 90% of its top-200 clients and AI-services revenue at 5.5% of the total, with over 325,000 employees being re-skilled on AI — an adoption-and-scale benchmark for EPAM's own AI positioning.
Infosys is emerging as a leader in AI services, with AI-led programs now deployed across 90% of our top 200 clients and rapidly scaling across industries. […] For Q3, we shared that our revenue from these six areas was 5.5% of our total revenue and growing at a significantly faster pace than the company. We are executing on our strategy of pivoting to AI services at speed. […] Our focus is to continuously re-skill our over 3,25,000 employees on AI.
p. 19 · Read in context →
More peer documents
Endava — FY2024 annual report (20-F) — FY2024 · 214 pages · Prior-year competition and business sections for the EPAM-naming trendline and Endava's earlier next-gen-services framing. · Open →
Globant — Q4 FY2025 earnings call — Q4 FY2025 · 40 pages · Fuller AI Pods rollout: management gives ARR traction and names anchor clients (FIFA, Santander, LaLiga) plus an 800+ client / 28,000-people delivery base. · Open →
Accenture — FY2025 annual report (10-K) — FY2025 · 102 pages · Market description, services taxonomy and headcount for the scale/market backdrop behind Accenture's reinvention-services model. · Open →
Source: S&P Capital IQ consensus via Xpressfeed · Generated 2026-07-18.
Street snapshot
The 17 price targets carry a mean of 135.94 and a median of 131 in USD but span a wide 83 to 235.
Currency: USD · Scale: money in millions, absolute (per share) · Analyst counts shown explicitly; recommendation respondents: 19.
| Street view | Reading | Analysts |
|---|---|---|
| Recommendation mix | Buy 8, Outperform 3, Hold 8, Underperform 0, Sell 0 | 19 |
| Consensus score | 2.00 | 19 |
| Target price | mean 135.9; high 235.0; low 83.00 | 17 |
Forward table
The company pays no dividend (DPS of 0) and carries a deepening net-cash position, with net debt moving from -1,341m in FY2025 to -2,354m by FY2028, while coverage thins to a single estimate by FY2029.
Currency: USD · Scale: money in millions, absolute (per share) · Analyst count is the estimate count for each period and metric.
| Period | Metric | Mean | YoY | Analysts | Low / high |
|---|---|---|---|---|---|
| FY0E | Revenue | 5,725 | 4.9% | 19 | 5,675 / 5,765 |
| FY0E | EBITDA | 949.7 | 7.3% | 7 | 940.4 / 957.1 |
| FY0E | EBIT | 891.2 | 7.9% | — | — / — |
| FY0E | Net income (GAAP) | 438.1 | 16.0% | 13 | 410.3 / 456.4 |
| FY0E | Net income (normalized) | 687.1 | 7.4% | — | — / — |
| FY0E | EPS (GAAP) | 8.31 | 23.6% | 12 | 7.79 / 8.67 |
| FY0E | EPS (normalized) | 13.05 | 13.4% | 19 | 12.82 / 13.15 |
| FY0E | Free cash flow | 572.6 | -0.6% | — | — / — |
| FY0E | Dividend per share | 0.00 | — | — | — / — |
| FY0E | Gross margin | 29.7% | 2.2% | — | — / — |
| FY0E | Capital expenditure | -53.77 | 33.3% | — | — / — |
| FY0E | Net debt | -1,327 | -1.0% | — | — / — |
| FY0E | Cash from operations | 581.8 | -2.5% | — | — / — |
| FY0E | ROE | 16.9% | 8.9% | — | — / — |
| FY+1E | Revenue | 6,057 | 5.8% | 19 | 5,944 / 6,180 |
| FY+1E | EBITDA | 1,027 | 8.2% | 7 | 1,007 / 1,064 |
| FY+1E | EBIT | 958.7 | 7.6% | — | — / — |
| FY+1E | Net income (GAAP) | 505.5 | 15.4% | 13 | 453.0 / 543.7 |
| FY+1E | Net income (normalized) | 729.7 | 6.2% | — | — / — |
| FY+1E | EPS (GAAP) | 9.83 | 18.4% | 12 | 8.86 / 10.44 |
| FY+1E | EPS (normalized) | 14.14 | 8.4% | 19 | 13.08 / 14.72 |
| FY+1E | Free cash flow | 653.5 | 14.1% | — | — / — |
| FY+1E | Dividend per share | 0.00 | — | — | — / — |
| FY+1E | Gross margin | 30.0% | 0.8% | — | — / — |
| FY+1E | Capital expenditure | -53.60 | -0.3% | — | — / — |
| FY+1E | Net debt | -1,738 | 30.9% | — | — / — |
| FY+1E | Cash from operations | 716.6 | 23.2% | — | — / — |
| FY+1E | ROE | 17.4% | 2.5% | — | — / — |
| FY+2E | Revenue | 6,443 | 6.4% | 11 | 6,279 / 6,671 |
| FY+2E | EBITDA | 1,114 | 8.4% | 4 | 1,064 / 1,180 |
| FY+2E | EBIT | 1,038 | 8.2% | — | — / — |
| FY+2E | Net income (GAAP) | 541.2 | 7.1% | 7 | 505.8 / 612.8 |
| FY+2E | Net income (normalized) | 783.7 | 7.4% | — | — / — |
| FY+2E | EPS (GAAP) | 10.87 | 10.5% | 7 | 10.14 / 11.82 |
| FY+2E | EPS (normalized) | 15.26 | 7.9% | 11 | 13.86 / 16.55 |
| FY+2E | Free cash flow | 699.0 | 7.0% | — | — / — |
| FY+2E | Dividend per share | 0.00 | — | — | — / — |
| FY+2E | Gross margin | 30.0% | -0.0% | — | — / — |
| FY+2E | Capital expenditure | -52.73 | -1.6% | — | — / — |
| FY+2E | Net debt | -2,354 | 35.5% | — | — / — |
| FY+2E | Cash from operations | 732.2 | 2.2% | — | — / — |
| FY+2E | ROE | 16.2% | -6.7% | — | — / — |
| Q2 FY2026 | Revenue | 1,408 | 4.0% | 17 | 1,399 / 1,414 |
| Q2 FY2026 | EBITDA | 230.4 | 6.5% | 6 | 228.3 / 231.9 |
| Q2 FY2026 | EBIT | 217.1 | 12.6% | — | — / — |
| Q2 FY2026 | Net income (GAAP) | 97.53 | 10.8% | 12 | 95.50 / 104.6 |
| Q2 FY2026 | Net income (normalized) | 165.2 | 11.4% | — | — / — |
| Q2 FY2026 | EPS (GAAP) | 1.86 | 19.4% | 10 | 1.81 / 2.00 |
| Q2 FY2026 | EPS (normalized) | 3.14 | 13.5% | 17 | 3.10 / 3.17 |
| Q2 FY2026 | Free cash flow | 104.3 | 33.8% | — | — / — |
| Q2 FY2026 | Dividend per share | 0.00 | — | — | — / — |
| Q2 FY2026 | Gross margin | 29.4% | 1.9% | — | — / — |
| Q2 FY2026 | Capital expenditure | -10.39 | 24.9% | — | — / — |
| Q2 FY2026 | Cash from operations | 164.4 | 43.5% | — | — / — |
| Q3 FY2026 | Revenue | 1,445 | 3.6% | 17 | 1,422 / 1,472 |
| Q3 FY2026 | EBITDA | 248.8 | 5.5% | 6 | 245.7 / 253.8 |
| Q3 FY2026 | EBIT | 232.4 | 5.4% | — | — / — |
| Q3 FY2026 | Net income (GAAP) | 124.3 | 16.3% | 12 | 106.5 / 132.0 |
| Q3 FY2026 | Net income (normalized) | 179.3 | 6.0% | — | — / — |
| Q3 FY2026 | EPS (GAAP) | 2.40 | 25.6% | 10 | 2.04 / 2.53 |
| Q3 FY2026 | EPS (normalized) | 3.44 | 11.8% | 17 | 3.31 / 3.53 |
| Q3 FY2026 | Free cash flow | 257.7 | 10.3% | — | — / — |
| Q3 FY2026 | Dividend per share | 0.00 | — | — | — / — |
| Q3 FY2026 | Gross margin | 30.5% | -0.3% | — | — / — |
| Q3 FY2026 | Capital expenditure | -9.90 | 17.0% | — | — / — |
| Q3 FY2026 | Cash from operations | 194.9 | -20.7% | — | — / — |
| Q4 FY2026 | Revenue | 1,474 | 4.7% | 16 | 1,453 / 1,494 |
| Q4 FY2026 | EBITDA | 258.1 | 6.2% | 5 | 256.2 / 259.9 |
| Q4 FY2026 | EBIT | 240.9 | 7.8% | — | — / — |
| Q4 FY2026 | Net income (GAAP) | 132.3 | 21.0% | 12 | 116.6 / 136.9 |
| Q4 FY2026 | Net income (normalized) | 187.6 | 7.7% | — | — / — |
| Q4 FY2026 | EPS (GAAP) | 2.55 | 28.7% | 10 | 2.24 / 2.68 |
| Q4 FY2026 | EPS (normalized) | 3.61 | 10.6% | 16 | 3.54 / 3.69 |
| Q4 FY2026 | Free cash flow | 279.0 | 14.4% | — | — / — |
| Q4 FY2026 | Dividend per share | 0.00 | — | — | — / — |
| Q4 FY2026 | Gross margin | 30.9% | 2.5% | — | — / — |
| Q4 FY2026 | Capital expenditure | -13.52 | 12.8% | — | — / — |
| Q4 FY2026 | Cash from operations | 227.8 | -2.2% | — | — / — |
| Q1 FY2027 | Revenue | 1,472 | 5.2% | 13 | 1,432 / 1,505 |
| Q1 FY2027 | EBITDA | 230.7 | 7.5% | 3 | 225.2 / 235.0 |
| Q1 FY2027 | EBIT | 211.6 | 8.1% | — | — / — |
| Q1 FY2027 | Net income (GAAP) | 103.0 | 24.8% | 10 | 86.06 / 117.0 |
| Q1 FY2027 | Net income (normalized) | 162.4 | 7.9% | — | — / — |
| Q1 FY2027 | EPS (GAAP) | 1.97 | 29.8% | 8 | 1.67 / 2.19 |
| Q1 FY2027 | EPS (normalized) | 3.15 | 10.1% | 13 | 2.83 / 3.31 |
| Q1 FY2027 | Free cash flow | 51.00 | -16.4% | — | — / — |
| Q1 FY2027 | Dividend per share | 0.00 | — | — | — / — |
| Q1 FY2027 | Gross margin | 28.7% | 3.5% | — | — / — |
| Q1 FY2027 | Capital expenditure | -16.67 | 66.4% | — | — / — |
| Q1 FY2027 | Cash from operations | 84.41 | 318.7% | — | — / — |
Estimate momentum
Over the past 180 days the street trimmed its FY2027 revenue estimate from 6,319 to 6,057 while nudging normalized EPS up from 13.90 to 14.14, and FY2028 shows the same shape, revenue cut from 6,775 to 6,443 and normalized EPS raised from 14.33 to 15.26. The revenue markdowns and EPS markups run across both years rather than a single-period move.
Currency: USD · Scale: money in millions, absolute (per share) · Point-in-time consensus; analyst count is shown where supplied.
| Period | Metric | Lookback | Then | Now | Direction / magnitude | Analysts |
|---|---|---|---|---|---|---|
| 2027 | EPS (normalized) | 30d | 14.11 | 14.14 | up 0.2% | — |
| 2027 | EPS (normalized) | 90d | 13.93 | 14.14 | up 1.5% | — |
| 2027 | EPS (normalized) | 180d | 13.90 | 14.14 | up 1.7% | — |
| 2027 | Revenue | 30d | 6,075 | 6,057 | down 0.3% | — |
| 2027 | Revenue | 90d | 6,206 | 6,057 | down 2.4% | — |
| 2027 | Revenue | 180d | 6,319 | 6,057 | down 4.1% | — |
| 2028 | EPS (normalized) | 30d | 15.16 | 15.26 | up 0.7% | — |
| 2028 | EPS (normalized) | 90d | 15.20 | 15.26 | up 0.4% | — |
| 2028 | EPS (normalized) | 180d | 14.32 | 15.26 | up 6.6% | — |
| 2028 | Revenue | 30d | 6,459 | 6,443 | down 0.2% | — |
| 2028 | Revenue | 90d | 6,659 | 6,443 | down 3.2% | — |
| 2028 | Revenue | 180d | 6,775 | 6,443 | down 4.9% | — |
Beat / miss record
Across the last eight quarters the company beat consensus on both revenue and normalized EPS every time. Revenue surprises were modest at roughly +0.4% to +2.9%, while normalized-EPS beats ran larger and more variable, from about +1.7% up to +15.6%.
Current sequences by metric: Revenue: 8 consecutive beats; EPS (normalized): 8 consecutive beats.
Currency: USD · Scale: money in millions, absolute (per share) · Consensus is captured before each actual first became effective; analyst count shown per observation.
| Quarter | Metric | Consensus as of | Actual | Surprise | Outcome | Analysts |
|---|---|---|---|---|---|---|
| Q1 FY2026 | Revenue | 1,394 | 1,400 | 0.4% | Beat | — |
| Q1 FY2026 | EPS (normalized) | 2.75 | 2.86 | 3.8% | Beat | — |
| Q4 FY2025 | Revenue | 1,391 | 1,408 | 1.2% | Beat | — |
| Q4 FY2025 | EPS (normalized) | 3.16 | 3.26 | 3.2% | Beat | — |
| Q3 FY2025 | Revenue | 1,375 | 1,394 | 1.4% | Beat | — |
| Q3 FY2025 | EPS (normalized) | 3.03 | 3.08 | 1.7% | Beat | — |
| Q2 FY2025 | Revenue | 1,333 | 1,353 | 1.5% | Beat | — |
| Q2 FY2025 | EPS (normalized) | 2.61 | 2.77 | 6.0% | Beat | — |
| Q1 FY2025 | Revenue | 1,282 | 1,302 | 1.5% | Beat | — |
| Q1 FY2025 | EPS (normalized) | 2.27 | 2.41 | 6.1% | Beat | — |
| Q4 FY2024 | Revenue | 1,213 | 1,248 | 2.9% | Beat | — |
| Q4 FY2024 | EPS (normalized) | 2.75 | 2.84 | 3.1% | Beat | — |
| Q3 FY2024 | Revenue | 1,152 | 1,168 | 1.4% | Beat | — |
| Q3 FY2024 | EPS (normalized) | 2.70 | 3.12 | 15.6% | Beat | — |
| Q2 FY2024 | Revenue | 1,140 | 1,147 | 0.6% | Beat | — |
| Q2 FY2024 | EPS (normalized) | 2.26 | 2.45 | 8.5% | Beat | — |
Where the street disagrees
Disagreement is concentrated in the outer years and in GAAP figures. Thin coverage, down to a single estimate on some FY2029 lines, limits how much to read from the widest spreads.
Currency: USD · Scale: money in millions, absolute (per share) · Dispersion is high-low divided by absolute mean; analyst count shown per item.
| Period | Metric | Mean | Low | High | Spread / mean | Analysts |
|---|---|---|---|---|---|---|
| Q1 FY2027 | Net income (GAAP) | 103.0 | 86.06 | 117.0 | 30.0% | 10 |
| Q1 FY2027 | EPS (GAAP) | 1.97 | 1.67 | 2.19 | 26.4% | 8 |
| Q3 FY2026 | Net income (GAAP) | 124.3 | 106.5 | 132.0 | 20.5% | 12 |
| Q3 FY2026 | EPS (GAAP) | 2.40 | 2.04 | 2.53 | 20.4% | 10 |
| 2028 | Net income (GAAP) | 541.2 | 505.8 | 612.8 | 19.8% | 7 |
Source: Visible Alpha consensus via S&P Xpressfeed · Consensus as of 2026-07-15 · generated 2026-07-18.
Model trust
This reads as a genuine consensus rather than a single-broker view.
Base currency: USD · VA scales normalized from Abs, M; item currencies and units retained · Coverage depth and vintage; broker count is the maximum represented.
| Brokers | Line items | Last revision |
|---|---|---|
| 16 | 379 | 2026-07-15 |
Operating KPIs
Base currency: USD · VA scales normalized from Abs, M; item currencies and units retained · FY-1A / FY0E / FY+1E; broker count shown per KPI.
| Operating KPI | Source | FY-1A | FY0E | FY+1E | Brokers |
|---|---|---|---|---|---|
| Total revenues | CD | 5,441,470.60bn Amount | 5,723,108.29bn Amount | 6,051,967.29bn Amount | 16 |
| Cost of revenues | CD | 3,874,782.55bn Amount | 4,039,033.97bn Amount | 4,245,265.81bn Amount | 15 |
| Depreciation and amortization expense | CD | 122,314.63bn Amount | 127,066.00bn Amount | 128,146.83bn Amount | 15 |
| Interest and other income | CD | 14,615.36bn Amount | 7,426.11bn Amount | 8,663.99bn Amount | 15 |
| Nonoperating income/(expense) - Operating | CD | 11,771.88bn Amount | 10,807.11bn Amount | 9,634.87bn Amount | 15 |
| Cost of revenues - Operating | CD | 3,790,576.18bn Amount | 3,950,556.37bn Amount | 4,152,845.87bn Amount | 14 |
| Foreign exchange loss and others | CD | -21,526.81bn Amount | -2,000.51bn Amount | -6,557.80bn Amount | 14 |
| Nonoperating income/(expense) | CD | -6,912.85bn Amount | 5,343.04bn Amount | 4,574.14bn Amount | 14 |
| SBC in cost of revenue | CD | 84,738.77bn Amount | 87,101.74bn Amount | 92,215.54bn Amount | 14 |
| Total adjustments in Nonoperating income/(expense) | CD | 18,534.72bn Amount | 5,254.61bn Amount | 8,625.93bn Amount | 14 |
| Cash and cash equivalents, beginning of period | CD | 1,289,847.67bn Amount | 1,303,882.77bn Amount | 1,488,344.92bn Amount | 13 |
| Depreciation and amortization | CD | 121,411.87bn Amount | 124,957.54bn Amount | 130,006.48bn Amount | 13 |
P&L bridge
GAAP diluted EPS climbs faster than revenue, from $6.82 to $8.30 to $9.83, while operating (adjusted) diluted EPS runs $11.42 / $13.04 / $14.17.
Base currency: USD · VA scales normalized from Abs, M; item currencies and units retained · Margins are derived against revenue; YoY compares adjacent fiscal columns; broker count shown per line.
| P&L line | FY-1A | FY0E | FY+1E | Brokers |
|---|---|---|---|---|
| Revenue | 5,441,470.60bn Amount | 5,723,108.29bn Amount (5.2% YoY) | 6,051,967.29bn Amount (5.7% YoY) | 16 |
| Gross Profit | 1,646,683.82bn Amount (30.3% margin) | 1,767,005.59bn Amount (30.9% margin; 7.3% YoY) | 1,894,514.42bn Amount (31.3% margin; 7.2% YoY) | 15 |
| Ebitda | 832,026.53bn Amount (15.3% margin) | 920,332.77bn Amount (16.1% margin; 10.6% YoY) | 991,818.81bn Amount (16.4% margin; 7.8% YoY) | 14 |
| Operating Income | 825,918.28bn Amount (15.2% margin) | 890,388.98bn Amount (15.6% margin; 7.8% YoY) | 958,207.37bn Amount (15.8% margin; 7.6% YoY) | 16 |
| Net Income | 639,502.81bn Amount (11.8% margin) | 686,859.44bn Amount (12.0% margin; 7.4% YoY) | 734,400.63bn Amount (12.1% margin; 6.9% YoY) | 16 |
| Eps | 11.42 Amount | 13.04 Amount (14.2% YoY) | 14.17 Amount (8.7% YoY) | 16 |
Consensus dispersion
The disagreement therefore sits below the line and on the pace of reacceleration, not on near-term revenue.
Base currency: USD · VA scales normalized from Abs, M; item currencies and units retained · Top high-low spreads relative to absolute mean; requires at least 3 brokers.
| Line item | Period | Mean | Min | Q1 | Q3 | Max | Spread / mean | Brokers |
|---|---|---|---|---|---|---|---|---|
| Nonoperating income/(expense) | 3QFY-2025 | -359.96bn Amount | -18,186.00bn Amount | 1,000.00bn Amount | 1,052.61bn Amount | 3,767.33bn Amount | 6098.8% | 13 |
| Nonoperating income/(expense) | 1QFY-2026 | -109.71bn Amount | -2,500.00bn Amount | -1,610.62bn Amount | 979.28bn Amount | 3,083.73bn Amount | 5089.6% | 7 |
| Total adjustments in Nonoperating income/(expense) | 2QFY-2027 | 513.87bn Amount | -11,629.44bn Amount | 1,335.31bn Amount | 2,400.00bn Amount | 3,018.95bn Amount | 2850.6% | 9 |
| Nonoperating income/(expense) - Operating | 2QFY-2027 | 1,349.62bn Amount | -11,129.44bn Amount | 1,309.73bn Amount | 2,929.26bn Amount | 4,370.18bn Amount | 1148.4% | 14 |
| Foreign exchange loss and others | 4QFY-2026 | -786.24bn Amount | -3,000.00bn Amount | -3,000.00bn Amount | 2,198.20bn Amount | 4,363.76bn Amount | 936.6% | 13 |
| Nonoperating income/(expense) | 3QFY-2026 | 858.73bn Amount | -1,000.00bn Amount | -1,000.00bn Amount | 2,773.37bn Amount | 6,853.30bn Amount | 914.5% | 14 |
Quarterly path
Base currency: USD · VA scales normalized from Abs, M; item currencies and units retained · Next four supplied quarters; final column is maximum broker coverage in the row.
| Quarter | Total revenues | Cost of revenues | Depreciation and amortization expense | Interest and other income | Nonoperating income/(expense) - Operating | Total revenue | EPS Diluted, Applicable to common stockholders($) | Broker coverage |
|---|---|---|---|---|---|---|---|---|
| 3QFY-2026 | 1,446,290.33bn Amount | 1,008,969.70bn Amount | 31,984.86bn Amount | 1,823.21bn Amount | 3,053.76bn Amount | 1,446,290.33bn Amount | 3.44 Amount | 16 |
| 4QFY-2026 | 1,469,775.73bn Amount | 1,019,087.78bn Amount | 32,225.02bn Amount | 2,939.73bn Amount | 4,467.03bn Amount | 1,469,775.73bn Amount | 3.60 Amount | 16 |
| 1QFY-2027 | 1,471,413.25bn Amount | 1,050,662.51bn Amount | 31,592.14bn Amount | 2,089.23bn Amount | 1,704.55bn Amount | 1,471,413.25bn Amount | 3.17 Amount | 15 |
| 2QFY-2027 | 1,489,629.66bn Amount | 1,048,901.16bn Amount | 31,530.21bn Amount | 2,153.25bn Amount | 1,349.62bn Amount | 1,489,629.66bn Amount | 3.43 Amount | 15 |
40 stale period values omitted; 4 line items fully removed.
Source: S&P Capital IQ transcripts via Xpressfeed · latest indexed call 2026-05-07 · generated 2026-07-18.
Latest call digest
EPAM Systems, Inc., Q1 2026 Earnings Call, May 07, 2026 · 2026-05-07T12:00:00
Q1 2026 call — May 07, 2026. EPAM reported Q1 revenue of $1.4 billion, up 7.6% year-over-year (3.7% organic constant currency), at the high end of its outlook. Pure AI-native revenues topped $125 million, up nearly 20% sequentially and a fifth straight quarter of double-digit sequential growth, and management reaffirmed its $600 million AI-native target for 2026. The company also announced a multiyear applied-AI partnership with Anthropic.
The prepared remarks led with momentum — AI-native traction, a growing large-deal pipeline, and gross-margin improvement in the quarter. The consequential news, however, was a cut to the full-year 2026 revenue-growth outlook to 4%–6.5% (from 4.5%–7.5% a quarter earlier), attributed to higher energy prices, Middle East uncertainty, North America underperformance, and a subset of clients delaying decisions. Q2 guidance implies roughly 4% year-over-year growth at the midpoint.
The Q&A concentrated on second-half visibility. Management leaned on a pipeline of close to 10 outsized, non-T&M vendor-consolidation deals to support a stronger back half, but said only a small, risk-adjusted subset is embedded in guidance and that the midpoint does not depend on winning them. Analysts pressed on what the low versus high end implies, on margin trajectory, and on AI tokenomics — where clients currently bear token costs and the commercial model is still evolving. On pricing, management said it is not seeing rate compression.
Participant coverage from the latest call.
| Group | Participants | Count |
|---|---|---|
| Management | Operator; Mike Rowshandel — Head of Investor Relations, EPAM Systems, Inc.; Balazs Fejes — President, CEO & Director, EPAM Systems, Inc.; Jason Peterson — Senior VP, CFO & Treasurer, EPAM Systems, Inc. | 4 |
| Analysts | Bryan Bergin — MD & Analyst, TD Cowen, Research Division; Margaret Nolan — Partner & Research Analyst of Technology, Media, and Communications, William Blair & Company L.L.C., Research Division; Jason Kupferberg — Managing Director & Senior Equity Analyst, Wells Fargo Securities, LLC, Research Division; James Friedman — Senior Analyst, Susquehanna Financial Group, LLLP, Research Division; David Grossman — Managing Director, Stifel, Nicolaus & Company, Incorporated, Research Division; Yu Lee — MD of Equity Research & Senior Equity Analyst, Guggenheim Securities, LLC, Research Division; James Schneider — Senior Research Analyst, Goldman Sachs Group, Inc., Research Division; Bryan Keane — Research Analyst, Citigroup Inc., Research Division; Arvind Ramnani — Managing Director, Truist Securities, Inc., Research Division; James Faucette — MD & Equity Analyst, Morgan Stanley, Research Division | 10 |
Curated latest-call exchanges; one row per analyst topic.
| Analyst | Firm | Topic | What changed in Q&A |
|---|---|---|---|
| Bryan Bergin | TD Cowen, Research Division | Lowered 2026 guide and second-half confidence | Asked whether the cut reflects a few slow large engagements or a broader portfolio dynamic; management pointed to a handful of clients delaying decisions and said it is not assuming the geopolitical backdrop improves. |
| David Grossman | Stifel, Nicolaus & Company, Incorporated, Research Division | Framing the low, mid and high end of the range | Pressed on whether the midpoint holds if large deals keep slipping; management said the midpoint relies on steady, typical execution rather than the outsized deals, which mainly drive the high end. |
| Jason Kupferberg | Wells Fargo Securities, LLC, Research Division | Nature and count of large vendor-consolidation deals | Management sized the pipeline at close to 10 outsized, non-T&M opportunities and said only a small, risk-adjusted subset is assumed in the back-half guide. |
| Margaret Nolan | William Blair & Company L.L.C., Research Division | Whether client weakness could broaden, and the margin bridge | Management said the low end of the range would reflect broadening delays; travel and consumer are already soft while Financial Services and Hi-Tech remain strong. |
| Bryan Keane | Citigroup Inc., Research Division | Contract pricing, tokenomics and Anthropic revenue model | Management said clients currently bear token costs, the commercial model is still being worked through, and it is not seeing rate compression — with some rate increases in Q1. |
| Arvind Ramnani | Truist Securities, Inc., Research Division | Confidence that pipeline converts on schedule | Questioned why prospective-deal conversion is dependable when existing-client visibility fell short; management cited Middle East uncertainty and said it counts on only a modest share converting. |
Theme tracker
Themes are curator-classified across supplied calls.
| Theme | Status | Quarters mentioned | Read-through |
|---|---|---|---|
| AI-native revenue as the primary growth narrative | emerged | Q4 2024, Q1 2025, Q2 2025, Q3 2025, Q4 2025, Q1 2026 | A disclosed AI-native revenue metric first appeared in late 2024 and has become the company's lead growth story, now exceeding $125 million per quarter with a $600 million full-year 2026 target. |
| Macro-driven delays in client decision-making | persisted | Q1 2025, Q2 2025, Q4 2025, Q1 2026 | Caution around discretionary spend and delayed decisions recurs across the window; in Q1 2026 it drove a cut to the full-year outlook, with North America and travel/consumer called out. |
| NEORIS acquisition and its large Mexico client | persisted | Q3 2024, Q4 2024, Q1 2025, Q3 2025, Q4 2025, Q1 2026 | First raised with the acquisition in Q3 2024, the lead NEORIS client has been a recurring topic; by Q1 2026 management describes it as stabilized with only modest further decline expected. |
| Ukraine delivery continuity as a standing guidance assumption | persisted | Q2 2023, Q3 2023, Q4 2023, Q4 2024, Q4 2025, Q1 2026 | Guidance continues to assume Ukraine delivery centers operate at productivity levels similar to the prior year; the assumption is restated each call even as prominence has faded. |
| New AI commercial models — tokenomics and vendor consolidation | emerged | Q4 2025, Q1 2026 | Non-T&M large deals, AI-enabled vendor consolidation and token economics enter the discussion as AI programs scale into deployment, a genuinely new commercial construct for the services model. |
| Demand shortfall and recovery-timing / stabilization | dropped | Q2 2023, Q3 2023, Q4 2023 | The 2023 narrative centered on a demand shortfall, cost-optimization pressure and when growth would stabilize; that framing faded once organic growth resumed and AI-native became the focus. |
Guidance ledger
Quotes, calls, and speakers are source-verified; outcomes are curator-classified.
| Verbatim guidance | Call | Speaker | Curator outcome | Outcome note |
|---|---|---|---|---|
| “Revenue growth will be in the range of 10% to 14%, with an inorganic contribution of approximately 10% for 2025.” | EPAM Systems, Inc., Q4 2024 Earnings Call, Feb 20, 2025 · 2025-02-20T13:00:00 | Jason Peterson | kept | Full-year 2025 revenue grew 15.4% on a reported basis; the guide was raised to 13%-15% by Q2 2025 and the year finished above the initial range. |
| “it's to exit the year at, let's say, 77% or maybe a little above” | EPAM Systems, Inc., Q2 2025 Earnings Call, Aug 07, 2025 · 2025-08-07T12:00:00 | Jason Peterson | missed | Q4 2025 utilization was 75.4%, below the ~77% exit-rate target set for the year. |
| “Revenue growth will be in the range of 4.5% to 7.5%.” | EPAM Systems, Inc., Q4 2025 Earnings Call, Feb 19, 2026 · 2026-02-19T13:00:00 | Jason Peterson | pending | Initial 2026 outlook; lowered to 4%-6.5% one quarter later on macro, energy-price and Middle East uncertainty. |
| “expect to scale these revenues in excess of $600 million in 2026” | EPAM Systems, Inc., Q4 2025 Earnings Call, Feb 19, 2026 · 2026-02-19T13:00:00 | Balazs Fejes | pending | Reaffirmed in Q1 2026, with AI-native revenue above $125 million in Q1 and management citing a strong line of sight to the target. |
| “Revenue growth will now be in the range of 4% to 6.5%.” | EPAM Systems, Inc., Q1 2026 Earnings Call, May 07, 2026 · 2026-05-07T12:00:00 | Jason Peterson | pending | Current full-year 2026 outlook, weighted toward a second-half ramp in large, risk-adjusted deals. |
Q&A pressure map
Question counts and firms are curator tallies; analyst coverage shown above.
| Topic | Questions | Firms | Pressure / response |
|---|---|---|---|
| Second-half visibility and the lowered 2026 guide | 6 | TD Cowen, Research Division, William Blair & Company L.L.C., Research Division, Wells Fargo Securities, LLC, Research Division, Stifel, Nicolaus & Company, Incorporated, Research Division, Truist Securities, Inc., Research Division | The most pressed topic on the call. Management repeatedly tied the back half to large-deal wins and a stable macro; one question on why existing-client visibility fell short was answered largely by pointing to the Middle East rather than the internal forecasting gap. |
| Outsized non-T&M vendor-consolidation deals | 4 | Wells Fargo Securities, LLC, Research Division, Susquehanna Financial Group, LLLP, Research Division, Guggenheim Securities, LLC, Research Division, Goldman Sachs Group, Inc., Research Division | Analysts probed the count, deal profile, and EPAM's ability to close and execute at that scale; management said the pipeline is risk-adjusted and only partly reflected in guidance. |
| Margin and profitability trajectory | 3 | William Blair & Company L.L.C., Research Division, Susquehanna Financial Group, LLLP, Research Division, Morgan Stanley, Research Division | Questions on bridging Q1's 14.3% non-GAAP operating margin to the full-year 15%-16% target and on margins as large deals ramp; management pointed to seasonality, cost optimization and year-over-year gross-margin gains. |
| AI tokenomics and pricing / commercial models | 2 | Citigroup Inc., Research Division, Morgan Stanley, Research Division | Analysts asked how token costs and new commercial models affect revenue recognition and margins; management said clients currently bear token costs and the model is still evolving. |
Language shifts
Only language evidence verified against the referenced component is shown.
| Observation | Verbatim evidence | Call ID | Component |
|---|---|---|---|
| A more cautious macro framing than the prior quarter, flagged explicitly by management. | “there's a more macro uncertainty today compared to 90 days ago” | 1993788992 | 2 |
| First time the Middle East is named as a specific driver of client decision delays. | “we are seeing the ongoing uncertainty in the Middle East begin to have an impact on client decision-making” | 1993788992 | 3 |
| New commercial vocabulary — 'tokenomics' enters the lexicon as AI programs scale into deployment. | “tokenomics and implication for our engagement is becoming more significant” | 1993788992 | 2 |
| Retained pricing confidence as a counterpoint to the softer demand tone. | “we are actually not seeing what we call rate compression at this point of time” | 1993788992 | 46 |
The call history frames Q1 2026 as a step-down in near-term visibility layered onto a genuine AI-native inflection: management cut the full-year outlook on macro and delayed decisions while pointing to an unusually large, still-unproven pipeline of non-T&M deals to carry the second half. The investment debate now turns on whether that pipeline converts on schedule, given a track record of guidance being raised through 2025 but cut early in 2026.
EPAM Systems: a fallen compounder
EPAM is a debt-free, founder-built digital-engineering firm that compounded revenue from $1.2 billion in 2016 to $5.5 billion in 2025 [1], then watched its shares fall roughly 88% from a late-2021 peak as growth stalled and the market began pricing in AI disruption. At about $86 it trades near 13 times trailing earnings and close to seven times 2026 consensus, carries net cash, and yields more than 13% on free cash flow. This report asks whether that is a trough or a decline.
What EPAM does
EPAM sells the work of software engineers. It describes itself as "a leading global provider of digital engineering, cloud and artificial intelligence-enabled transformation services" — it builds custom software, modernizes legacy platforms, and runs large product-engineering programs for global enterprises [2]. The economic model is straightforward: it hires skilled engineers in lower-cost locations, bills clients for their time at a markup, and keeps the spread. At the end of the first quarter of 2026 it employed more than 56,500 delivery professionals and over 62,750 people in total [3]. Capital intensity is minimal — capital expenditure ran $42 million in 2025, under 1% of revenue — so the business is really a payroll wrapped in client relationships, and its value turns on how many engineers it can keep billable and at what rate.
The company was founded in 1993, listed on the NYSE in 2012, and joined the S&P 500 in 2021 [4]. Its distinguishing feature for two decades was where those engineers sat: EPAM's largest delivery locations were historically Ukraine, Belarus, and Russia [5]. That Central and Eastern European talent base was a genuine cost-and-quality edge — and, after February 2022, the delivery base disrupted by the war in Ukraine, which the company has spent four years rebuilding across new geographies.
From hypergrowth to a stall
For six years EPAM was one of the fastest-growing large IT-services firms in the world, roughly quadrupling revenue between 2016 and 2022. Then growth stopped. Revenue slipped from $4.82 billion in 2022 to $4.69 billion in 2023, was flat in 2024, and returned to growth only in 2025 — the $5.46 billion that year owing partly to acquisitions rather than organic demand [6].
Source: derived from reported financials; FY2025 figure per FY2025 Form 10-K, Consolidated Statements of Income [7].
Profitability tells the sharper story. GAAP operating margin peaked at 14.4% in 2021 and has fallen every full year since, to 9.5% in 2025 [8]. Part of that is acquisition amortization and the cost of carrying idle capacity through the demand air-pocket; utilization ran 77% in early 2026, held down by a deliberate intake of junior staff [9]. The result is a company earning less profit in 2025 ($378 million) than in 2021 ($482 million) on 45% more revenue.
Source: derived from reported financials; FY2025 per FY2025 Form 10-K, Consolidated Statements of Income [10].
The share price
The stock told the story before the income statement did. EPAM closed at $668 at the end of 2021, having touched roughly $717 that November. It has fallen in each of the four calendar years since, and then dropped by more than half again in the first half of 2026 to about $86 — a decline of roughly 88% from the peak.
Source: daily closing prices, market data as reported; 2026 point is the 13 July close.
Two forces sit behind the fall. The first is the war: EPAM entered 2022 with its biggest talent pools inside the conflict zone, exited Russia, and rebuilt delivery across new geographies — as of end-2024 it still had roughly 13,950 personnel in Ukraine and Belarus [11]. The second, and now dominant, force is artificial intelligence. Management states the risk plainly in its own filing: "If comparable services can be performed less expensively using AI, clients may seek other service providers or expect price concessions" [12]. A business that bills for engineer-hours faces an obvious question when the tools it sells can write code, and the shares now trade at about seven times forward earnings.
A balance sheet that removes the worst outcome
Whatever the demand debate, EPAM is not a solvency story. It carries no meaningful borrowings — long-term debt is about $25 million of finance leases against $1.3 billion of cash at year-end 2025, and stockholders' equity of $3.7 billion [13]. Free cash flow was $613 million in 2025 and has been positive and growing for a decade, with earnings converting to cash at more than 150% [14].
Cash (year-end 2025, $M)
Shareholders' Equity ($M)
Free Cash Flow 2025 ($M)
FCF Yield (on market cap)
Source: cash and equity per FY2025 Form 10-K, Consolidated Balance Sheets [15]; FCF derived from reported cash-flow statements; yield computed on a ~$4.5 billion market capitalization.
That matters for how the rest of the report is framed. For a value investor whose first exclusion is companies that could go bankrupt, the net-cash position takes ruin off the table: the debate here is about the trajectory of a profitable business, not its survival. The company has also been returning cash aggressively — roughly $1.5 billion repurchased since the buyback program began, including 1.8 million shares in the first quarter of 2026 [16]. The counter-fact worth carrying forward: those first-quarter buybacks were done at an average price of $143.84, well above where the shares now sit [17] — a reminder that even insiders did not call this bottom.
What the price implies
At roughly $86 and about 52.4 million shares outstanding [18], the equity is worth about $4.5 billion. Net of cash, the market values the operating business at roughly $3.3 billion — around six times 2025 operating income of $520 million [19]. On earnings, the shares trade near 13 times trailing GAAP EPS of $6.72 and close to seven times the roughly $13 that consensus expects on a non-GAAP basis in 2026.
P/E (trailing GAAP)
P/E (2026 consensus, non-GAAP)
EV / Operating Income
Consensus Target ($)
Source: valuation derived from reported financials [20] and shares outstanding per the 2026 proxy [21]; forward EPS and $139 mean target are consensus estimates.
Those are not the multiples of a growing IT-services franchise; they are the multiples the market assigns to businesses it expects to shrink. The gap between the $86 price and the $139 mean analyst target is the visible form of the disagreement — but a value buyer should treat the low multiple as a hypothesis to test, not a bargain to assume. The price is cheap only if the earnings behind it hold.
The question this report answers
EPAM is a debt-free, cash-generative digital-engineering business, still led at the board level by its founder Arkadiy Dobkin — now Executive Chairman after handing the CEO role to Balazs Fejes in 2025 [22] — whose shares have fallen ~88% while the business kept generating cash. The report exists to judge whether EPAM's growth stall is a cyclical trough set to re-rate, or the early stage of an AI-driven structural decline that the current ~7x forward-earnings price is right to anticipate — and whether the balance sheet and free cash flow offer a value buyer a genuine margin of safety while that resolves.
The evidence so far points to a business that is impaired, not broken: it still grows, still converts earnings to cash, and cannot go bankrupt. The strongest fact against that read is management's own admission that AI could make its core service cheaper to deliver — and its most recent guidance, cut in early 2026 as clients "modestly delay decisions," shows the demand pressure is live, not past [23]. What would change the read is evidence on two fronts the later chapters take up: whether AI is expanding EPAM's addressable work or compressing its billable hours, and whether organic growth re-accelerates once the current decision-deferral clears. Everything that follows connects back to that question.
AI and Billable Hours
EPAM sells senior engineering hours, so generative AI is the factor that separates the two readings of its stall: a tool that compresses billable hours and invites price concessions, or a wave that enlarges the software its clients build. Through mid-2026 the labor model is still expanding — about 56,600 delivery professionals and utilization near 77% — even as EPAM's own filings escalated AI from an execution risk to a demand risk it says has hurt its stock.
Why the model is exposed to AI at all
EPAM's economics are simple to state and that is exactly why AI matters. The company employs people, trains them, staffs them onto client projects, and bills for their time; salaries of delivery professionals are booked as cost of revenue whether or not those people are on a billable project at a given moment [1]. Revenue is, to a first approximation, headcount times utilization times a billing rate. Any technology that changes how many hours a piece of software takes to build, or what a client will pay per hour, lands directly on that identity.
That cuts two ways, and both are real. If a coding assistant lets a smaller team ship the same system, a fixed-scope program needs fewer billed hours, and clients may — in EPAM's own words — "seek other service providers or expect price concessions" once comparable work can be done less expensively [2]. If instead cheaper software means clients commission more of it, the pie grows and an engineering-led vendor captures more work. The case is most sensitive to which force dominates, and it is not yet settled by the numbers.
Management's language escalated, on the record
The most concrete evidence that this is a live risk is that EPAM's own risk disclosure changed. The escalation is datable across three consecutive 10-Ks.
Source: EPAM FY2023 10-K [3]; FY2024 10-K [4]; FY2025 10-K [5].
In the FY2023 filing, the AI risk was mostly about EPAM keeping up: if it were "slow to develop, adopt, and deploy generative AI technologies," its competitiveness against peers would suffer [6]. By the FY2025 filing, EPAM had added a distinct risk factor titled "Increased Adoption of AI-Based Software Tools May Reduce Demand for Our Services," warning that clients could "develop, customize, and maintain software solutions internally," or "replace traditional software with agentic AI, rather than purchasing our services" [7]. The same page contains the most direct admission in the file: "Increased competition, or the perception of increased competition, from new and non-traditional market participants like AI-based task-specific tools, has negatively impacted the price of our stock" [8]. Management is not disputing that AI sits behind the de-rating; it is confirming it.
What the filing labels as an AI risk still shows a cyclical demand pattern underneath. EPAM's FY2025 10-K now names AI as a risk that 'may reduce demand for our services' and 'negatively impacted the price of our stock', but the stall it points to had a cyclical shape — Business Information & Media fell 10.5% and Consumer, Retail & Travel 5.6% in FY2024 while Life Sciences grew 17.3% — and the only vertical behaving as AI substitution predicts, Software & Hi-Tech, is EPAM's once-largest and now among its softest at ~15% of FY2025 revenue. That vertical breakdown is developed in [Demand Mix].
The original stall was macro, not AI
It matters that the two shocks arrived in a specific order, because it bears on whether the damage is structural. EPAM's revenue growth broke well before AI displacement was a commercial force. Revenue fell 2.8% in 2023 and grew 0.8% in 2024, after +28% in 2022.
Source: derived from reported financials, EPAM FY2021–FY2025 10-Ks; consolidated statements of operations [9].
The June 2023 outlook cut names the cause plainly. EPAM reduced its Q2 and full-year guidance because clients "become even more cautious with spending specifically in the 'build' segment," with "pipeline conversions occurring at slower rates than previously assumed" [10]. The FY2025 10-K reaches the same conclusion looking back: growth "significantly slowed at times, particularly during 2023 and the first half of 2024, due to reduced client demand resulting primarily from uncertain macroeconomic conditions" [11]. The first leg of the stall, then, was a cyclical pullback in discretionary IT spend. The AI-displacement worry is the newer, additive overhang layered on top of a business that was already growing slowly — which is why untangling the two is the analytical task, not a footnote.
What the operating numbers show so far
If AI were already gutting billable demand, the plainest tell would be a shrinking, less-utilized delivery force. So far the opposite is visible: EPAM has kept adding engineers and kept them busy.
Delivery Professionals (FY2025)
Utilization (FY2025)
Top Clients on GenAI (Q4 2024)
Sources: FY2025 10-K, human-capital disclosure [12]; Q4 2024 earnings call [13].
Delivery professionals rose from about 47,350 at the end of 2023 to 55,100 in 2024 and 56,600 in 2025; utilization of that force improved from 74.3% to 76.7% to 76.8% over the same years [14]. Into the latest reported quarter, Q1 2026, the headcount held at more than 56,500 delivery professionals with utilization at 77% [15].
Source: derived from reported financials and human-capital disclosure, FY2025 10-K [16].
The revenue-per-professional column looks alarming for 2024, but that dip is an artifact, not a signal: EPAM closed the NEORIS and First Derivative acquisitions late in 2024, adding "nearly 6,000 people combined" to the year-end count while those staff contributed almost no 2024 revenue [17]. Normalized in 2025, revenue per delivery professional recovered to roughly $96,000. There is no evidence in these lines of AI silently hollowing out billed hours — at least not yet.
The AI-linked revenue itself is real but small and, tellingly, still unquantified. Management says 75% of its top clients are engaged on GenAI initiatives [18] and that AI-native services are growing "double digits" sequentially, but the CFO conceded it is "somewhat challenging to quantify precisely" [19]. On economics, CEO Balazs Fejes was measured: AI projects are "not fundamentally different from non-AI projects," and profitability is "currently similar to non-AI," with only the prospect of "higher profitability in the future" [20]. The upside case is a hope with a pilot behind it, not yet a margin in the accounts.
The bull mechanism management leans on
EPAM's answer to the displacement fear is a specific claim: cheaper software leads to more software, and AI pushes clients toward custom builds rather than off-the-shelf products. Fejes argues that "as functional capabilities improve, we anticipate a greater inclination to build rather than buy" [21]. Through 2024 and 2025 the company recast itself around this thesis — an "AI-native" delivery model it brands "Delivery-as-Code" [22], built on proprietary frameworks (DIAL, EliteA, and an AI/Run stack) meant to let clients run larger transformation programs with EPAM's engineering at the core [23]. Coming out of the trough, organic constant-currency growth did re-accelerate, from about 1.4% in Q1 2025 toward a mid-single-digit pace later in the year [24]. That is consistent with a cyclical recovery beginning — but it is modest, and the 2025 headline growth of 15% was inflated by acquisitions and currency, not organic demand.
The industry is testing the same question
This is not an EPAM-specific experiment; the entire IT-services sector is running it, and peer commentary shows both mechanisms operating at once. On the efficiency side, Cognizant reports that roughly 30% of its internal code was already AI-generated in a recent quarter and expects "it could reach 50% in the years ahead" — a direct measure of how fast machine-written code is displacing hand-written hours [25]. Infosys frames the current cycle around clients prioritizing "cost reduction and operational efficiency," which is "driving vendor consolidation" [26]. Both point at pricing pressure.
On the other side, Grid Dynamics — a smaller engineering-led peer closer to EPAM's model — reports the pie-expansion effect directly: because "the cost of development [is] getting reduced" by AI, it sees "increased demand for our custom-built software," and it is pursuing "enhanced pricing with our AI offering" rather than discounting [27], [28]. The honest reading of the peer set is that the net effect is genuinely undecided across the industry — which is why no single filing settles it for EPAM.
What would decide it, and what to watch
The evidence available today leans against the hard structural-decline case: through mid-2026 EPAM's delivery force is larger and more fully utilized than before generative AI, AI-native work is growing rather than cannibalizing, and the sharpest part of the stall traces to a macro spending pause that predates AI displacement. The strongest fact against that read sits in EPAM's own 10-K — the company itself now warns that AI adoption "may reduce demand for our services" and concedes it has weighed on the stock [29], and the effect is early enough that the operating metrics have not yet had to reveal it.
What would move the read is measurable and near-term. Revenue per delivery professional is the cleanest signal: if it falls on organic, acquisition-adjusted numbers while utilization stays high, that is price and hour compression showing through. A second is whether AI-native revenue becomes a disclosed, growing line rather than a "double digits, hard to quantify" aside [30]. A third is the character of the current softness: in Q1 2026 management again blamed macro — clients "modestly delay decisions" amid "higher energy prices and global economic uncertainty" — and cut full-year organic constant-currency growth to a 2.5% to 5% range [31]. If deferred deals convert in the second half as promised, the cyclical reading holds; if they quietly disappear, the case that AI is shrinking the addressable work gets harder to dismiss.
Engineering Premium
EPAM's edge was never a patent or a network. It was a reputation for the hardest engineering, staffed from a scarce, low-attrition talent pool — and for a decade it showed up as revenue growth two to three times the scale incumbents' at comparable margins. That growth premium has now closed: organic growth runs slightly below Accenture's and Cognizant's, and reported operating margin sits beneath both. What remains is genuine client stickiness — being tested on price and mix, not yet on retention.
In a labor-based services business there is no moat you can point to on a balance sheet. The tell is indirect: clients choosing a more expensive provider, and paying for that choice in the vendor's growth rate and pricing. On that test EPAM was, for years, the clearest case in its cohort. Read at the competitive level, this is the report's cyclical-versus-structural read again: the evidence below weighs whether the premium is dormant or spent.
The premium showed up as growth
For six years through 2022, EPAM compounded revenue at 25% to 41% a year — 28.4% in 2022 alone, to $4.825 billion — while the scale IT-services incumbents grew in the low-to-mid single digits [1]. That gap is the visible fingerprint of an edge: enterprises routed their most demanding build work to EPAM and let it grow into their budgets.
Source: derived from reported financials, FY2017–FY2025 10-Ks; FY2022 growth per FY2022 10-K MD&A [2].
The 2025 figure needs a caveat. Reported growth of 15.4% was lifted by the late-2024 NEORIS and First Derivative acquisitions; on an organic constant-currency basis, revenue rose 4.9% [3]. Over the same year Accenture's revenue grew 7.4% and Cognizant's 7.0%. On the cleanest available measure, EPAM is now growing marginally slower than the two incumbents it historically outpaced. Management's 2026 guidance of 3% to 6% organic constant-currency growth keeps it in that same band [4].
What built the edge: scarce talent, embedded clients
The premium rested on two things a competitor cannot quickly copy: the quality of the delivery pool and the depth of the client relationships.
The talent signal is retention. EPAM's voluntary attrition was 8.5% in 2025, 8.9% in 2024 and 8.6% in 2023 [5]. Cognizant, whose model leans on a much larger India base, ran 15.9% in 2024 and 13.8% in 2023 [6]. A workforce that turns over at half the peer rate keeps institutional knowledge inside client accounts and lowers the cost of staffing complex work — the operational core of the reputation.
That reputation converts into rate. EPAM earned roughly $87,000 of revenue per employee in 2025 (5,457 million dollars across about 62,850 people) [7] against about $59,000 at Cognizant, whose roughly 336,800 staff generated $19.7 billion [8]. Geographic mix explains part of the gap, but the direction is the point: EPAM sells scarcer, higher-value hours.
Voluntary Attrition (2025)
Revenue / Employee
Revenue Below Top-20 Clients
Sources: attrition and headcount, FY2025 10-K [9] [10]; client concentration, FY2025 10-K MD&A [11].
The second pillar is how diversified and embedded the client base is. EPAM's top five clients were 13.7% of revenue in 2025, the top twenty 31.9%, and everything below the top twenty 68.1% [12]. For a firm this size that is unusually low concentration, and it has kept falling as the base broadens.
Source: FY2025 10-K MD&A, Revenues by Client Concentration (2023–2025) [13].
The mechanism behind the falling concentration is land-and-expand still working. In the fourth quarter of 2025, revenue from clients outside the top twenty grew 15.5% year over year while the top-twenty accounts grew 7.3% [14]. New and smaller relationships are compounding faster than the anchor accounts — the opposite of a franchise losing its pull with customers.
Where the premium has narrowed
Three lines of evidence show the edge being priced, not abandoned.
First, pricing power. In 2025 EPAM's cost of revenues rose to 71.2% of sales from 69.3%, and management's own explanation was blunt: the increase was "primarily due to compensation increases which we were not able to fully offset through pricing increases" [15]. A firm with unassailable rate power passes wage inflation through; EPAM could not fully do so, and gross margin absorbed the difference.
Second, the margin gap to the scale peers. On reported figures EPAM's 2025 operating margin was 9.5%, against roughly 15.6% at Accenture and 16.1% at Cognizant. Much of that gap is the intangible-amortization drag from the 2024 acquisitions, examined in Earnings Quality: on the adjusted basis management guides to, EPAM's operating margin was 15.2% [16]. The honest read is that EPAM's margin premium over the incumbents has closed to rough parity, not that it has inverted.
Sources: EPAM GAAP and adjusted operating margin, Q4 FY2025 earnings call [17]; Globant, Accenture and Cognizant operating margins derived from reported financials, latest fiscal year.
Third, the delivery base is drifting toward the same geography as the low-cost incumbents. India is now EPAM's single largest delivery location, at roughly 12,200 professionals, ahead of Ukraine (8,750), Poland (5,050), Belarus (3,400) and Mexico (2,950) [18]. The Central and Eastern European engineering heritage that once set EPAM apart is being blended, of necessity, with the same India talent pool that Infosys, Cognizant and TCS draw on. EPAM itself frames the field this way, listing competitors from Accenture and Cognizant to Endava, Globant, Grid Dynamics, Infosys and TCS, and naming "price" among the principal competitive factors [19].
What holds, and what would decide it
The distinction that matters is between a moat under pricing pressure and a moat under retention pressure. EPAM's evidence points to the first. Clients are not leaving — attrition of the workforce is low, the client base is broadening, and the long tail is growing faster than the anchors. What has weakened is the ability to convert that loyalty into premium growth and premium price, in a market where the scarce-talent story is diluting and AI reframes what an engineer-hour is worth (the pricing channel traced in AI and Billable Hours).
The strongest fact against a durable-moat read is that the whole pure-play engineering cohort re-rated together — EPAM, Globant and Grid Dynamics — which suggests the market is repricing the engineering-hours premium itself rather than any one firm's execution. Globant, the closest listed comparable, decelerated from 15.3% revenue growth in 2024 to 1.6% in 2025 on the same forces.
What would decide durability is observable and near-term: whether gross margin stabilizes or keeps eroding as wage costs outrun pricing; whether organic growth re-accelerates back above the incumbents as deferred programs convert; and whether revenue per delivery professional holds as the India mix rises. Retention metrics turning down — attrition climbing, the client base concentrating, the long tail stalling — would move the read from "premium under pressure" to "moat impaired." None of those has turned yet.
Demand Mix
Where EPAM's revenue comes from — by industry and by region — carries the clearest demand-side read on whether the 2022–24 stall was cyclical or the early stage of an AI-driven structural decline. EPAM's FY2025 10-K now names AI as a risk that 'may reduce demand for our services' and 'negatively impacted the price of our stock', but the stall it points to had a cyclical shape — Business Information & Media fell 10.5% and Consumer, Retail & Travel 5.6% in FY2024 while Life Sciences grew 17.3% — and the only vertical behaving as AI substitution predicts, Software & Hi-Tech, is EPAM's once-largest and now among its softest at ~15% of FY2025 revenue.[1][2] The counter sits inside EPAM's own delivery base: aggregate delivery headcount rose to about 56,600 and utilization to roughly 77% over the same window [3], the opposite of a demand hollow-out.
EPAM sells into six industry verticals, none larger than about a quarter of revenue, with roughly 42% of sales run out of Europe. The sections below read that mix vertical by vertical and region by region; the 2025 recovery that runs through it is real but modest, and flattered by acquisitions.
The stall had a shape
The 2024 flat year makes the shape plain. Total 2024 revenue rose 0.8% over 2023, but that near-zero average hid a wide dispersion. Financial Services, Life Sciences & Healthcare and Emerging Verticals grew; Consumer Goods, Retail & Travel, Business Information & Media and Software & Hi-Tech all declined [4]. The contraction landed hardest on the most discretionary, project-based work — Business Information & Media fell 10.5% and Consumer, Retail & Travel fell 5.6% — while the more defensive Life Sciences book grew 17.3% [5].
Source: derived from reported revenues by vertical, FY2023–FY2025 10-Ks [6]; "stall" is FY2024 over FY2023, "recovery" is FY2025 over FY2024.
That signature reads more like a discretionary-spending pullback than a broad erosion. An AI-substitution shock — clients replacing bought engineering with their own models — would be expected to press on software-heavy engagements across the book at once. This pressed where budgets flex. It is also consistent with how management framed the original downgrade: in June 2023 EPAM cut its outlook citing "continued uncertainty in the demand environment," a macro signal, not a technology one [7].
The tell that cuts the other way is Software & Hi-Tech. These clients — technology companies themselves — are the ones best placed to build with AI internally and cut outside engineering, and this was once EPAM's single largest vertical. It has since been among its softest: roughly flat in both 2023 and 2024, drifting to 15.1% of revenue [8]. Its 2025 rebound of 17% restored only part of that ground, and left it no longer the anchor vertical it once was [9].
At roughly 15.1% of the $5,457.1m FY2025 top line — about $820m — Software & Hi-Tech is large enough to move the read [10]. The single checkable test that would flip the read from cyclical to structural is whether that vertical and the other discretionary books resume organic growth into the second half of 2026 on their own clients, rather than on acquired NEORIS and First Derivative revenue or a weaker dollar. If AI displacement surfaces in the demand data before it surfaces anywhere else, the technology vertical is where it would show first.
A diversified book, no single end-market
EPAM assigns clients to five named verticals plus a catch-all "Emerging Verticals" that spans energy, utilities, manufacturing, automotive and telecom. In 2025 the largest, Financial Services, was 24.1% of the $5.46 billion top line; the smallest named vertical, Life Sciences & Healthcare, was 11.5% [11]. That spread matters: no client industry can sink the business on its own, and Financial Services only became the largest vertical in 2024, overtaking a Consumer book that had led for years [12].
Largest Vertical — Financial Services ($M)
Largest Vertical, % of Revenue
Source: FY2025 Annual Report (Form 10-K), Note 13 — Disaggregation of Revenues [13].
The recovery, read on the organic line
The 2025 headline looks like a clean return to growth; the organic line is more sober. Reported revenue rose 15.4%, but on an organic constant-currency basis growth was 4.9% [14]. The gap is the two 2024 acquisitions — NEORIS and First Derivative — plus a weaker dollar. Those deals did most of the vertical heavy-lifting: Financial Services grew 28.7% and Emerging Verticals 26.9% in 2025, but management attributes both largely to acquired clients — insurance and payment processing in Financial Services, energy and telecom in Emerging [15].
Source: Q4 2025 earnings call, CFO remarks [16].
Underneath, the demand trend genuinely improved. By the third quarter of 2025 organic constant-currency growth reached 7.1%, EPAM's fourth consecutive quarter of positive organic growth [17], and management entered 2026 pointing to "healthy client sentiment, a solid pipeline" and relative stability in client budgets [18]. But the recovery is modest and slowing on the margin: 2026 organic growth is guided to 3–6%, roughly a point of which is one large NEORIS client in Mexico winding down under tariff pressure [19]. That is a return to growth, not a return to the double-digit organic cadence EPAM ran before the stall.
Persistent tech-vertical softness through an otherwise-recovering macro would be the clearest demand-side signal that the erosion is structural rather than cyclical.
More European than the peer group
EPAM's regional mix is a demand exposure in its own right, and a distinctive one. Its Europe segment was 42.0% of revenue in 2025, up from 39.4% a year earlier, with the Americas the remaining 58.0% [20]. That leans far more toward Europe than the India-centric majors, whose revenue skews heavily to North America — so EPAM's growth is more geared to European corporate budgets, and to the euro and pound, than a peer screen would suggest.
Source: FY2025 Annual Report (Form 10-K), Note 13 — Disaggregation of Revenues [21]; FY2023 excludes a residual $16.1M Russia segment.
In 2025 that tilt helped: Europe grew 23.1% reported, 19.7% in constant currency, outrunning the Americas' 10.5% [22]. But here too the reported figure overstates underlying demand — the UK-based First Derivative acquisition and a stronger euro did much of the work — and a concentration that flatters in a soft-dollar year is the same concentration that would hurt if European budgets tighten or the currency reverses. The Americas share of revenue has, in fact, been drifting down, from 60.6% to 58.0% in a single year [23], which is why management is now redirecting go-to-market investment back toward North America.
The demand data leaves one standing test: whether Software & Hi-Tech — the vertical most able to internalize AI, once EPAM's largest and still among its softest on an organic basis — and the other discretionary books resume organic growth into the back half of 2026 on their own clients rather than on acquired revenue or currency. That is what would separate a cyclical trough from structural erosion.
Delivery Footprint
EPAM entered 2022 with more than half of its delivery staff in Ukraine, Belarus and Russia. The invasion forced a full exit from Russia and a relocation of the base: the war-zone share of delivery professionals fell from 58% to 21% by the end of 2025, with India now the largest single location. The direct financial hit was contained — roughly $42 million of one-time charges against $4.8 billion of revenue — but the higher-cost rebuilt footprint sits inside the gross-margin erosion, and about 12,000 people still work in a live conflict zone.
Where a company's engineers physically sit is not usually a first-order investment question. For EPAM it is. The firm was built on a single, unusual delivery base — Central and Eastern Europe rather than India — and in February 2022 that base became the front line of a war. How EPAM absorbed that shock, what it cost, and what the rebuilt footprint means for margins and risk is a distinct thread from the demand debate (AI and Billable Hours) and the moat (Engineering Premium), and it is the most company-specific fact in the case.
A base concentrated in three countries
At the end of 2021 EPAM employed 52,617 delivery professionals. Its three largest delivery locations were Ukraine (12,389), Belarus (9,416) and Russia (8,933) — 30,738 people, or 58% of the delivery base, concentrated in three countries that shared a border and, within months, a war [1]. India, by contrast, held 4,349 and Poland 3,055 [2]. The company's own risk disclosure put it plainly: more than half of its global delivery, administrative and support personnel were located in Ukraine, Belarus and Russia [3].
That concentration was a feature, not an accident. It supplied the deep engineering talent, established technical education and government tax incentives that underwrote EPAM's premium — the same premium the moat chapter traces (Engineering Premium) — at a labor cost below Western Europe and the United States [4]. It also concentrated the firm's operating risk in a region its filings had long flagged for political and economic instability [5].
Delivery in Ukraine/Belarus/Russia (2021)
In Ukraine/Belarus (2025)
India Delivery Staff (now #1)
One-Time 2022 Exit Charges ($M)
Sources: delivery-staff mix from FY2021 [6] and FY2025 10-Ks [7]; exit charges from the FY2022 10-K, Note 2 [8].
The 2022 shock, and what it actually cost
EPAM's response was fast and total on the Russia side. On 4 March 2022 it announced it would discontinue services to customers in Russia; on 7 April it began a phased exit of Russian operations; and on 7 September it signed an agreement to sell substantially all its remaining Russian holdings [9]. The accounting consequences landed in 2022 but were modest against the size of the company: asset impairments of $15.1 million (property and equipment), $3.8 million (leases) and $0.7 million (goodwill); $5.1 million of bad-debt expense on Russian receivables; and $17.1 million of employee-separation costs — roughly $42 million in total one-time charges [10]. Alongside, EPAM committed $100 million in humanitarian aid to its people in Ukraine [11].
The lost Russian business was the larger line. Revenue from customers in the CEE geography — mostly Russia — fell $88.8 million, or 52.9%, in 2022, with Russian customers alone accounting for a $90.4 million decline [12]. The Russia reporting segment swung from a $32.5 million operating profit in 2021 to a $13.5 million operating loss in 2022, and shrank from 4.4% of segment revenue to 1.5% on its way to zero [13].
Revenue grew even through the exit. As it wound down Russia and relocated tens of thousands of people out of a war zone, EPAM still grew total 2022 revenue about 28% to $4.82 billion [14]. The growth stall came a year later, in 2023, and the demand chapter attributes it to macro conditions, not the war (AI and Billable Hours). On the evidence, the invasion was a contained, largely one-time shock to a still-growing business — an execution credit for management — rather than the origin of the current slowdown.
Rebuilding the map
The harder task was rebuilding the delivery base. Through 2023 EPAM sustained hiring across Central and Eastern Europe, Central and Western Asia, India and Latin America, and by the end of that year employed delivery professionals in more than 50 countries [15]. The total delivery headcount actually contracted first — from 52,617 in 2021 to about 47,350 by the end of 2023 — as the Russia exit and the 2023 demand slump both bit, before recovering to roughly 56,600 by the end of 2025 [16] [17].
By the end of 2025 the geography had inverted. India was the largest single delivery location at about 12,200 professionals, having added roughly 2,150 during the year; Ukraine held about 8,750 (essentially flat on 2024's 8,764); Poland 5,050; Belarus 3,400; and Mexico 2,950 — with Russia at zero [18]. Management now describes four delivery hubs — Europe, India, Latin America and Western Central Asia — where it had effectively one region before [19].
Source: delivery-staff counts by location, FY2021 10-K [20] and FY2025 10-K [21].
The combined Ukraine-Belarus-Russia share of delivery staff fell from 58% in 2021 to about 21% in 2025, while India rose from 8% to 22%. Central and Eastern Europe remains, in management's words, a "cornerstone" that anchors long-tenured clients, and Ukrainian headcount has stabilized — Q4 2024 marked the first sequential net additions there since the invasion began [22] [23]. The result is a more diversified base than the one that existed in 2021, a durability improvement the war forced rather than one management chose.
What the rebuild left behind
Two residuals matter for the investment case. The first is cost. As early as the Q4 2022 call, an analyst pressed management on exactly this — that "the average cost of delivery has gone up" and asked whether the old Eastern-European cost edge was gone; the CEO's answer pointed to India and Latin America as the fastest-growing, and higher-cost-to-establish, locations [24]. The mechanism shows up in the gross margin: it has fallen from 33.9% in 2021 to 28.8% in 2025, roughly five points, as the base shifted toward higher-cost geographies and relocated Ukrainian staff while the Belarusian and Russian tax-incentivized cost pools shrank.
Source: derived from reported financials, FY2021–FY2025 10-Ks (revenue and cost of revenues).
The footprint is one contributor to that erosion, not the whole story — wage inflation the company could not fully offset through pricing is the other, as the moat and earnings-quality chapters set out (Engineering Premium, Earnings Quality). But the direction is unambiguous: the delivery base that survived the war is structurally more expensive to run than the one that entered it, and it competes on more of the same offshore geography as Cognizant, Infosys and TCS than the old CEE-only model did.
The second residual is a live tail. About 12,000 delivery, administrative and support personnel still work in Ukraine and Belarus — roughly 12,600 at end-2023 and around 12,150 at end-2025 — inside or adjacent to an active war [25] [26]. EPAM owns an office building in Kyiv and leases space in several Ukrainian cities that could be damaged, and its own disclosure warns that any escalation drawing in Belarus's military could jeopardize its people and operations there [27]. This is a lower-probability, higher-severity risk than it was in 2022 — the base is smaller and the firm has proven it can relocate under fire — but it has not gone to zero, and it is not one a peer running an India-and-Latin-America model carries.
The war was a contained one-time shock to a still-growing business, absorbed without breaking the top line. The lasting marks are a structurally higher-cost delivery base — visible in five points of lost gross margin — and about 12,000 people still working in a conflict zone. What would change the read on the tail risk: a material escalation involving Belarus, or a renewed step-down in Ukrainian headcount, would move it from a manageable residual toward a first-order problem.
The footprint story cuts both ways for the central question of whether EPAM is a cyclical trough or a structural decline. It removes the war as an explanation for the current stall — 2022 grew 28% — and it leaves the company more diversified than before. Against that, it is one reason the old cost-and-engineering distinctiveness has narrowed toward peer terms, and it embeds a geopolitical tail that a value buyer must price into the margin of safety rather than assume away.
Capital and Alignment
A margin of safety built on cash is only as good as what management does with it. Since 2023 EPAM has deployed roughly $2.2 billion — about $1.2 billion buying back its own stock and $1.0 billion on 2024 acquisitions. The buybacks have been executed at an average near $200 while the shares now trade around $86, and the deals loaded roughly $1.6 billion of goodwill and intangibles onto an asset-light balance sheet as margins compressed. The people making these calls own about 3.8% of the company.
For most of its listed life EPAM returned nothing to shareholders — it held its cash and grew. That changed in 2023, and the pace and price of the spending since shows how management thinks about value.
From holding cash to spending it
EPAM has never paid a dividend and does not intend to [1]. Through 2022 it also bought back essentially no stock, letting cash accumulate. The Board authorized its first repurchase program — $500 million — in February 2023, a second $500 million in August 2024, and a third for $1.0 billion in October 2025 [2]. Alongside the buybacks, 2024 brought the largest acquisition spend in the company's history.
Sources: buyback cash from FY2025 10-K, Stockholders’ Equity note [3]; acquisition purchase prices from FY2024 10-K, Acquisitions note [4].
The shape matters. Nothing was returned in 2022; 2024 was an acquisition year dominated by two deals; 2025 was a buyback year at record scale. Management has been an active allocator, and what each dollar bought differs by year.
The buybacks bought high
The company repurchased 686 thousand shares for $164.9 million in 2023 [5], 1,854 thousand for $398.0 million in 2024, and 3,538 thousand for $660.6 million in 2025 [6]. Those figures imply average prices of roughly $240, $215 and $187. In the first quarter of 2026 EPAM spent a further $264 million — including a $300 million accelerated repurchase with Morgan Stanley — at an average of $143.84 [7], [8]. Every tranche to date sits well above the ~$86 the stock fetches in mid-July 2026.
Sources: 2023–2025 averages derived from shares and cash in the FY2025 10-K Stockholders’ Equity note [9]; 1Q26 average from the Q1 2026 10-Q issuer-purchases table [10]; July 2026 market price as established in The De-Rating.
In the short run the arithmetic runs against the company. The roughly 6.1 million shares bought across 2023–2025 cost about $1.22 billion; at $86 they are worth about $525 million. Because the shares were retired, that gap never appears as an accounting loss — but the cash is spent, and the same money would buy more than twice as many shares today. On the record so far, the program has been a wealth transfer to exiting holders rather than a bargain for those who stayed.
Two facts cut the other way, and belong in the same breath. First, the buying accelerated as the price fell — $240 in 2023 down to $144 in early 2026 — which is the right direction for a company that believes its stock is cheap. Second, the share base is now genuinely shrinking rather than merely absorbing stock-based-compensation dilution.
Sources: year-end share counts from the FY2025 10-K Statement of Stockholders’ Equity [11]; March 2026 count from the 2026 proxy statement [12].
Issued shares fell about 9% from the end of 2023 to March 2026. Stock-based compensation runs at scale — $135.5 million in 2023, $159.1 million in 2024 and $169.5 million in 2025 [13] — so in 2023 the buyback did little more than mop up new issuance. Only from 2024, and decisively in 2025–26, did repurchases outrun dilution and start compounding per-share value. That timing shows in the numbers: net income fell from $454.5 million in 2024 to $377.7 million in 2025 [14], yet a smaller share count is now supporting per-share earnings, with first-quarter 2026 diluted EPS rising to $1.52 from $1.28 partly on reduced shares outstanding [15].
One nuance sits under the "debt-free" label. To fund the first-quarter 2026 buying, EPAM drew $140 million on its revolving credit facility [16] — small and revolving, but the first time it has leaned on borrowing to repurchase stock.
The 2024 acquisition turn
2024 was the year EPAM spent its cash on other companies. It paid $626.3 million for NEORIS, a 4,800-person advanced-technology consultancy concentrated in Latin America and Spain, and $300.7 million for First Derivative, a Northern Ireland–headquartered managed-services and consulting business for capital markets [17], plus $74.2 million across three smaller deals [18] — roughly $1.0 billion in all.
Almost none of that price bought tangible assets. NEORIS added $406.8 million of goodwill and $259.0 million of intangibles; First Derivative added $170.4 million of goodwill and $124.8 million of intangibles [19]. Company-wide, goodwill reached $1,211 million and intangibles $407 million at the end of 2025 — together about $1.6 billion, or 44% of the $3.68 billion of equity, on a business that carries almost no physical capital [20].
Source: FY2025 10-K, Consolidated Balance Sheets [21].
The strategic logic is coherent — NEORIS extends delivery into Latin America, First Derivative deepens a financial-services vertical [22] — but the timing is awkward. The deals closed just as blended operating margin was compressing (the arc traced in The De-Rating), and consulting and managed-services revenue of the kind these businesses carry tends to dilute the engineering-led margin that is EPAM's differentiator. No impairment has been recorded, so the market is not yet questioning the carrying values; whether the acquired revenue earns its cost of capital is a question the next few years of segment results will answer, not this one.
Who is making these calls
The capital being deployed belongs overwhelmingly to outside institutions, and the people directing it hold comparatively little of it. As of March 2026, all 17 directors and executive officers together owned 3.8% of the company. Founder Arkadiy Dobkin — who moved to Executive Chairman in the 2025 succession — held 2.9%, and thus accounts for most insider ownership on his own. New CEO Balazs Fejes owned 71,722 shares and CFO Jason Peterson 69,931, each well under 1% [23].
Source: 2026 Definitive Proxy Statement, Security Ownership of Certain Beneficial Owners and Management [24]. NEO percentages under 1% are computed on 52.44 million shares.
Two large active managers — Capital World Investors at 12.3% and Invesco at 6.3% — sit alongside the index holders Vanguard (11.8%) and BlackRock (7.0%) [25]. This is a professionally managed, institutionally owned company, not a founder-controlled one. Alignment runs mainly through equity grants rather than large personal stakes: insider transaction records over 2023–2026 are dominated by grants and tax-withholding sales, with no discretionary open-market purchase of size even as the stock fell by more than 80%. For an investor who prizes a founder-operator with meaningful skin in the game, that is a real qualification — the buyback-versus-price judgment is being made by managers whose own wealth is only modestly tied to getting it right.
What this says about the margin of safety
The cash cushion at the center of this report's question is real, but its steward has spent the past three years buying its own shares above today's price and paying full multiples for consulting revenue while margins slipped. That is not recklessness — the balance sheet remains strong, the buyback is now shrinking the base, and the acquisitions may yet pay off — but it is a management team whose timing has cost value so far and whose alignment is modest. The read that would flip is straightforward: sustained repurchases at current prices, no impairment of the 2024 goodwill, and acquired revenue that holds EPAM's margin rather than diluting it would turn a poorly-timed record into a disciplined one. The evidence to date points the other way.
Earnings Quality
EPAM's headline free cash flow is large: $613 million in 2025, more than 1.6 times reported net income, a yield near 13.5% on the equity. Most of that ratio is an artifact. The 2024 acquisitions tripled a non-cash amortization charge that depresses reported earnings, and $177 million of stock compensation is added back to cash. Measured against the earnings management actually guides on, free cash flow converts at about 95%, not 150%. The cash is clean; the owner's yield is nearer 10%.
Two earnings numbers that disagree by 71%
For 2025 EPAM reported GAAP diluted earnings of $6.72 per share and non-GAAP diluted earnings of $11.50 — a gap of $4.78, or 71% [1]. The same split runs through the income statement: GAAP income from operations was $520 million (a 9.5% margin, down 4.5% on the year), while non-GAAP income from operations was $831 million, a 15.2% margin that management reports as up 6.7% [2]. One set of numbers says the business shrank; the other says it grew. The $311 million between them is the subject of this chapter.
GAAP Diluted EPS
Non-GAAP Diluted EPS
Free Cash Flow ($M)
FCF / Adj. Net Income
Source: Q4/FY2025 earnings call, full-year 2025 results [3].
What the conversion ratio is really measuring
The report's opening chapter noted free cash flow converting at more than 150% of net income and a free-cash-flow yield around 13.5% (The De-Rating). Both figures are correct on their face, and both are flattered by the same thing: a GAAP net income denominator that has been pushed down by non-cash charges.
The bridge from GAAP to non-GAAP operating income is dominated by two items. Stock-based compensation was $176.8 million in 2025, split $86.3 million into cost of revenue and $90.5 million into SG&A [2]. Amortization of purchased intangibles was $71.4 million — up from $29.5 million in 2024 [4] and $22.7 million in 2023 [5]. That threefold jump is not operational; it is the accounting tail of the $927 million NEORIS and First Derivative deals closed in late 2024, whose purchase price created $384 million of intangible assets now being written off against earnings (Capital and Alignment).
Sources: net income and free cash flow from the FY2025 Consolidated Statements of Cash Flows [6]; non-GAAP net income (~$645M) derived from the 94.7% adjusted-conversion figure management reported [7].
The 162% figure divides $613 million of free cash flow by $378 million of GAAP net income [8]. But the same amortization and stock compensation that suppress GAAP net income are added straight back inside operating cash flow, so they inflate the ratio at both ends. Management frames the conversion differently, and more honestly: $613 million of free cash flow is "a 94.7% adjusted net income conversion" — that is, roughly 95% of the ~$645 million of non-GAAP net income the company guides on [9]. A company converting adjusted earnings to cash at 95% is doing well, but the 1.6x figure the GAAP ratio implies overstates the conversion.
What is fair to exclude, and what is not
Not all of the $311 million adjustment is created equal. Two pieces genuinely belong outside a picture of cash economics: the $71.4 million of purchased-intangible amortization is a non-cash write-down of acquisition accounting, and the year's $25.9 million foreign-exchange loss reflects currency translation rather than operations [10]. Strip those out and the 9.5% GAAP operating margin does understate the underlying business.
The largest single piece does not belong outside the picture. Stock-based compensation of $176.8 million — 3.2% of revenue — is a real, recurring cost of paying a workforce of roughly 60,000 partly in equity [2]. It is non-cash to the company only because the cost is borne by shareholders through dilution instead. It appears twice in the bull case — once lifting non-GAAP EPS to $11.50, and again as an add-back inside the $613 million of free cash flow — and both times it makes the return look larger than an owner receives. EPAM buys back stock to offset that dilution, but at prices well above today's, so the offset has cost more than the dilution it neutralised (Capital and Alignment).
Sources: stock-based compensation totals for all three years from Note 15 [2]; purchased-intangible amortization from the FY2025 segment reconciliation [11], [12]; 2026 figures are management's guidance assumptions [13].
Charging stock compensation in full against free cash flow reframes the yield. On $613 million and roughly $4.5 billion of equity value, the headline yield is about 13.5%. Subtract the $177 million of stock compensation and free cash flow to owners is closer to $436 million, a yield near 9.6%. At $86 EPAM is priced below the value of its own cash flow standing still — owner free cash flow of ~$436m (reported FCF less a full $176.8m stock-comp charge) capitalised flat at 10% is worth ~$107 a share — so the price embeds a permanent ~3%/yr decline in owner cash flow even though FY2025 organic revenue still grew 4.9% in constant currency and management guides FY2026 organic growth to 3-6% (What the Price Implies).
Source: derived from FY2025 free cash flow and stock-based compensation [14], [2]; equity value per The De-Rating.
The parts that are genuinely clean
Where the accounting is not doing the work, EPAM's cash generation is high quality by the ordinary tests. Capital spending was $42.2 million in 2025 — under 0.8% of revenue — so operating cash flow of $655 million dropped almost intact to $613 million of free cash flow, with no reinvestment or hidden capex draining it [15]. The asset-light model the report opened with is real in the cash statement, not just the narrative.
Collections are equally undramatic. Trade receivables and contract assets rose 10.6% to $1.11 billion while revenue grew 15.4%, so days sales outstanding actually eased — management reported 72 days at year-end versus 70 a year earlier and 75 in the prior quarter [16], [17]. There is no channel-stuffing tell here: cash is being collected, not booked and awaited. Cash interest paid was $1.4 million, consistent with the debt-free balance sheet [18]. The quality question here is one of framing, not integrity.
Two caveats before crediting the run-rate
Watch item: 2025 operating cash flow was lifted about $144 million by a rise in accrued expenses and other liabilities — largely accrued compensation, which grew from $485 million to $608 million. That is a working-capital timing benefit that can reverse in a weaker year.
The $144 million swing in accrued liabilities flattered 2025 operating cash flow; accrued compensation and benefits alone rose $123 million on stronger second-half variable pay [19], [20]. Strip it out and normalized operating cash flow sits closer to $510 million — still comfortably above capital spending, but short of the reported figure.
The second caveat runs against the "GAAP understates everything" defence. Margins compressed even on the adjusted numbers management prefers: non-GAAP operating margin fell from about 16.5% in 2024 to 15.2% in 2025, so the earnings decline is not purely an amortization illusion — real mix and cost pressure sit underneath it, from higher variable compensation to the introduction of lower-utilization junior staff [21].
Sources: GAAP operating margin from the FY2025 MD&A results of operations [22]; non-GAAP operating margin from the Q4/FY2025 earnings call, with FY2024 derived from the 6.7% growth management reported [23].
The read
EPAM's free cash flow is real, cleanly collected, and barely touched by capital spending — but it is not the 150%-of-earnings gusher the GAAP ratio suggests. The right way to read it sits between the two numbers the company publishes. Purchased-intangible amortization and foreign-exchange losses genuinely depress GAAP earnings without touching cash, so the 9.5% reported operating margin understates the business. Stock compensation, the largest adjustment, does not: charge it in full and free cash flow converts at roughly 95% of adjusted earnings and yields near 10% rather than 13.5%. For the margin-of-safety question the report is built around, that still leaves an attractive cash return on a net-cash balance sheet, thinner than the headline and most sensitive to stock compensation.
The near-term direction of that cost is the wrong way: management guides 2026 stock compensation up to about $202 million even as intangible amortization eases to $69 million [24]. The read would firm up if stock compensation flattened as a share of revenue and the accrued-liability tailwind normalised while free cash flow held; it would weaken if the equity bill keeps climbing against slower revenue, because then the owner's yield erodes even as the reported one looks steady. The counter-case is fair: EPAM repurchases enough stock to shrink the share count, so a portion of the compensation cost is being funded rather than left to dilute — though, as the capital chapter showed, at prices that made the funding expensive.
Governance and Succession
For an investor who treats weak governance as a reason to walk away, EPAM's governance is a mark in favor of the case, not against it. The board is nine of eleven independent and is dismantling its own takeover defenses; executive pay fell hard with the stock and carries none of the usual problem features; the related-party record is clean; and the founder handoff was planned and internal. The qualifier is concentration — the founder remains Executive Chair, the largest insider, and the highest-paid executive.
This chapter examines the board, the September 2025 CEO succession, and how executives are paid — the stewardship questions that sit behind the margin-of-safety case (Capital and Alignment covered who owns the shares; this covers who controls the company and on what terms).
An independent board, dismantling its own defenses
EPAM's board has eleven directors, nine of them independent — every member except Executive Chair Arkadiy Dobkin and CEO Balazs Fejes [1]. Only independent directors serve on the audit, compensation, and nominating committees, each regular meeting reserves time for an executive session without management present, and there are no family relationships among the officers or directors [2]. Independent director Richard Michael Mayoras has served as Lead Independent Director since 2024, under a charter that assigns him responsibility for running executive sessions and ensuring the board functions independently of management [3].
Source: 2026 Proxy Statement (DEF 14A), Board Composition and Director Nominees [4].
Two features stand out because they run against the usual direction of travel. First, the board is unwinding its own classified structure: in response to a 2024 stockholder proposal and strong support for a 2025 declassification vote, EPAM amended its charter to phase out staggered three-year terms, so that by the 2028 annual meeting every director stands for election annually [5]. A staggered board is a standard takeover defense; removing it makes directors easier for shareholders to replace. Second, the board is asking shareholders to approve a charter amendment that would let holders of 25% or more of the voting power call a special meeting — a right they do not have today [6]. The move was itself prompted by a shareholder proposal seeking a lower 10% threshold, which the board recommends against [7]. The board is expanding shareholder rights, but on its own terms rather than the proponent's: a 25% threshold, not the 10% the proposal requested.
The Nominating and Corporate Governance Committee reported no related-person transactions approved or ratified since the beginning of 2025 — no founder side-deals, no supplier or customer arrangements tied to a director's own company.
Source: 2026 Proxy Statement (DEF 14A), Certain Relationships and Related Transactions [8].
The handoff
The central governance event of the last year is the CEO transition. Effective September 1, 2025, Balazs Fejes became President and CEO and co-founder Arkadiy Dobkin moved to Executive Chair, separating the Chair and CEO roles that Dobkin had held together since the company's early days [9]. The board frames it as the output of a deliberate succession process, and Fejes is an internal candidate of long standing — previously President of Global Business and Chief Revenue Officer, and before that co-head of global business, global head of banking and financial services, and Chief Technology Officer [10]. A promotion from within, of a two-decade insider, is the low-drama version of a founder transition.
What the split does not do is loosen the founder's grip. Dobkin remains Chair of the Board as well as Executive Chair, is still the largest insider at 2.9% of the shares against 3.8% for all directors and officers combined [11], and out-earned the sitting CEO in 2025: total compensation of $8.13 million as Executive Chair versus $5.24 million for Fejes [12].
Source: 2026 Proxy Statement (DEF 14A), Summary Compensation Table, fiscal 2025 [13].
The comparison flatters Dobkin somewhat — Fejes was CEO for only four months of 2025, so a full-year run-rate would narrow the gap — and the board's stated rationale, that the co-founder is the director most familiar with the business, is a reasonable one for keeping him engaged. But the substance is that influence and pay still concentrate on the founder a year into the transition.
This matters for one specific reader preference. A value investor who prizes a founder-CEO personally giving the quarterly updates now gets a partial version of that: the quarterly calls continue, but they are led by Fejes as CEO, not by the founder [14]. Dobkin remains the most senior voice in the boardroom rather than on the call. Whether that is a downgrade or simply a normal maturing of a 30-year-old company is a judgment the reader can make; the fact is that the founder-at-the-microphone setup is no longer intact.
Pay that moved with the stock
The most useful governance evidence is not a policy but an outcome: EPAM's pay actually fell when the stock did. The proxy's required pay-versus-performance disclosure indexes a $100 investment in EPAM against its peer group. By the end of 2025, that $100 in EPAM was worth $57.17 while the same $100 in the peer group had grown to $258.38 — the de-rating this report opens with, seen from the shareholder's side [15].
Source: 2026 Proxy Statement (DEF 14A), Pay Versus Performance table [16].
Crucially, executive pay did not stay whole while shareholders were cut in half. "Compensation actually paid" — the SEC measure that re-marks unvested equity to the year-end share price — swung with the stock. For Dobkin as the continuing named executive, it ran from a positive $26.7 million in 2021, when the shares peaked, to a negative $13.9 million in 2022 as they collapsed, before settling near $7.2 million in 2025 [17]. Equity-heavy pay that can post a negative number is pay that is genuinely at risk, which is the opposite of the guaranteed cash-and-repricing pattern that draws a governance objection.
Source: 2026 Proxy Statement (DEF 14A), Pay Versus Performance table (principal executive officer, Arkadiy Dobkin) [18].
The rest of the pay machinery is conventional in the ways that matter. Shareholders backed the say-on-pay vote with roughly 94% support at the 2025 meeting, and told the company in engagement that they liked the succession plan specifically [19]. Directors and employees are prohibited from pledging or hedging EPAM stock; there are no guaranteed bonuses, no single-trigger change-in-control vesting, no golden parachutes, and no excise-tax gross-ups; and a clawback policy allows recovery of incentive pay after a restatement regardless of fault [20]. In November 2025, alongside the succession, the board strengthened its stock-ownership guidelines: the CEO must hold six times base salary and non-employee directors ten times their retainer, with Fejes required to keep 100% of net shares until he reaches the threshold [21]. Independent directors are paid modestly and identically in equity — an annual $247,824 restricted-stock grant to each — which keeps board pay from tracking any single director's influence [22].
Independent Directors (of 11)
Say-on-Pay Support
CEO Pay Ratio (× median)
Insider Ownership
Sources: 2026 Proxy Statement (DEF 14A) — Director Independence p.25 [23]; Advisory Vote p.55 [24]; Pay Ratio p.73 [25]; Beneficial Ownership p.38 [26].
The one headline figure that looks large deserves context. EPAM discloses a CEO pay ratio of 186 to 1 for 2025, against a median employee — a full-time professional in Eastern Europe — earning $38,570, with roughly 95% of the workforce located outside the United States [27]. That ratio reflects the geography of a global engineering-labor model — a low offshore median denominator — more than it reflects an inflated numerator; the blended CEO figure that produces it is itself split across two executives during the transition year.
What would change the read
On the evidence, governance is not the reason a value buyer would avoid EPAM. The board is largely independent and is voluntarily shedding its own defenses; pay is disciplined, at genuine risk, and endorsed by shareholders; and there are no related-party entanglements around the founder. The standing caveat is concentration rather than conflict — the founder keeps the chair, the largest insider stake, and the top pay packet, and insider ownership overall is thin, so alignment leans on at-risk equity and reputation more than on a large personal holding.
Four things would move this from an asset to a liability, and each is checkable in the next proxy: a reversal or watering-down of the declassification and special-meeting commitments; the appearance of related-person transactions involving the founder or directors; a slide in say-on-pay support toward the 70-80% range that signals investor discontent; or evidence that the Executive Chair's continued dominance is constraining rather than supporting the new CEO. None of those is present today.
What the Price Implies
At $86 EPAM is priced below the value of its own cash flow standing still — owner free cash flow of ~$436m (reported FCF less a full $176.8m stock-comp charge) capitalised flat at 10% is worth ~$107 a share — so the price embeds a permanent ~3%/yr decline in owner cash flow even though FY2025 organic revenue still grew 4.9% in constant currency and management guides FY2026 organic growth to 3-6%. At the $86.38 traded price the operating business changes hands at an EV/operating-income multiple of 6.3 times, or 3.9 times on the adjusted line — the level normally attached to businesses in secular decline. Whether that price is right is the cyclical-versus-structural question the rest of the report has been building toward.
The cushion is real but thin, and it is most sensitive to one variable: the charge for stock compensation. Run owner free cash flow about 20% lower — stock compensation rising toward the guided $202m and the roughly $144m accrued-liability tailwind in 2025's cash flow reversing toward a normalised ~$510m of operating cash flow — and the no-growth value falls from ~$107 to about $91, essentially today's price; on that same conservative flow it takes a ~13% required return to justify $86 outright. The counter sits in the same breath: in a genuine structural-decline world EPS and the multiple compress together with no stable "normal" to anchor to, and the net cash is a partial floor rather than a full one, because a shrinking business tends to spend it defending revenue and buying stock at falling prices, as the Q1 2026 repurchases at $143.84 against today's ~$86 already show.
Share Price
Market Cap ($M)
Enterprise Value ($M)
Net Cash ($M)
Consensus Target
Sources: price and consensus target per market data, mid-July 2026; net cash of $1,296.1m cash less $25.0m debt from the FY2025 balance sheet [1]; enterprise value derived (market cap of ~52.4m shares × $86.38, less net cash).
The market capitalisation of roughly $4.53 billion rests on about 52.4 million shares — the count management guides to for 2026 after two years of buybacks [2]. Against that, EPAM held $1.30 billion of cash and $25.0 million of finance-lease debt at year-end, so about $1.27 billion of net cash — 28% of the market value — sits inside the equity [3]. Strip it out and the operating business is valued at about $3.26 billion. That cushion has since thinned: Q1 2026 buybacks of $264 million and a first-ever $140 million revolver draw [4] cut the cash balance to just over $1 billion, a use of the balance sheet examined in Capital and Alignment [5].
The multiples in one place
The valuation reads differently depending on which earnings line you use, so both belong on the page. On statutory GAAP figures — depressed by the intangible amortisation and stock compensation dissected in Earnings Quality — EPAM trades at 12.9 times trailing and about 10 times forward earnings. On the non-GAAP figures management and the sell-side actually forecast, it trades at 7.5 times trailing and 6.6 times forward.
Source: derived from FY2025 reported and non-GAAP results — revenue $5,457.1m, GAAP operating income $520.0m, GAAP diluted EPS $6.72 [6]; non-GAAP operating income $831m (15.2%) and non-GAAP EPS $11.50 [7] — against price and consensus 2026 estimates.
Two features stand out. The GAAP-to-non-GAAP spread is wide because 2024's acquisitions loaded the income statement with amortisation, so the honest range is 6.6 times forward at the low end to about 10 times at the high — not a single number. And EV/operating income of 6.3 times, or 3.9 times on the adjusted line, is a multiple normally attached to businesses in secular decline, not one whose non-GAAP operating income grew 6.7% in the year just reported [8].
The de-rating was a multiple story
The fall from the late-2021 peak of roughly $717 to $86 — about 88%, established in The De-Rating — happened while the earnings held up. GAAP diluted EPS was $8.15 in 2021 and $6.72 in 2025; non-GAAP EPS is higher now than it was then. Almost the entire decline was the multiple compressing, not the business contracting. That reframes the valuation question: the debate is not whether EPAM earned less, but whether a mid-single-digit multiple is the correct price for earnings that have, so far, held.
What zero growth is worth
The cleanest way to size the implied pessimism is to ask what EPAM is worth if its cash flow never grows again. Charging the full $176.8 million of stock compensation against the reported $613 million of free cash flow leaves about $436 million of free cash flow to owners — the conservative figure derived in Earnings Quality [9]. Capitalising that flat, forever, at a range of required returns, and adding back the net cash, gives a no-growth value per share:
Source: derived — owner free cash flow $436m (reported FCF $613m less $176.8m stock compensation) and reported FCF $613m [10], each capitalised with zero growth at the stated return, plus $1,271m net cash, over ~52.4m shares.
On the conservative owner cash flow, a 10% required return values a no-growth EPAM at about $107 — some 24% above the current price. The reported free cash flow, capitalised the same way, is worth about $141, almost exactly the consensus mean target. For $86 to be the right price on the conservative flow, the required return has to be about 13% — a steep hurdle for a debt-free, asset-light franchise — or the cash flow has to actually decline. Turned into an implied growth rate at a 10% return, the current enterprise value embeds owner cash flow shrinking roughly 3% every year in perpetuity. That is the arithmetic definition of "priced for decline."
Three ways the fork resolves
Whether that implied decline is too harsh depends on which way the fork resolves. The scenarios below hold the method fixed — non-GAAP EPS three years out, times an exit multiple — and let the story move both. The 2026 starting point is management's guided non-GAAP EPS of $12.98 to $13.28 [11].
Source: illustrative, derived from the FY2025 base and management's 2026 non-GAAP EPS guidance of $12.98–$13.28 [12]; EPS paths and exit multiples are assumptions, not forecasts.
The bear case is the structural read: AI compresses billable hours and price, organic revenue drifts flat-to-down, the non-GAAP margin slips toward the low-teens, and non-GAAP EPS erodes to about $10.50 while the market holds a distressed 6 times — roughly $63, or 27% below spot. The base case is the one Engineering Premium supports on the evidence to date: EPAM has converged to peer-level growth and margin, not fallen below it, so mid-single-digit growth plus continued buybacks lift non-GAAP EPS to about $15, and a still-cheap re-rating to 10 times implies roughly $150. The bull case needs AI-native demand to restore a growth premium and margins to head back toward 16–17%, taking EPS near $17.50 at a 13 times multiple — about $228, close to the Street's high mark of $235.
Two things about that spread matter more than the point values. First, the value is most sensitive to the exit multiple, which is itself a proxy for how that fork resolves: at a fixed $15 of EPS, each turn of multiple is about $15 of price. Second, the modelled downside of about 27% is milder than the base-and-bull upside of 74% to 164% — an asymmetry that exists because the multiple already sits near a floor.
The consensus frame
The sell-side sits closer to the base case than to either tail. Nineteen analysts carry a mean target of $139 and a median of $135 — about 61% above spot — with a high of $235 and a low of $85, and no sell ratings against eleven buys and eight holds.
Source: consensus of 19 analysts per market data, mid-July 2026; current price $86.38.
The mean target of $139 is worth reading against the no-growth work above: it lands almost on top of the value of EPAM's reported free cash flow capitalised flat at 10%. The Street, in other words, is underwriting a re-rating toward fair value on cash flow that barely grows — not a heroic growth recovery. That is a modest thing to require, and it is the same thing the base case requires: that EPAM's stall proves cyclical rather than terminal. The margin of safety is genuine at the level of the balance sheet and today's cash flow; it is contingent at the level of the multiple, and the multiple will move with the debate the corpus cannot yet settle.
Where the read can break
The asymmetry is real but not a guarantee, and the honest counter sits inside it. The bear column above is not the worst case. If AI resets the price of an engineer-hour across the industry, EPS and the multiple fall together, and there is no "normalised" earnings level to anchor to because the normal itself moves down. That is the pattern Engineering Premium documents in the pure-play cohort EPAM names among its competitors — Globant and Grid Dynamics among them [13] — where Globant's revenue growth collapsed from 15.3% to 1.6% in a single year. In that world the net cash is a partial floor, not a full one: a structurally shrinking business tends to spend its cash defending revenue and buying stock at prices that keep falling, exactly as the Q1 2026 repurchases at $143.84 — well above today's $86 — already show [14].
On the evidence assembled so far, the weight sits with the base case rather than the bear: the delivery force is still growing, utilisation is near 77%, the client base keeps broadening, and management guides 2026 organic growth of 2.5% to 5% with stable-to-higher margins [15]. What would move the read toward the bear column is concrete and checkable: two or more quarters of falling revenue per delivery professional on an organic, mix-adjusted basis; a non-GAAP operating margin breaking below the 15% guide floor; or organic growth failing to reaccelerate into the second half of 2026 that management says is back-end loaded.